

The landscape of corporate reporting is undergoing a fundamental transformation as the International Sustainability Standards Board (ISSB) moves closer to establishing a definitive global baseline for environmental, social, and governance (ESG) disclosures. For decades, the private sector has grappled with a fragmented "alphabet soup" of reporting frameworks, ranging from the Global Reporting Initiative (GRI) to the Sustainability Accounting Standards Board (SASB). However, the recent momentum behind the ISSB suggests that the era of voluntary, disparate reporting is ending, replaced by a rigorous, investor-focused system designed to treat sustainability data with the same level of scrutiny as financial audits.
At the heart of this movement is the International Financial Reporting Standards (IFRS) Foundation, which established the ISSB during the COP26 climate summit in Glasgow in November 2021. By leveraging the credibility of the IFRS—the body responsible for accounting standards used in over 140 jurisdictions—the ISSB has successfully positioned its frameworks, IFRS S1 and IFRS S2, as the bridge between sustainability performance and financial valuation. As of 2024, nearly 50 countries have signaled their intent to adopt or align with these standards, representing a coalition that accounts for approximately 60 percent of global gross domestic product (GDP).
The Foundations of a Global Baseline: Understanding S1 and S2
The ISSB’s strategy centers on two core pillars released in June 2023. IFRS S1 (General Requirements for Disclosure of Sustainability-related Financial Information) requires companies to communicate the sustainability-related risks and opportunities they face over the short, medium, and long term. Crucially, S1 is designed to be used in conjunction with financial statements, ensuring that sustainability data is not siloed in a separate marketing-heavy "sustainability report" but is integrated into the core narrative of the business’s health.
IFRS S2 (Climate-related Disclosures) is the first thematic standard, focusing specifically on climate change. It incorporates the recommendations of the Task Force on Climate-related Financial Disclosures (TCFD) and requires companies to disclose their greenhouse gas emissions across three categories: Scope 1 (direct emissions), Scope 2 (indirect emissions from purchased energy), and the often-controversial Scope 3 (emissions across the entire value chain). By mandating Scope 3 reporting, the ISSB has set a high bar for transparency, forcing companies to look beyond their immediate operations to the environmental impact of their suppliers and customers.
A Chronology of Rapid Institutional Adoption
The trajectory of the ISSB has been remarkably swift compared to traditional accounting standard-setting processes. Following its launch in late 2021, the board spent 2022 engaging in extensive global consultations, receiving over 1,400 comment letters from investors, corporations, and regulators. This feedback led to the finalization of the standards in mid-2023.
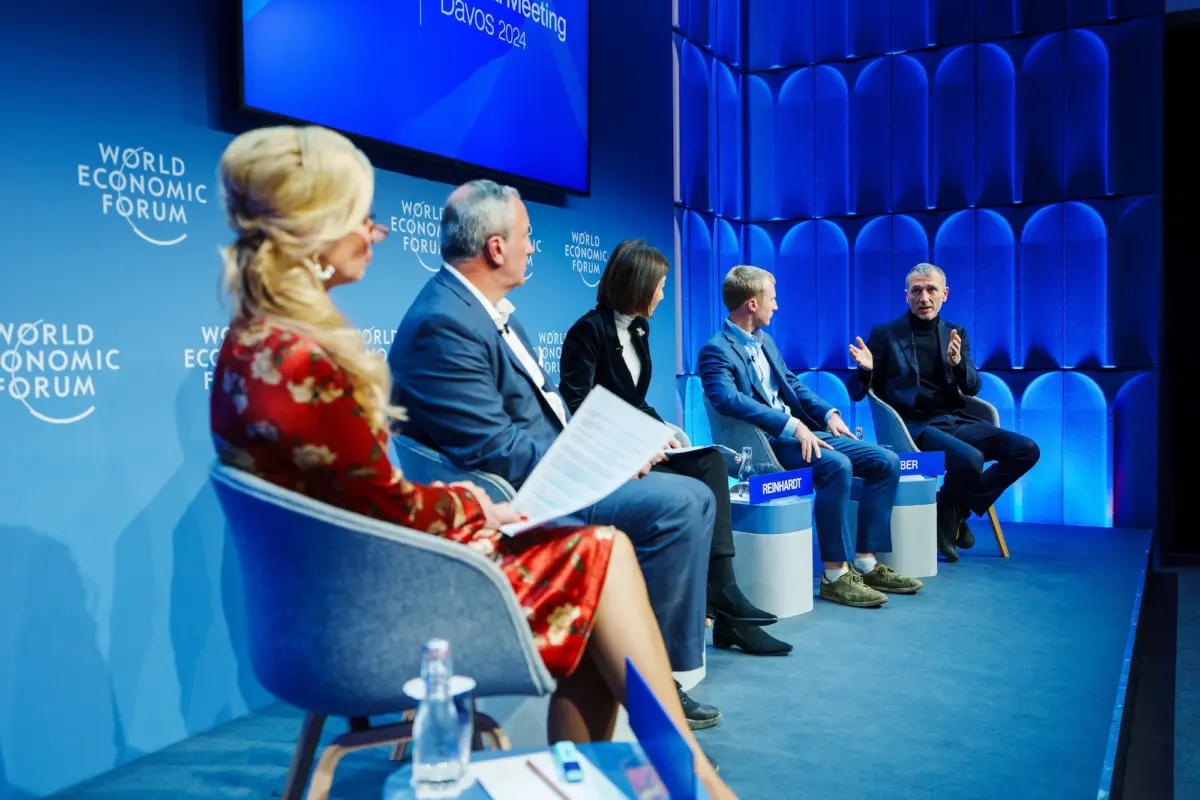
By early 2024, the World Economic Forum in Davos served as a significant platform for Emmanuel Faber, Chair of the ISSB, to advocate for the "global passport" initiative. This concept aims to harmonize the way different jurisdictions implement the standards to ensure that a multinational corporation can report once and satisfy the regulatory requirements of multiple countries. Throughout 2024 and heading into 2025, major economies including the United Kingdom, Australia, Canada, Brazil, and Singapore have moved from theoretical support to legislative implementation.
Regional Variations: The Challenge of Uniformity
While the ISSB seeks a "global baseline," the actual implementation across different nations reveals a complex tapestry of local adjustments. This "cherry-picking" or modification of the standards highlights the tension between global consistency and national sovereignty.
In the United Kingdom, the government has been a staunch supporter of the ISSB, yet it has opted for a more aggressive timeline. While the core ISSB framework allows for "transition relief"—such as delaying Scope 3 reporting for a year—the U.K. Financial Conduct Authority (FCA) has indicated that listed companies will face a rigorous "comply or explain" model that aims to phase out existing climate rules in favor of the ISSB framework by 2028.
In contrast, Australia’s implementation has seen the removal of industry-specific climate metrics originally found in the ISSB draft, focusing instead on broader thematic disclosures. Meanwhile, Brazil, one of the earliest adopters in South America, initially moved toward mandatory reporting but recently shifted to a "comply or explain" basis for June 2026, though with the significant caveat that reports must be independently assured.
Asia presents perhaps the most diverse adoption landscape. Singapore and Malaysia have transposed the ISSB standards largely unchanged, signaling to international investors that their capital markets are fully aligned with global norms. China, however, has taken a distinct path. While the Chinese Ministry of Finance has released draft standards based on the ISSB, it has maintained a focus on "double materiality."

The Materiality Debate: Financial vs. Double Materiality
A central point of contention in the global reporting evolution is the definition of "materiality." The ISSB focuses on "financial materiality"—how sustainability issues affect a company’s cash flows, access to finance, and cost of capital. This is an "outside-in" perspective designed primarily for investors and creditors.
The European Union, through its Corporate Sustainability Reporting Directive (CSRD), champions "double materiality." This approach requires companies to report not only on how climate change affects the company but also on how the company affects the planet and society (an "inside-out" perspective).
The divergence between the ISSB and the EU’s European Sustainability Reporting Standards (ESRS) created significant anxiety for multinational corporations. However, in April 2026, a proposal for stronger alignment between the two frameworks suggested that companies could potentially use a single report to satisfy both. While some industry groups in France and Germany initially feared this might create a two-tier system, the ongoing dialogue between the ISSB and the European Financial Reporting Advisory Group (EFRAG) suggests a gradual convergence toward interoperability.
Economic Implications and Investor Demand
The push for ISSB adoption is not merely a regulatory exercise; it is driven by a massive shift in capital allocation. According to data from the Global Sustainable Investment Alliance, sustainable investment assets now exceed $30 trillion globally. Institutional investors, such as BlackRock and Vanguard, have frequently called for standardized data to better price risk.
Without a global standard, investors face the "greenwashing" risk—where companies provide selective or misleading data to appear more environmentally friendly than they are. By mandating external assurance, as seen in the Mexican and Brazilian models, regulators are treating sustainability data with the same legal weight as financial audits. This shift is expected to reduce the "ESG premium" currently paid for data collection and allow for more efficient market pricing of carbon risks.
Future Horizons: Biodiversity and the SASB Legacy
The ISSB is not stopping at climate and general disclosures. The board is currently expanding its reach into nature-related risks. Drawing on the work of the Taskforce on Nature-related Financial Disclosures (TNFD), the ISSB is developing a practice statement for biodiversity, ecosystems, and ecosystem services. A draft of this statement is expected to be released in late 2024, signaling that the "E" in ESG is broadening from a narrow focus on carbon to a holistic view of natural capital.
Furthermore, the ISSB is in the process of updating the SASB standards, which provide industry-specific guidance for 77 different sectors. These updates are essential for ensuring that the metrics remain relevant in a rapidly changing technological and social environment. The ISSB’s Jurisdictional Working Group, which was expanded in 2025, continues to act as a diplomatic body, working to ensure that as more countries join the framework, the "global baseline" does not fragment into dozens of incompatible local versions.
Strategic Advice for Global Businesses
For corporations navigating this transition, the message from Davos and the IFRS Foundation is clear: waiting for mandatory legislation may be a strategic error. Voluntary adoption of the ISSB standards allows companies to build the internal data infrastructure necessary for high-quality reporting before the pressure of regulatory deadlines and legal liability intensifies.
Experts suggest a three-step approach for alignment. First, companies must conduct a gap analysis between their current disclosures and the requirements of S1 and S2. Second, they must address the "data deficit" in their supply chains to prepare for Scope 3 emissions reporting. Finally, they must integrate sustainability governance into the board level, ensuring that ESG risks are managed with the same oversight as financial risks.
As the ISSB continues to build its "global passport" for reporting, the goal is to create a world where a company’s sustainability performance is as transparent, comparable, and verifiable as its balance sheet. While regional variations and the materiality debate will continue to spark discussion, the momentum toward a unified global baseline appears irreversible, marking a new chapter in the history of global capitalism.
