

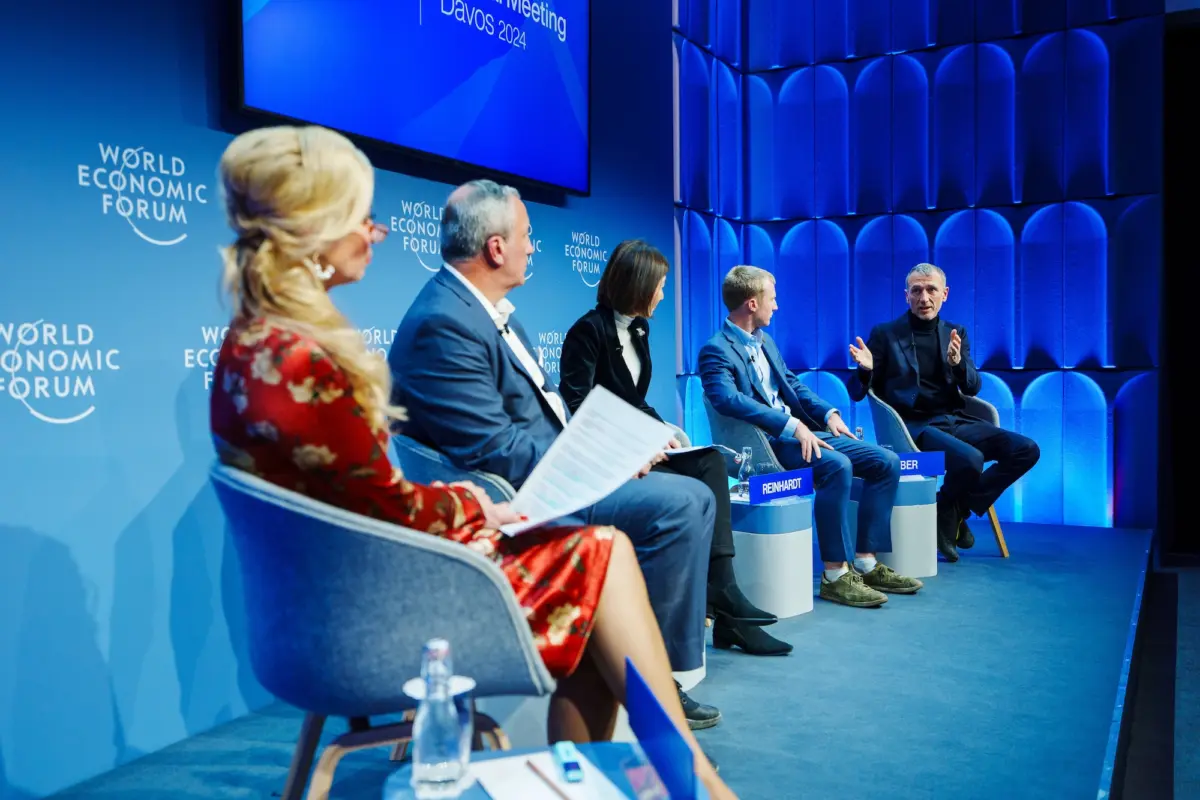
The International Sustainability Standards Board (ISSB) is rapidly consolidating its position as the primary architect of a global baseline for non-financial reporting, aiming to harmonize the often-fragmented landscape of sustainability-related risks and opportunities. As corporations face increasing pressure from institutional investors, regulators, and civil society to quantify their environmental and social impacts, the ISSB’s framework is emerging as the preferred technical bridge between corporate performance and financial materiality. Led by Chair Emmanuel Faber, the former CEO of Danone, the board has spent the last two years navigating a complex geopolitical environment to create a standardized language that allows investors to compare the sustainability profiles of companies across different jurisdictions.
The push for a unified standard comes at a critical juncture for the global economy. For decades, sustainability reporting was characterized by a "alphabet soup" of voluntary frameworks, including the Sustainability Accounting Standards Board (SASB), the Task Force on Climate-related Financial Disclosures (TCFD), and the Global Reporting Initiative (GRI). This fragmentation often led to "greenwashing" or inconsistent data that made it difficult for asset managers to accurately price climate risk into their portfolios. The ISSB, established under the auspices of the International Financial Reporting Standards (IFRS) Foundation, seeks to rectify this by integrating sustainability disclosures directly into the financial reporting ecosystem, treating environmental data with the same rigor as balance sheets and income statements.
A Chronology of Consolidation and Implementation
The journey toward a global baseline began in earnest during the COP26 climate summit in Glasgow in November 2021, where the IFRS Foundation officially announced the creation of the ISSB. The board’s mandate was clear: to deliver a comprehensive global baseline of sustainability-related disclosure standards that provide investors with information about a company’s sustainability-related risks and opportunities.
Following extensive public consultation, the ISSB issued its first two inaugural standards in June 2023: IFRS S1, which covers general requirements for disclosure of sustainability-related financial information, and IFRS S2, which focuses specifically on climate-related disclosures. These standards were designed to be used together, ensuring that companies provide a holistic view of how sustainability factors influence their long-term value creation.
By early 2024, the momentum behind these standards reached a fever pitch. At the World Economic Forum in Davos, Emmanuel Faber emphasized that the ISSB was not merely creating another reporting requirement but was instead building a "global passport" for corporate transparency. Since their release, nearly 50 jurisdictions—representing approximately 60 percent of global Gross Domestic Product (GDP)—have signaled their intent to adopt or align with the ISSB standards. This rapid uptake marks a significant shift in the regulatory landscape, moving from voluntary disclosures to mandatory, audited reporting in many of the world’s largest economies.
The Strategy of Neutrality: Adoption by Stealth
One of the primary reasons for the ISSB’s success is its perceived neutrality. Unlike the European Union’s Corporate Sustainability Reporting Directive (CSRD), which is often seen as being driven by a specific political and social agenda, the ISSB standards are framed as purely technical and investor-focused. By operating under the IFRS Foundation—the same body that oversees the accounting standards used in over 140 countries—the ISSB leverages existing institutional credibility.
This "adoption by stealth" has allowed the ISSB to gain ground in regions that might otherwise resist heavy-handed environmental regulations. In the United States, where climate disclosure rules have faced significant legal and political challenges, the ISSB framework provides a market-led alternative that many multinational corporations are adopting voluntarily to satisfy international investors. Similarly, in the Middle East and Africa, the framework is being used as a tool to modernize local capital markets and attract foreign direct investment by aligning with international best practices.
Regional Variations and the "Cherry-Picking" Challenge
Despite the goal of a universal baseline, the implementation of ISSB standards has not been uniform. National regulators often adjust the framework to suit local economic conditions, leading to a patchwork of "ISSB-aligned" rules rather than a single, identical set of requirements.
In the United Kingdom, the Financial Conduct Authority (FCA) has been a vocal supporter of the ISSB, planning to replace existing TCFD-based rules with ISSB standards for listed companies. However, the U.K. has opted for a "comply or explain" model for certain elements, with mandatory Scope 1 and 2 emissions reporting starting in 2028 and Scope 3 (value chain) emissions following in 2029.
Australia has taken a similar "climate-first" approach but has modified the standards to remove certain industry-specific metrics that were deemed less relevant to its domestic market. Meanwhile, in Latin America, Brazil and Mexico have emerged as early adopters. Brazil initially planned for mandatory reporting by 2026 but recently shifted to a voluntary "comply or explain" basis to give smaller companies more time to build the necessary data infrastructure. Mexico, on the other hand, has maintained a strict requirement for external assurance, meaning that sustainability reports must be verified by independent third-party auditors—a higher bar than the core ISSB standards currently require.
The most significant deviation, however, comes from China. In May 2024, China’s Ministry of Finance released a draft of its sustainability disclosure standards, which are heavily influenced by the ISSB but incorporate a "double materiality" perspective. This means that Chinese companies must report not only on how sustainability issues affect their financial performance but also on how their operations impact the environment and society at large. This aligns China more closely with the European Union’s philosophy than with the ISSB’s strictly financial focus.

The Materiality Debate: Financial vs. Double Materiality
At the heart of the global reporting debate is the concept of materiality. The ISSB operates on the principle of "financial materiality," which focuses on information that is likely to influence the decisions of investors, lenders, and other creditors. This approach asks: "How does the changing climate affect this company’s ability to generate cash flow?"
In contrast, the European Union’s CSRD utilizes "double materiality," which adds an outward-looking lens: "How does this company’s carbon footprint affect the planet?" Proponents of double materiality argue that financial risks cannot be fully understood without understanding a company’s broader impact on the world. They point out that today’s environmental impact is tomorrow’s financial risk.
Efforts to bridge these two philosophies have met with mixed results. In 2024, European regulators and the ISSB issued joint guidance to help companies navigate the overlap between CSRD and IFRS S1/S2. However, proposals to fully align the two systems were eventually dropped after European business groups raised concerns that investor-focused disclosures might be "obscured" by the sheer volume of impact-related data required by the EU. This tension suggests that while a global baseline is emerging, a truly unified global standard remains elusive.
Transition Relief and the Scope 3 Hurdle
For many corporations, the most daunting aspect of the new standards is the requirement to report Scope 3 emissions—the indirect emissions that occur in a company’s value chain, including both upstream suppliers and downstream customers. Recognizing the technical difficulty of gathering this data, the ISSB included "transition relief" provisions.
Under the core ISSB framework, companies are granted a one-year exemption from reporting Scope 3 emissions and are allowed to prioritize climate-related disclosures over other sustainability topics in their first year of adoption. This phased approach is intended to give firms time to implement new software systems, train staff, and engage with suppliers. However, as seen in the U.K. and Australia, national regulators are frequently extending these timelines even further, reflecting a pragmatic recognition that the "data gap" in global supply chains remains a significant hurdle.
Future Horizons: Nature, Biodiversity, and SASB Updates
The ISSB’s work is far from complete. Having established the foundation for climate reporting, the board is now turning its attention to other critical environmental and social issues. A major focus for late 2024 and 2025 is the development of standards for biodiversity, ecosystems, and ecosystem services. This work will draw heavily from the Taskforce on Nature-related Financial Disclosures (TNFD), reflecting the growing investor concern over nature loss and its potential to disrupt global supply chains.
Furthermore, the ISSB is in the process of integrating and updating the SASB standards, which provide industry-specific guidance for 77 different sectors. By maintaining these industry-specific lenses, the ISSB ensures that its standards remain relevant to the unique challenges faced by diverse sectors, from mining and oil and gas to technology and healthcare.
Analysis: The Implications for Global Capital Markets
The widespread adoption of ISSB standards represents a fundamental shift in how corporate value is assessed. For the first time, sustainability data is being moved out of the "glossy brochure" of corporate social responsibility reports and into the "engine room" of financial filings.
For multinational corporations, the benefits of this shift include reduced compliance costs over the long term as jurisdictions converge on a single baseline. It also provides a clearer roadmap for internal decision-making, allowing boards to identify and mitigate risks before they manifest as financial losses. For investors, the ISSB provides a more reliable toolkit for capital allocation, helping to distinguish between companies that are genuinely transitioning to a low-carbon economy and those that are merely paying lip service to sustainability.
However, the "fragmented adoption" model poses risks. If countries continue to cherry-pick elements of the ISSB standards, the goal of comparability will be undermined. Furthermore, the exclusion of "impact materiality" from the ISSB’s core mission may leave a gap in the data needed to address systemic global challenges like inequality and ecosystem collapse.
As the ISSB moves toward its 2027 goal of having over 50 countries on the path to adoption, the focus will shift from standard-setting to implementation and enforcement. The success of this global experiment will ultimately depend on whether national regulators can resist the urge to over-customize the standards and whether companies can rise to the challenge of providing transparent, high-quality data in an era of unprecedented environmental change.
