

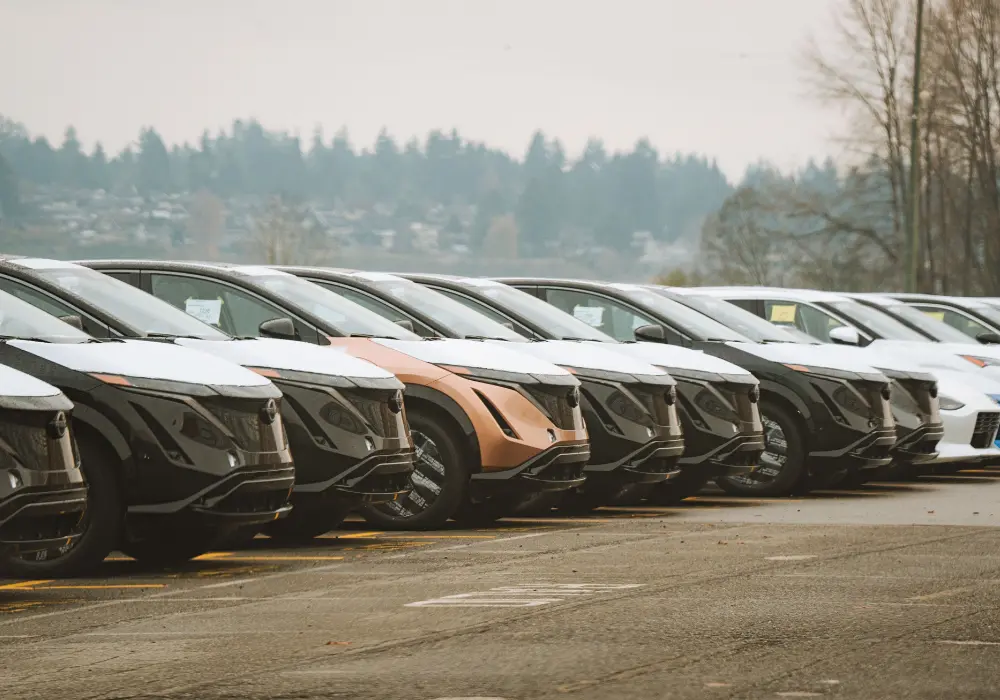
The American automotive landscape is witnessing a significant shift as electric vehicle (EV) sales begin a robust recovery following a period of market volatility. According to the latest data from Cox Automotive, U.S. consumers purchased 262,649 new electric vehicles in the third quarter of 2024, marking the second consecutive quarter of growth. This resurgence suggests that the "face-plant" experienced by the industry last year—driven by the expiration of federal tax incentives—may have been a temporary correction rather than a permanent cooling of consumer interest. As gasoline prices remain stubbornly high and automakers introduce more affordable, technologically advanced models, the transition to electric mobility appears to be entering a more stable and sustainable phase of growth.
The Economic Catalyst: Persistent High Fuel Costs
A primary driver behind the renewed interest in electric vehicles is the sustained pressure at the gasoline pump. Despite various geopolitical maneuvers, including pledges to stabilize oil markets ahead of critical election cycles, the national average for a gallon of gasoline has remained above the $4.00 mark for several months. This economic reality has fundamentally altered the total cost of ownership (TCO) equation for the average American commuter.
Data from AAA indicates that even when utilizing public charging stations—which typically command a premium over residential electricity rates—the cost per mile for an EV remains significantly lower than that of an internal combustion engine (ICE) vehicle. For many households, the monthly savings on fuel have begun to outweigh the higher upfront purchase price of electric models. This shift is particularly evident in regions where electricity rates have remained stable while oil markets continue to roil due to international tensions and supply chain constraints.
Industry analysts note that the psychological barrier of "$4.00 gas" often serves as a tipping point for consumer behavior. When fuel costs cross this threshold and remain there for an extended period, the long-term value proposition of an EV moves from a theoretical environmental benefit to a practical financial necessity.
A Chronology of the EV Market: From Boom to Bust and Back Again
To understand the current rebound, it is essential to examine the market’s trajectory over the past 24 months. The U.S. EV sector has navigated a dramatic "boom-and-bust" cycle influenced heavily by federal policy and consumer sentiment.
The 2023 Peak: In the third quarter of 2023, the U.S. saw a record-breaking 437,487 new EVs sold. This surge was largely fueled by a rush to capitalize on federal tax credits before significant changes to eligibility requirements took effect. Consumers accelerated their purchasing timelines to ensure they qualified for the $7,500 incentives, leading to an artificial inflation of sales figures.
The Early 2024 Slump: Following the expiration and tightening of these tax credits, the market hit what analysts termed the "tax credit cliff." Sales plummeted as the effective price of many popular models jumped overnight. This period was characterized by high inventory levels on dealer lots and a general narrative of "EV fatigue" among the public. During this time, major manufacturers, including Ford, reassessed their aggressive electrification timelines, leading to the cancellation of high-profile projects like the F-150 Lightning production run.
The Mid-2024 Recovery: By the second quarter of 2024, the market began to find its footing. The current third-quarter figures of 262,649 units represent a stabilization. While still below the 2023 record, the growth is now viewed as more "organic," driven by market fundamentals—such as fuel prices and better product availability—rather than temporary government subsidies.
The Surprising Dominance of the Used EV Market
Perhaps the most unexpected trend in the current recovery is the explosive growth of the used EV market. In August 2024, Americans purchased 44,350 used electric vehicles, a 26% increase from the previous month and a 15% increase year-over-year.
At the center of this surge is the Ford F-150 Lightning. Despite Ford’s decision to cancel production of the electric truck in late 2025 due to sluggish initial sales and high manufacturing costs, the vehicle has found a second life in the resale market. Analysts suggest that the Lightning’s initial failure was not due to a lack of utility or performance, but rather a price point that exceeded the reach of the traditional truck buyer.
"The F-150 Lightning was a victim of its own MSRP," says one industry consultant. "At $70,000 or $80,000, it was a hard sell for a work truck. But at a reduced used price, it becomes an incredible value proposition for contractors and families alike. We are seeing a ‘price discovery’ phase where the market is finally deciding what these vehicles are actually worth to the consumer."
This trend highlights a broader maturation of the EV ecosystem. A healthy secondary market is crucial for maintaining residual values, which in turn makes leasing and new-vehicle financing more attractive for the next wave of buyers.
Global Context: Record-Breaking Sales in Europe and Beyond
The U.S. rebound is part of a larger global trend toward electrification, though other regions are moving at a faster clip. In Europe, drivers purchased nearly 600,000 EVs in September 2024 alone, marking the continent’s largest sales month on record. According to Benchmark Mineral Intelligence, global EV sales rose by 17% in September compared to August, signaling that the transition is gaining momentum worldwide.
The European market has been bolstered by stricter emissions regulations and a more mature charging infrastructure. However, the underlying driver remains the same as in the U.S.: the volatility of fossil fuel prices. As European nations seek energy independence from traditional oil-producing regions, the push for EVs has become a matter of national security as much as environmental policy.
In contrast, the U.S. market remains somewhat insulated due to the ban on low-cost Chinese electric vehicles. While this protectionist stance helps domestic manufacturers like Ford, GM, and Rivian find their footing, it also means that U.S. consumers do not yet have access to the ultra-affordable $15,000 to $25,000 EV models currently saturating the Chinese and European markets.
Diversification of the Domestic Lineup
The sustainability of the current U.S. rebound is tied directly to the "next generation" of electric vehicles currently hitting showrooms. Automakers have learned from the mistakes of the first wave of EVs, which were often either high-end luxury playthings or small, range-limited hatchbacks.
Several key releases are defining this new era:
- Ford’s Affordable Pickup: Following the lessons of the Lightning, Ford is readying a new electric truck platform designed with a much lower price ceiling and improved manufacturing efficiency.
- Subaru’s Trailseeker: The new electric SUV from Subaru addresses one of the primary complaints of early EVs: charging speed. The Trailseeker features advanced battery architecture that allows for significantly faster DC fast-charging than the previous Solterra model.
- Rivian’s Expansion: Rivian has successfully introduced lower-priced variants of its popular R1S and R1T models, broadening its appeal beyond the ultra-premium segment.
These developments suggest that the industry is moving toward the "sweet spot" of the market—vehicles that offer 300+ miles of range, fast charging, and a price point that competes directly with mid-to-high-trim internal combustion vehicles.
Infrastructure and Policy: The Road Ahead
While the sales data is encouraging, challenges remain regarding infrastructure. The "sweet deal" of owning an EV is most apparent for those who can charge at home. For the millions of Americans living in apartments or urban environments without dedicated parking, the reliance on public charging remains a hurdle.
Government and private investment in the National Electric Vehicle Infrastructure (NEVI) Formula Program is beginning to bear fruit, with more high-speed chargers appearing along highway corridors. However, the reliability of these stations remains a point of contention. Industry experts argue that for the current sales growth to persist, the charging experience must become as seamless and dependable as the gasoline refueling experience.
Furthermore, the political climate continues to cast a shadow over the industry. With mid-term elections approaching, energy policy has become a central campaign issue. While the current administration has doubled down on electrification, any shift in legislative control could impact future incentives, charging infrastructure grants, and emissions standards.
Conclusion: The End of the Boom-and-Bust Cycle?
The data from the third quarter of 2024 provides a compelling case that the U.S. EV market has moved past its "awkward teenage years." The transition from a subsidy-dependent market to one driven by consumer demand and economic necessity is a critical milestone.
With gasoline prices showing no signs of a permanent retreat and a fresh wave of more affordable, capable electric models entering the market, the stage is set for steady, sustainable growth. The era of "face-plants" and "cliffs" may finally be giving way to a period of consistent market penetration. For the American consumer, the message is becoming increasingly clear: while the initial cost of entry may still be a hurdle, the long-term path to savings—and a more stable energy future—is increasingly electric.
