

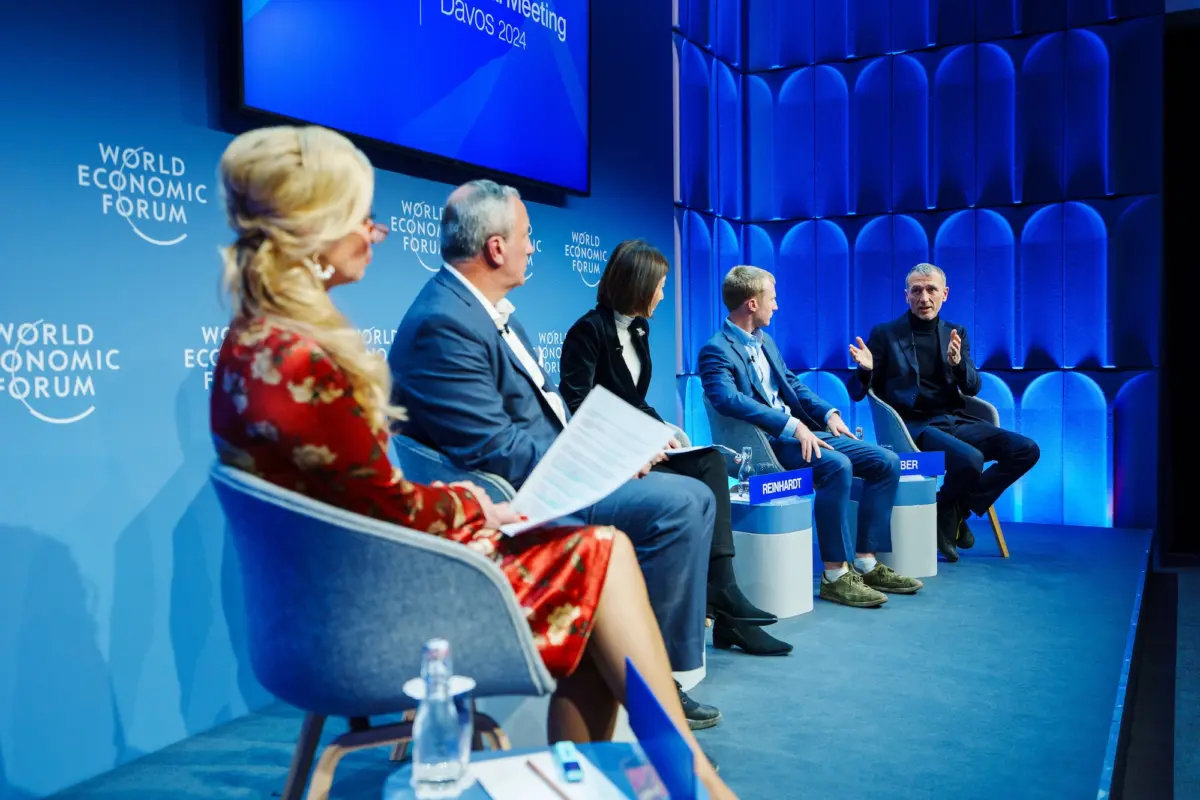
The International Sustainability Standards Board is inching closer to its goal of creating a global baseline for disclosing sustainability-related risks and opportunities that could impact company financial performance, signaling a transformative era for corporate transparency. As global capital markets increasingly demand comparable, reliable, and decision-useful information regarding environmental, social, and governance (ESG) factors, the work of the International Sustainability Standards Board (ISSB) has moved from the periphery of financial regulation to its very center. Led by Chair Emmanuel Faber, the former CEO of Danone, the ISSB is navigating a complex landscape of divergent national interests to establish a unified language for non-financial reporting.
At the 2024 World Economic Forum Annual Meeting in Davos, Switzerland, Faber emphasized that the era of "alphabet soup"—a confusing array of voluntary reporting frameworks like the Task Force on Climate-related Financial Disclosures (TCFD) and the Sustainability Accounting Standards Board (SASB)—is coming to an end. In its place, the ISSB is erecting a robust architecture designed to integrate sustainability data directly into the financial narrative of a business. This shift is not merely administrative; it represents a fundamental change in how value is measured in the 21st century, moving beyond short-term profit to include the long-term resilience of a company in the face of climate change and social shifts.
The Foundation of a Global Baseline: IFRS S1 and S2
The momentum behind the ISSB began in earnest at the 2021 UN Climate Conference (COP26) in Glasgow, where the IFRS Foundation announced the board’s creation. By June 2023, the ISSB released its inaugural standards: IFRS S1, which covers general requirements for disclosure of sustainability-related financial information, and IFRS S2, which focuses specifically on climate-related disclosures.
IFRS S1 requires companies to communicate the sustainability-related risks and opportunities they face over the short, medium, and long term. It is designed to ensure that companies provide information that is material to investors, lenders, and other creditors. IFRS S2, meanwhile, mandates the disclosure of a company’s exposure to climate-related physical risks—such as extreme weather events—and transition risks, such as new carbon taxes or shifts in consumer behavior. Crucially, IFRS S2 requires the disclosure of greenhouse gas emissions across Scope 1 (direct), Scope 2 (indirect from purchased energy), and Scope 3 (value chain), although the latter has been a point of significant debate and varying implementation timelines globally.
Since the release of these standards, close to 50 countries have taken steps to adopt or align their domestic reporting requirements with the ISSB framework. These jurisdictions represent approximately 60 percent of global gross domestic product (GDP), illustrating a massive shift toward standardized reporting. The endorsement by the International Organization of Securities Commissions (IOSCO) in July 2023 served as a critical catalyst, signaling to market regulators worldwide that the ISSB standards are fit for purpose in protecting investors and maintaining fair, efficient, and transparent markets.
A Chronology of Rapid Development
The timeline of the ISSB’s ascent reflects an unprecedented speed for international standard-setting:
- November 2021: The IFRS Foundation announces the formation of the ISSB at COP26, merging the Climate Disclosure Standards Board (CDSB) and the Value Reporting Foundation (VRF) into the new entity.
- March 2022: Exposure drafts for IFRS S1 and S2 are released for public comment, receiving thousands of responses from global stakeholders.
- June 2023: The final versions of IFRS S1 and S2 are published, marking the official launch of the global baseline.
- July 2023: IOSCO endorses the standards, calling on its 130 member jurisdictions—which regulate more than 95 percent of the world’s financial markets—to consider how they can incorporate the standards into their regulatory frameworks.
- January 2024: The standards officially become effective for annual reporting periods beginning on or after January 1, 2024, meaning the first wave of ISSB-aligned reports will emerge in 2025.
- May 2024: At the Beijing International Sustainability Conference, Emmanuel Faber confirms that jurisdictions representing over half of the global economy are actively moving toward implementation.
Adoption by Stealth: The Strategy of Neutrality
One of the primary reasons for the ISSB’s rapid acceptance is its institutional pedigree. As an arm of the IFRS Foundation, which oversees the accounting standards used in over 140 jurisdictions, the ISSB possesses an inherent credibility that regional or political bodies lack. By positioning itself as a "technical" and "neutral" standard-setter, the ISSB has avoided much of the political baggage associated with ESG regulations in the United States or the European Union.
In the United States, the Securities and Exchange Commission (SEC) faced significant legal and political pushback over its own climate disclosure rule, leading to a stay on the regulation and a scaling back of Scope 3 requirements. In the European Union, the Corporate Sustainability Reporting Directive (CSRD) has been criticized by some business leaders for its complexity and its "double materiality" approach—which requires companies to report not just on how sustainability affects them, but also on how they affect the world.
Amidst this friction, the ISSB has emerged as a "middle ground" for many nations. For countries in the Middle East, Africa, and parts of Asia, adopting the ISSB framework allows them to leapfrog local regulatory hurdles and align with international capital markets instantly. It provides a "global passport" for companies, theoretically allowing a firm listed in Singapore to provide the same sustainability data to an investor in London or New York without redundant effort.

The Patchwork of Global Implementation
Despite the goal of a "single global baseline," the reality of implementation has been characterized by regional nuances and "cherry-picking" of certain provisions. While the ISSB provides a core framework, national regulators retain the authority to modify the timing and scope of adoption to suit local economic conditions.
In the United Kingdom, the Financial Conduct Authority (FCA) has moved aggressively to replace existing climate reporting rules with ISSB-aligned standards. However, the U.K. government chose to strip out some of the "transition relief" measures provided by the ISSB, pushing for earlier adoption of certain disclosures to maintain its position as a global leader in green finance. Under current plans, U.K.-listed companies will be required to report direct emissions by 2028, with value chain emissions following shortly thereafter.
In contrast, China has taken a different path. While the Chinese Ministry of Finance has expressed support for the ISSB, it has deviated from the core "financial materiality" focus. Chinese regulators have indicated a preference for "double materiality," mirroring the EU’s approach by emphasizing the impact of corporate activities on the environment and society. This creates a unique test case for whether the ISSB standards can truly function as a baseline that accommodates more rigorous regional requirements.
Other nations have introduced their own variations:
- Australia: The government has mirrored the core ISSB framework but removed specific industry climate metrics to simplify the initial transition for its resource-heavy economy.
- Brazil: Initially a proponent of mandatory reporting by 2026, Brazil shifted to a "comply or explain" basis, though it maintains an expectation that reports be independently assured.
- Mexico: While the standards remain largely unaltered, Mexican regulators have added a requirement for external review and assurance, a step that is recommended but not mandated by the core ISSB framework.
The Materiality Debate and Corporate Impact
The tension between "financial materiality" and "double materiality" remains the most significant hurdle to total global harmonization. The ISSB’s focus on financial materiality—information that is likely to influence the decisions of investors—is designed to integrate sustainability into the traditional valuation models used by Wall Street and the City of London.
However, critics argue that ignoring a company’s impact on the planet (the "inside-out" view) is short-sighted. They contend that what is an environmental impact today often becomes a financial risk tomorrow. For instance, a company’s high water usage might not be financially material in a period of abundance, but during a drought, that environmental footprint becomes a direct threat to operational continuity and profitability.
For multinational corporations, this divergence means they must still navigate a dual-track reporting system. A European firm with significant U.S. operations may find itself reporting under the CSRD for its headquarters while using the ISSB framework to satisfy international investors. To mitigate this, the ISSB and the European Financial Reporting Advisory Group (EFRAG) have been working on "interoperability" guidance, aiming to ensure that companies can use a single data set to satisfy both sets of standards.
Future Horizons: Biodiversity and Beyond
The ISSB is not resting on the success of IFRS S1 and S2. During the 2024 Davos sessions, it became clear that the board’s next frontier is nature-related disclosures. As the world recognizes that climate change cannot be solved without addressing nature loss, the ISSB is developing a practice statement for biodiversity, ecosystems, and ecosystem services. This work is being closely modeled on the Taskforce for Nature-related Financial Disclosures (TNFD), with a draft expected to undergo public consultation in late 2024.
Furthermore, the ISSB is in the process of updating the SASB standards, which provide industry-specific guidance for over 70 sectors. By refining these metrics, the ISSB aims to provide companies with more granular tools to report on issues ranging from labor practices in the apparel industry to data security in the technology sector.
The ultimate goal, as stated by Faber and his colleagues, is to reach a point where "sustainability reporting" is no longer a separate discipline but is simply part of "reporting." By 2027, with over 50 countries expected to be on the path to adoption, the ISSB standards may well become the bedrock of a new global financial architecture—one where the risks of a warming planet and a changing society are priced into every investment decision. For businesses, the message is clear: the transition from voluntary to mandatory, and from fragmented to standardized, is no longer a future possibility but a present reality. Companies that fail to align with the ISSB framework risk not only regulatory scrutiny but also a potential increase in the cost of capital as investors gravitate toward those providing the clearest picture of their long-term viability.
