

The International Sustainability Standards Board (ISSB) is rapidly approaching a definitive milestone in its mission to establish a comprehensive global baseline for sustainability-related financial disclosures. As capital markets increasingly demand transparent, comparable, and reliable data regarding environmental, social, and governance (ESG) risks, the ISSB’s frameworks—IFRS S1 and IFRS S2—have emerged as the primary vehicles for harmonizing a historically fragmented reporting landscape. Since their official launch in June 2023, nearly 50 jurisdictions, representing approximately 60 percent of global gross domestic product (GDP), have initiated steps to incorporate these standards into their national regulatory frameworks. This shift marks a fundamental transition from voluntary, disparate "alphabet soup" reporting to a structured, investor-focused system designed to link sustainability performance directly to financial materiality.
The Genesis of a Global Standard: From COP26 to Davos
The trajectory of the ISSB began with a high-profile announcement at the United Nations Climate Change Conference (COP26) in Glasgow in November 2021. The International Financial Reporting Standards (IFRS) Foundation, which oversees the accounting standards used in over 140 countries, recognized that the lack of consistency in sustainability reporting was creating significant "noise" for global investors. To rectify this, the Foundation established the ISSB to sit alongside the International Accounting Standards Board (IASB), ensuring that sustainability disclosures would eventually carry the same weight and rigor as traditional financial statements.
To accelerate its development, the ISSB absorbed several pre-existing organizations, including the Value Reporting Foundation (which housed the SASB Standards) and the Climate Disclosure Standards Board (CDSB). By consolidating these entities, the ISSB avoided reinventing the wheel, instead building upon the Task Force on Climate-related Financial Disclosures (TCFD) recommendations, which were already widely supported by the G20 and the Financial Stability Board.
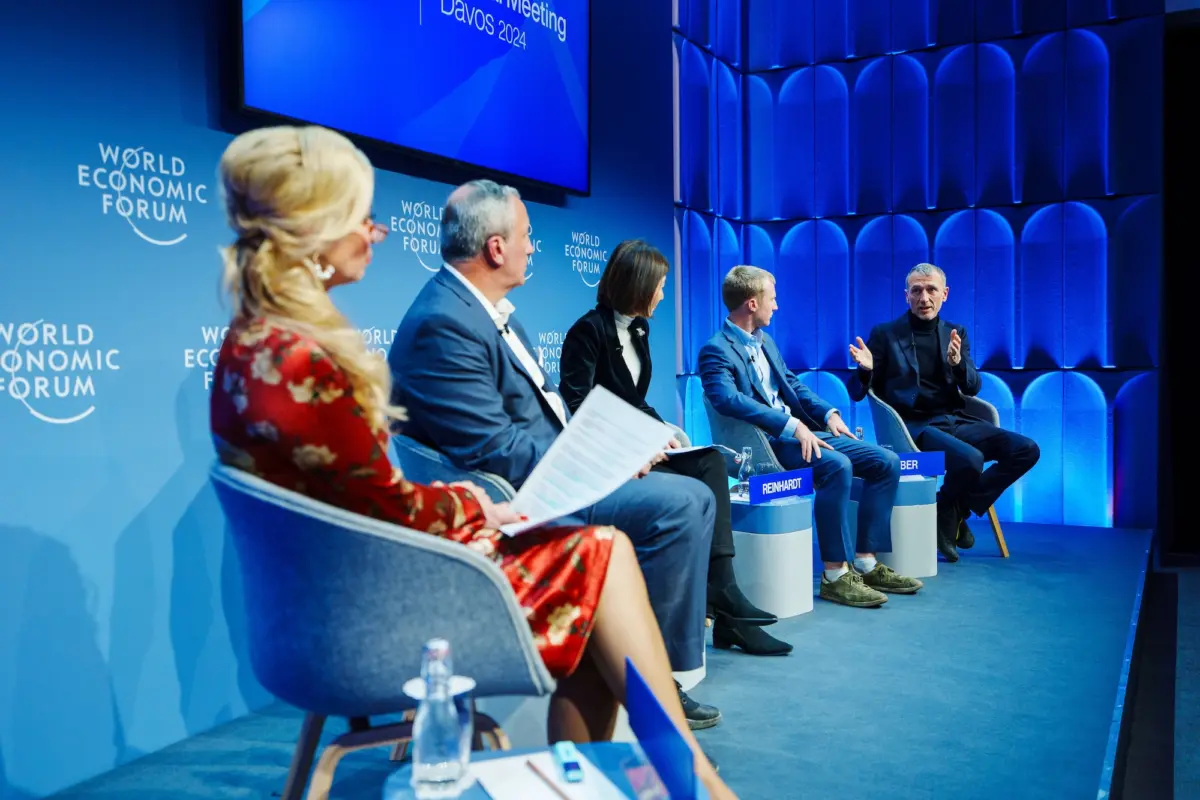
By the time Emmanuel Faber, Chair of the ISSB, addressed the World Economic Forum in Davos in early 2024, the board had successfully transitioned from a conceptual entity to a regulatory powerhouse. The focus at Davos shifted from "why" companies should report to "how" they can achieve compliance across multiple jurisdictions. The urgency is driven by the realization that climate change and social inequities are no longer peripheral concerns but core financial risks that can dictate a company’s cost of capital and long-term viability.
Understanding the Framework: IFRS S1 and IFRS S2
At the heart of the ISSB’s strategy are two core standards designed to provide a complete picture of a company’s sustainability profile.
IFRS S1, titled General Requirements for Disclosure of Sustainability-related Financial Information, sets out the overarching requirements for a company to disclose information about its sustainability-related risks and opportunities. It requires companies to communicate how they govern these risks, the strategies they employ to manage them, and the metrics and targets used to measure progress. Crucially, IFRS S1 adopts a "financial materiality" lens, meaning companies must report on issues that could reasonably be expected to affect their cash flows, access to finance, or cost of capital over the short, medium, or long term.
IFRS S2, Climate-related Disclosures, is the first thematic standard issued by the board. It focuses specifically on climate-related risks, including physical risks (such as extreme weather events) and transition risks (such as new carbon taxes or shifts in consumer demand). A significant requirement of IFRS S2 is the disclosure of greenhouse gas emissions across three scopes. Scope 1 covers direct emissions from owned sources; Scope 2 covers indirect emissions from the generation of purchased electricity; and Scope 3 covers all other indirect emissions that occur in a company’s value chain, including both upstream and downstream activities.
A Fragmented Path to Adoption: Regional Variations and Challenges
While the ISSB’s goal is a "global baseline," the actual implementation of these standards varies significantly across borders. National regulators are balancing the need for global alignment with local economic realities and political priorities. This has led to a phenomenon described as "adoption by stealth" or "modified adoption," where the core principles of the ISSB are embraced but the timelines and specific requirements are adjusted.
The United Kingdom and the "Comply or Explain" Model
The United Kingdom has been a vocal proponent of the ISSB, yet its approach to implementation is nuanced. The Financial Conduct Authority (FCA) and the UK government have moved to replace existing TCFD-aligned rules with ISSB-based standards. However, the UK has notably stripped out some of the "transition relief" measures initially proposed by the ISSB for voluntary use. Under the current roadmap, listed companies in the UK will be expected to report on Scope 1 and 2 emissions starting in 2028, with the more complex Scope 3 value chain emissions following in 2029. By 2030, a full suite of sustainability-related disclosures will be mandatory on a "comply or explain" basis, requiring firms to provide a rigorous justification if they fail to meet specific disclosure requirements.
China’s Shift Toward Double Materiality
Perhaps the most significant deviation from the ISSB’s core philosophy comes from China. While the Chinese Ministry of Finance has expressed support for a unified global standard, recent regulatory proposals suggest a lean toward "double materiality." Unlike the ISSB’s focus on financial materiality (how sustainability affects the company), double materiality also requires companies to report on their impact on the environment and society (how the company affects the world). This approach aligns more closely with the European Union’s Corporate Sustainability Reporting Directive (CSRD). China’s massive market size means its decision to prioritize social and environmental impacts alongside financial risks could create a dual-track system for multinational corporations operating within its borders.

Emerging Markets: Nigeria, Brazil, and Singapore
In emerging economies, the adoption of ISSB standards is often viewed as a way to attract foreign direct investment. Nigeria was one of the first countries to officially launch the ISSB standards, viewing them as a tool to improve corporate governance and transparency in its energy-heavy economy. Similarly, Singapore and Malaysia have integrated the standards into their listing requirements to maintain their status as premier global financial hubs.
Brazil, which initially moved toward mandatory reporting by 2026, recently adjusted its stance to a "comply or explain" model. Despite this slight rollback in the mandate, the Brazilian Securities and Exchange Commission (CVM) continues to encourage independent assurance—a third-party audit of sustainability data—to ensure the information provided to investors is as reliable as financial data.
The Materiality Debate: Financial vs. Impact Reporting
The tension between the ISSB’s financial materiality and the EU’s double materiality remains a central point of contention in the global reporting landscape. In April 2024, discussions were held regarding a potential "interoperability" agreement that would allow companies to satisfy both CSRD and ISSB requirements with a single report. However, these proposals faced pushback from European industry groups, including the Mouvement des Entreprises de France and the French Banking Federation.
These groups argued that a two-tier system might emerge where investor-focused financial disclosures would overshadow the broader social and environmental impact disclosures required by European law. Consequently, while the ISSB and the European Financial Reporting Advisory Group (EFRAG) have issued guidance on how to align the two frameworks, a full merger of the standards appears unlikely in the near term. For businesses, this means that while the ISSB provides a baseline, those operating in Europe must still navigate the more stringent and expansive requirements of the CSRD.
Implications for Global Business and Investors
For multinational corporations, the rise of the ISSB offers both relief and a new set of challenges. On one hand, the consolidation of various frameworks into a single baseline reduces the "reporting fatigue" caused by responding to multiple, overlapping investor requests. On the other hand, the requirement to disclose Scope 3 emissions and conduct climate scenario analysis requires a level of data sophistication that many companies currently lack.
Investors, meanwhile, are the primary beneficiaries of this shift. Standardized data allows for more accurate benchmarking of companies within the same sector, regardless of where they are headquartered. It also enables asset managers to better fulfill their own regulatory requirements, such as the Sustainable Finance Disclosure Regulation (SFDR) in Europe, which requires them to disclose the sustainability profile of their investment portfolios.
The Road Ahead: Biodiversity and the "Global Passport"
The ISSB is not resting on its laurels with climate reporting. Behind the scenes, the board is expanding its reach into new thematic areas. A significant focus for the remainder of 2024 and 2025 is the development of nature-related disclosures. The ISSB is currently working on a practice statement for biodiversity, ecosystems, and ecosystem services, drawing heavily from the Taskforce for Nature-related Financial Disclosures (TNFD) framework. This move acknowledges that nature loss and the degradation of ecosystems pose systemic risks to the global economy that are as significant as climate change.
Furthermore, the ISSB is pursuing a "global passport" initiative. Through its expanded Jurisdictional Working Group, the board is working with regulators to identify why certain countries feel the need to modify the standards during adoption. By addressing these local concerns through additional guidance or technical adjustments, the ISSB hopes to create a version of the standards that can be "transposed" unchanged across all major economies, effectively creating a universal language for sustainability performance.
The ongoing updates to the SASB Standards also remain a priority. With over 70 industry-specific guidelines, these standards provide the granular detail that investors need to understand the unique risks of sectors ranging from mining to software development. As the ISSB integrates and updates these industry standards, the goal is to ensure they remain relevant in a rapidly changing technological and environmental landscape.
Conclusion: A New Era of Corporate Accountability
The movement toward a global baseline for sustainability disclosures represents a fundamental shift in the definition of corporate transparency. The work of the ISSB, supported by the IFRS Foundation and endorsed by international bodies like IOSCO (International Organization of Securities Commissions), has successfully moved ESG reporting from the marketing department to the finance department.
While regional variations and the debate over double materiality will continue to pose hurdles, the momentum behind the ISSB is undeniable. For companies, the message is clear: sustainability reporting is no longer a voluntary exercise in corporate social responsibility. It is a rigorous financial discipline that requires robust data systems, board-level oversight, and a clear understanding of how the changing planet will impact the bottom line. As more countries adopt these standards through 2027, the "global passport" for reporting will likely become the standard operating procedure for any business seeking to compete on the international stage.
