

The International Sustainability Standards Board (ISSB) is currently advancing toward a definitive global baseline for disclosing sustainability-related risks and opportunities. This initiative, designed to provide a standardized framework for how environmental and social factors impact a company’s financial performance, represents a pivotal shift in the landscape of corporate reporting. As the world moves away from a fragmented "alphabet soup" of voluntary reporting frameworks, the ISSB standards—specifically IFRS S1 and IFRS S2—are emerging as the primary tools for institutionalizing non-financial data within the global financial system.
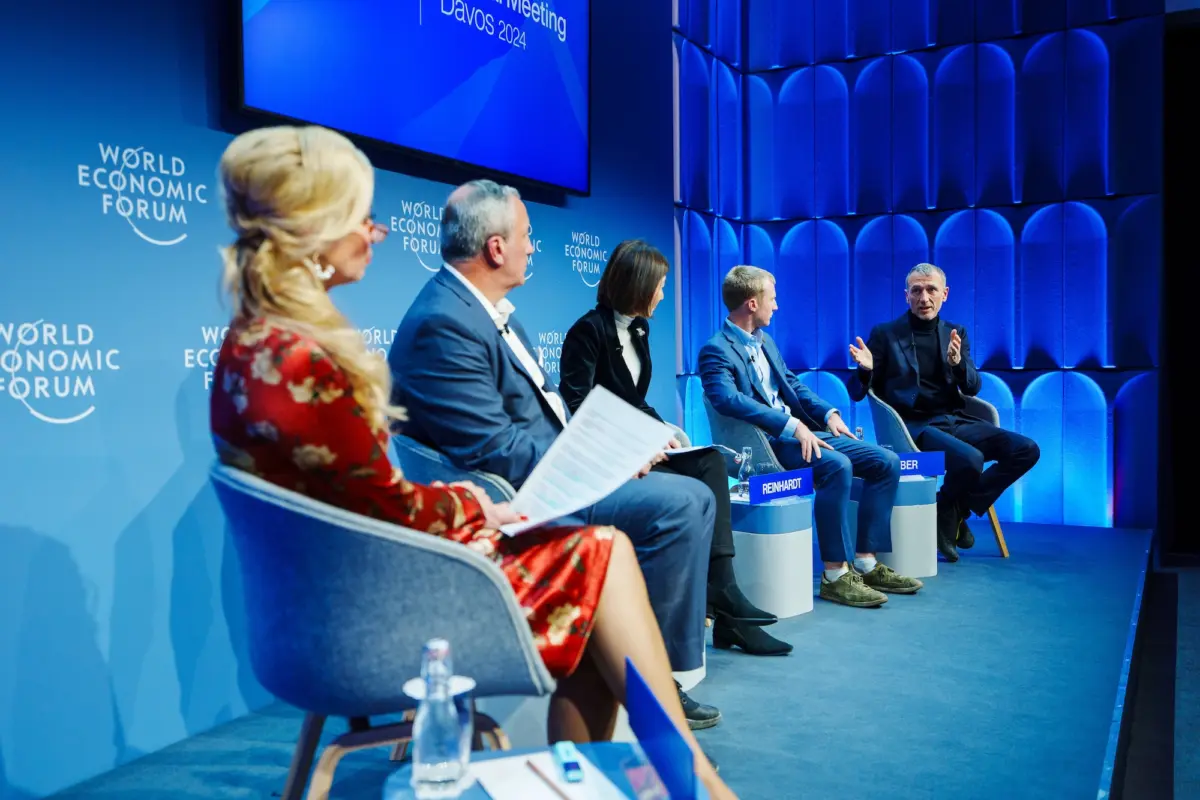
Since their official launch in June 2023, nearly 50 jurisdictions have taken significant steps toward adopting or aligning with these standards. This momentum was a central theme at the 2024 World Economic Forum in Davos, where ISSB Chair Emmanuel Faber highlighted the necessity of a common language for sustainability metrics. The goal is to move beyond disparate regional priorities and create a technical, neutral standard that allows investors to compare the long-term viability of companies across different borders and sectors.
The Evolution of Global Sustainability Reporting
The journey toward a unified reporting standard began in earnest at the 2021 UN Climate Conference (COP26) in Glasgow, where the IFRS Foundation announced the creation of the ISSB. The foundation, which already oversees the International Financial Reporting Standards used in over 140 jurisdictions, sought to apply the same rigor to sustainability reporting as it does to traditional financial accounting.
The timeline of development has been rapid. Following the 2021 announcement, the ISSB spent 18 months consolidating existing frameworks, including the Climate Disclosure Standards Board (CDSB) and the Value Reporting Foundation—which housed the Integrated Reporting Framework and the SASB Standards. In June 2023, the ISSB issued its first two inaugural standards: IFRS S1, which covers general requirements for disclosure of sustainability-related financial information, and IFRS S2, which focuses specifically on climate-related disclosures.
By early 2024, the focus shifted from creation to implementation. The board’s strategy has been to offer a "global baseline" that serves as a floor rather than a ceiling. This approach allows national regulators to build upon the ISSB standards with their own additional requirements, such as the European Union’s more expansive "double materiality" approach, while maintaining a core set of comparable data for global investors.
Strategic Adoption and the Concept of Neutrality
The rapid uptake of ISSB standards is largely attributed to the board’s perceived independence and technical focus. Unlike the European Union’s Corporate Sustainability Reporting Directive (CSRD), which is often viewed as a politically driven regulatory tool, or the volatile regulatory environment in the United States, the ISSB is positioned as a neutral, market-led body.
For many emerging economies, particularly in Africa and the Middle East, adopting the ISSB framework is a strategic move to attract international capital. By validating these standards, countries like Nigeria and Jordan are effectively elevating their local reporting requirements to international levels, signaling to global investors that their markets are transparent and risk-aware.
Market analysts observe that the ISSB has successfully navigated the "adoption by stealth" phase by building on existing, familiar frameworks like the Task Force on Climate-related Financial Disclosures (TCFD). Because many large corporations were already reporting under TCFD or SASB, the transition to IFRS S1 and S2 feels less like a radical disruption and more like a logical evolution of existing processes.
Regional Variations and the Challenge of Uniformity
While the momentum is undeniable, the path to a truly "universal" standard is complicated by regional adjustments. Over 40 countries are on the path to adoption, but the implementation is far from uniform. Some nations, including Chile, Malaysia, and Singapore, have opted to transpose the standards largely unchanged. Others have introduced significant modifications to suit local economic conditions.
In the United Kingdom, for instance, the Financial Conduct Authority (FCA) has moved to replace existing climate reporting rules with the ISSB framework. However, the U.K. government has demonstrated a "comply or explain" approach for listed companies, with a clear timeline: direct emissions (Scope 1 and 2) reporting is slated for 2028, with value chain emissions (Scope 3) following in 2029.
Australia has taken a different route, mirroring the core framework but removing specific industry climate metrics that were deemed less relevant to its domestic market. Meanwhile, Brazil, an early adopter, initially proposed mandatory reporting for 2026 but later shifted to a voluntary "comply or explain" basis, though it still emphasizes the need for independent third-party assurance to maintain data integrity.

The most significant deviation comes from China. In its adoption process, Chinese regulators have leaned toward "double materiality." While the core ISSB framework focuses on "financial materiality"—how sustainability affects the company—China’s approach encourages companies to also report on how the company affects the planet and society. This divergence highlights the ongoing tension between investor-focused reporting and broader stakeholder-focused accountability.
The Materiality Debate: Financial vs. Double Impact
The debate over materiality remains one of the most contentious issues in the sustainability space. The ISSB’s primary audience is the primary provider of capital: the investor. Therefore, its standards focus on information that is material to a company’s enterprise value.
In contrast, the EU’s CSRD mandates double materiality, requiring companies to disclose their impacts on the environment regardless of whether those impacts have an immediate financial consequence for the firm. In April 2026, attempts were made to align the CSRD and ISSB frameworks more closely to allow companies to produce a single, integrated report. However, these proposals faced significant pushback from groups like the Mouvement des Entreprises de France and the French Banking Federation, who feared that integrating the two might lead to a "two-tier" system where investor-focused data obscures broader impact data.
The failure to fully harmonize these two approaches means that global multinationals must continue to navigate a complex dual-reporting environment. However, many sustainability experts argue that the gap between financial materiality and impact materiality is narrowing. They suggest that today’s environmental impacts are tomorrow’s financial risks, a phenomenon clearly seen in the way carbon emissions have transitioned from a reputational concern to a direct financial liability through carbon taxes and climate litigation.
Economic Implications and the Global Passport Initiative
The economic stakes of this standardization are immense. Countries that have committed to the ISSB standards represent approximately 60 percent of global GDP. For multinational corporations, this alignment offers the potential for significant cost savings by reducing the need to prepare different sets of sustainability data for different jurisdictions.
To further this goal, the ISSB is working on what it calls a "global passport" for reporting. This initiative involves working closely with the Jurisdictional Working Group—which was expanded in 2025 to include more representative nations—to understand why countries are choosing to adapt or "cherry-pick" parts of the standards. By addressing these local concerns through further guidance and technical support, the ISSB hopes to minimize future variations and ensure that a report produced in one country is accepted by regulators and investors in another.
Future Horizons: Biodiversity and Industry-Specific Metrics
The ISSB’s work is far from finished. Having established the foundation for climate and general disclosures, the board is now turning its attention to other critical areas of environmental and social risk.
A major focus for late 2024 and 2025 is the development of nature-related disclosures. The ISSB is currently drafting a practice statement for reporting on biodiversity, ecosystems, and ecosystem services. This work is being closely modeled on the Taskforce for Nature-related Financial Disclosures (TNFD) framework, ensuring that the board continues its strategy of building upon existing, market-accepted tools.
Furthermore, the ISSB is in the process of updating the SASB Standards, which provide industry-specific guidance for over 70 sectors. These updates are essential for ensuring that the metrics remain relevant in a rapidly changing technological and environmental landscape. While a final timetable for these updates has yet to be released, the board has completed extensive stakeholder consultations to prioritize the first 12 industry standards.
Conclusion: A Unified Vision for the Future
The rise of the ISSB standards represents a maturing of the sustainability field. By shifting from voluntary "feel-good" reporting to a rigorous, investor-focused financial disclosure model, the ISSB is bringing sustainability into the heart of the capital markets.
For businesses, the message is clear: alignment with the ISSB framework is becoming a prerequisite for global competitiveness. Even in jurisdictions where adoption is not yet mandatory, the pressure from institutional investors—who manage trillions of dollars in assets and demand comparable, reliable data—will likely make the ISSB standards the de facto global requirement.
While regional variations and the materiality debate will continue to pose challenges, the movement toward a global baseline appears irreversible. As regulators continue to provide support and the ISSB expands its guidance into nature and social issues, the corporate world moves closer to a future where "non-financial" reporting is treated with the same seriousness and scrutiny as the balance sheet.
