

The International Sustainability Standards Board is inching closer to its goal of creating a global baseline for disclosing sustainability-related risks and opportunities that could impact company financial performance. As global markets grapple with the fragmented landscape of Environmental, Social, and Governance (ESG) reporting, the emergence of a unified framework has become a priority for institutional investors, regulators, and multinational corporations. The International Sustainability Standards Board (ISSB), established under the auspices of the International Financial Reporting Standards (IFRS) Foundation, is leading this charge, attempting to harmonize disparate reporting requirements into a single, cohesive language for non-financial performance.
The Davos Context: A Call for Transparency
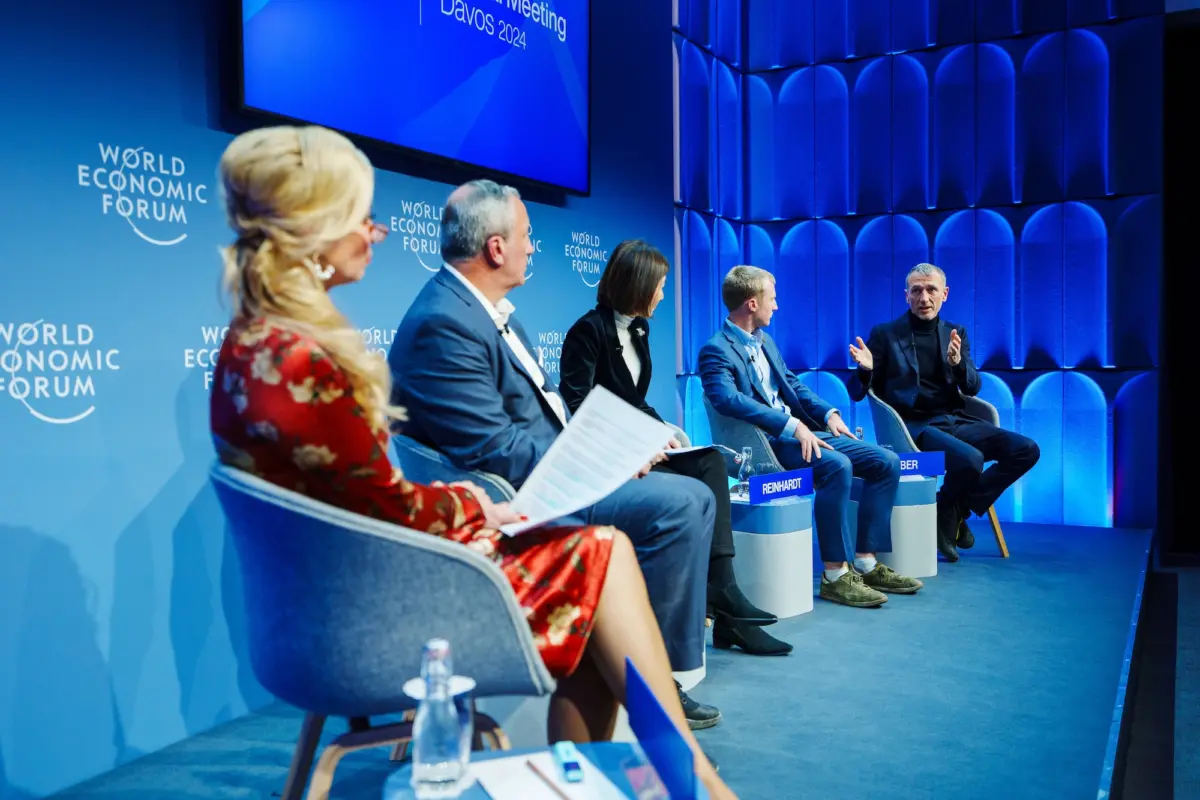
At the 2024 World Economic Forum Annual Meeting in Davos, Switzerland, the discourse surrounding sustainability shifted from voluntary commitments to mandatory compliance. Emmanuel Faber, Chair of the ISSB, emphasized that for sustainability metrics to be effective, they must be integrated into the core financial reporting mechanisms of a company. The session on sustainability metrics highlighted a growing consensus: the era of "alphabet soup" reporting—where companies could choose from a dozen different voluntary frameworks—is coming to an end.
The backdrop of this shift is a global economy increasingly vulnerable to climate-related risks and social upheavals. Investors are no longer satisfied with glossy CSR reports; they require rigorous, comparable, and auditable data to assess the long-term viability of their portfolios. Faber’s presence at Davos signaled that the ISSB standards are not merely technical suggestions but are intended to become the "global passport" for corporate transparency.
The Foundation of a New Era: IFRS S1 and IFRS S2
The architecture of the ISSB’s mission rests on two primary pillars: IFRS S1 and IFRS S2. Launched in June 2023, these standards were designed to provide a comprehensive global baseline.
IFRS S1: General Requirements for Disclosure of Sustainability-related Financial Information. This standard requires companies to communicate the sustainability-related risks and opportunities they face over the short, medium, and long term. Crucially, it focuses on "financial materiality," meaning information that could reasonably be expected to influence the decisions of primary users of general-purpose financial reports.
IFRS S2: Climate-related Disclosures. This is the first thematic standard, focusing specifically on climate change. It incorporates the recommendations of the Task Force on Climate-related Financial Disclosures (TCFD) and requires companies to disclose their greenhouse gas (GHG) emissions across Scope 1, Scope 2, and—most controversially—Scope 3 (value chain) emissions. It also mandates disclosures regarding physical risks (such as extreme weather) and transition risks (such as new carbon taxes or shifting consumer preferences).
A Timeline of Rapid Adoption
The journey toward a global baseline has been remarkably swift compared to the decades it took to harmonize international financial accounting standards.
- November 2021: The IFRS Foundation announces the creation of the ISSB at the COP26 climate summit in Glasgow.
- June 2023: The ISSB issues its inaugural standards, IFRS S1 and S2.
- July 2023: The International Organization of Securities Commissions (IOSCO) officially endorses the standards, calling on its members—who regulate 95% of the world’s financial markets—to incorporate them into their regulatory frameworks.
- Early 2024: Close to 50 jurisdictions, representing over 60% of global GDP, take formal steps toward adopting or aligning with the ISSB standards.
- 2025-2026: Mandatory reporting is set to begin in several major economies, including Brazil, Singapore, and Australia.
Adoption by Stealth: The Power of Independence
The ISSB’s success is largely attributed to its institutional heritage. Because it was established by the IFRS Foundation—the same body that oversees the accounting standards used in over 140 countries—it arrived with immediate credibility. Unlike regional regulations, such as the European Union’s Corporate Sustainability Reporting Directive (CSRD), the ISSB standards are perceived as neutral technical benchmarks rather than political mandates.
This neutrality has allowed for "adoption by stealth." National governments, particularly in the Middle East and Africa, have found that endorsing the ISSB framework allows them to elevate local reporting requirements to international standards rapidly. By doing so, they make their domestic companies more attractive to foreign capital without appearing to yield to the regulatory agendas of the EU or the United States.
The Challenge of Uniformity: Regional Variations
Despite the momentum, the "global baseline" is not yet a carbon copy across all borders. While countries like Chile, Malaysia, Nigeria, and Singapore have adopted the standards largely unchanged, other major economies are introducing variations.

In the United Kingdom, the Financial Conduct Authority (FCA) has moved to replace existing climate reporting rules with the ISSB framework on a "comply or explain" basis. However, the U.K. version stripped out much of the "transition relief" provided in the original standards. This means that while the ISSB allowed companies a grace period for reporting Scope 3 emissions, the U.K. timeline is more accelerated, with direct emissions reporting starting in 2028 and value chain emissions following in 2029.
In Australia, the government has mirrored the core framework but removed references to industry-specific climate metrics to better suit the nation’s resource-heavy economy. Brazil, initially an early adopter of mandatory reporting, recently pivoted to a "comply or explain" model for the first few years, though it still expects independent assurance of these reports.
The Materiality Divide: Financial vs. Double Materiality
Perhaps the most significant hurdle to a truly universal standard is the philosophical divide over "materiality." The ISSB focuses on financial materiality—how sustainability issues affect the company’s bottom line. In contrast, the EU’s CSRD and China’s emerging standards lean toward double materiality—which considers both the financial impact on the company and the company’s impact on the world (people and planet).
China’s deviation is particularly noteworthy. By favoring double materiality, Chinese regulators are signaling that corporate responsibility must serve broader social and national goals, not just investor interests. This creates a complex landscape for multinational corporations that must report under ISSB for their global investors while meeting double-materiality requirements in the EU and China.
In early 2026, proposals were floated to better align the EU’s CSRD with the ISSB framework to allow companies to produce a single integrated report. However, these proposals faced pushback from European banking and business federations concerned that investor-focused disclosures might obscure broader environmental impact data. For now, the two systems remain distinct but interoperable.
Implications for the Business Community
For global multinationals, the rise of the ISSB standards is a double-edged sword. On one hand, it promises to reduce the burden of reporting across multiple jurisdictions by providing a common language. On the other hand, the "baseline" is increasingly seen as a floor, not a ceiling.
Businesses are advised to take the following steps to navigate this transition:
- Assess Local Requirements: Determine if the ISSB standards are mandatory in your primary markets or if local variations (like those in the UK or Australia) take precedence.
- Gap Analysis: Map current ESG disclosures against IFRS S1 and S2 to identify where data collection systems need to be strengthened, particularly regarding Scope 3 emissions.
- Auditability: Unlike voluntary frameworks, the ISSB standards are designed to be audit-ready. Companies must ensure their non-financial data is subject to the same internal controls as their financial data.
- Investor Engagement: Since the ISSB standards are tailored for investors, companies should use these disclosures to tell a more compelling story about their long-term value creation and risk management.
Future Horizons: Biodiversity and Beyond
The ISSB is not resting on its climate-focused laurels. Recognizing that nature loss poses a systemic risk to the global economy, the board is currently developing a practice statement for biodiversity, ecosystems, and ecosystem services reporting. This work is being closely modeled on the Taskforce for Nature-related Financial Disclosures (TNFD) framework, with initial drafts expected to influence reporting as early as 2026.
Furthermore, the ISSB has taken over the responsibility for the Sustainability Accounting Standards Board (SASB) standards. These industry-specific standards provide detailed guidance for over 70 sectors, ensuring that a mining company isn’t reporting on the same metrics as a software firm. The board is currently consulting on updates to these standards to ensure they remain relevant in a rapidly changing economic environment.
Conclusion: Toward a Unified Financial Language
The efforts of the ISSB represent a monumental shift in how the world defines corporate success. By moving sustainability from the periphery of public relations to the center of financial reporting, the board is forcing a fundamental reassessment of risk and value. While regional variations and the materiality debate continue to pose challenges, the direction of travel is clear: sustainability is becoming an inextricable part of the global financial architecture. As Emmanuel Faber noted at Davos, the goal is not just more reporting, but better reporting that serves the needs of a world in transition. For companies and investors alike, the ISSB standards are becoming the essential map for navigating the complexities of the 21st-century economy.
