

Mortgage interest rates experienced a further ascent last week, a trend that significantly contributed to a renewed weakening in demand for home loans across the United States. The latest data from the Mortgage Bankers Association (MBA) reveals a discernible shift in borrower sentiment and activity, reflecting the persistent pressure of higher borrowing costs on both prospective homebuyers and existing homeowners contemplating refinancing. This development underscores the ongoing recalibration within the housing sector, which remains highly sensitive to fluctuations in the broader economic landscape and monetary policy.
Key Trends in Mortgage Applications
According to the Mortgage Bankers Association’s seasonally adjusted index, total mortgage application volume recorded a 1% decline from the preceding week. This represents a continuation of a pattern observed over recent months, where each upward tick in interest rates translates almost immediately into a measurable reduction in loan inquiries and applications. The core driver behind this decline was the average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances (up to $832,750), which rose to 6.78% last week, up from 6.77% the week prior. This marginal, yet impactful, increase pushed points — a fee paid to the lender at closing to obtain a specific interest rate — to 0.66 from 0.65, including the origination fee, for loans with a 20% down payment. This marks the highest interest rate observed for this benchmark product in three weeks, indicating a re-tightening of credit conditions after a brief period of slight moderation. The sustained elevation of these rates above the 6.5% threshold continues to exert considerable strain on housing affordability for a wide segment of the population.
The Sensitive Refinance Market
The segment of the mortgage market most acutely affected by weekly rate movements is refinance applications. In the latest reporting period, applications to refinance a home loan fell by 2% for the week. This drop is particularly stark when viewed in a year-over-year context, with refinance activity now 17% lower than during the same week one year ago. At that time, interest rates were approximately 9 basis points lower, highlighting the immediate and significant impact of even small rate increases on homeowners’ willingness to restructure their existing mortgages.
Joel Kan, vice president and deputy chief economist at the MBA, articulated the specific nuances of this decline in a recent release. "Refinance applications decreased, particularly for FHA and VA loans, and the average loan size for refinances was at its lowest since June 2025," Kan stated. The heightened sensitivity of FHA (Federal Housing Administration) and VA (Department of Veterans Affairs) loans to rate changes is noteworthy. These government-backed programs often cater to borrowers who may have lower credit scores, smaller down payments, or who are first-time homebuyers or veterans. For these groups, even a slight increase in interest rates can significantly impact their monthly payments, making refinancing less attractive or even financially unviable. The observation that the average loan size for refinances reached its lowest point since June 2025 further suggests that the pool of eligible borrowers who can benefit from refinancing under current conditions is shrinking, primarily comprising those with smaller loan amounts or specific financial circumstances. Many homeowners who secured historically low rates during the pandemic-era boom are effectively "rate-locked-in," finding it disadvantageous to trade their sub-4% or sub-5% mortgages for current rates nearing 7%.
Purchase Activity and Shifting Buyer Dynamics
While less volatile than refinance applications, demand for new home mortgages also experienced a decline. Applications for a home mortgage, representing potential purchases, fell by 0.3% for the week. This modest weekly drop becomes more significant when compared to the previous year, with purchase activity now 5% lower than the same week a year ago. This annual comparison underscores a persistent softness in the purchase market, even as rates fluctuate.
Despite the prevailing higher interest rates compared to the previous year, an interesting dynamic in buyer behavior has emerged. A separate report from Realtor.com indicated that fewer buyers are now utilizing all-cash transactions. This trend, while seemingly counterintuitive in a high-rate environment, suggests a broader cooling of the overall housing market. Less intense competition among buyers, which often characterized the frenzied market of 2021-2022, makes sellers more inclined to accept offers from buyers who require financing. This subtle shift provides a degree of relief for conventional buyers, as the "all-cash is king" mentality begins to wane, allowing more financed offers to gain traction. However, the affordability hurdle posed by high rates remains a significant barrier.
Joel Kan also noted the specific impact on certain buyer segments within the purchase market. "Purchase activity was down over the week, driven by a 7 percent decrease in FHA applications. The purchase market has also slowed these past two months," he added. The substantial decline in FHA purchase applications mirrors the trend seen in refinances, indicating that first-time buyers and those relying on more flexible lending programs are particularly vulnerable to the current rate environment. These borrowers often operate on tighter budgets, making them highly sensitive to even marginal increases in monthly mortgage costs. The overall deceleration of the purchase market over the past two months signals a broader retrenchment, as potential buyers grapple with the dual challenges of elevated home prices and rising borrowing costs.
A Brief Respite: Post-Survey Rate Movements
It is important to note that the MBA’s weekly survey captures data up to the previous Friday. Subsequent market movements can, and often do, introduce new dynamics. In a development occurring after the MBA’s reporting period, mortgage rates reportedly saw a slight decrease in the current week, according to a separate survey from Mortgage News Daily. This modest downward adjustment was particularly evident on Tuesday, primarily attributed to falling oil prices.
Matthew Graham, chief operating officer at Mortgage News Daily, explained the intricate connection: "News reports suggested progress in the peace process via Pakistani mediators. Oil prices dropped sharply in response, and bond yields followed the move. Bond yields correlate with mortgage rates." This explanation highlights the complex interplay of global events, commodity markets, and financial instruments that ultimately influence the cost of borrowing for homebuyers. Geopolitical stability, or the perception thereof, can impact oil prices, which in turn affect inflation expectations. Lower inflation expectations can lead to a decrease in the yield on U.S. Treasury bonds, particularly the 10-year Treasury note, which serves as a key benchmark for long-term mortgage rates. Thus, a fleeting moment of optimism on the geopolitical front can translate into a temporary, albeit welcome, dip in mortgage rates, offering a brief reprieve for some potential borrowers. However, such short-term fluctuations do not necessarily signal a sustained downward trend.
Broader Economic and Housing Market Implications
The consistent upward pressure on mortgage rates and the subsequent weakening of demand have far-reaching implications for the broader economy and the housing market.
- Housing Affordability Crisis Deepens: The most immediate impact is on housing affordability. With median home prices remaining stubbornly high in many regions, the added burden of elevated interest rates makes homeownership increasingly out of reach for a significant portion of the population, particularly first-time buyers and those in lower to middle-income brackets. The income required to qualify for a median-priced home with a 20% down payment has surged dramatically over the past few years, and rising rates only exacerbate this challenge.
- Reduced Market Liquidity and Transaction Volume: Weakening demand translates directly into fewer transactions. This can lead to a slowdown in market liquidity, with homes potentially staying on the market longer. Real estate agents, mortgage lenders, appraisers, and other ancillary service providers (e.g., home inspectors, movers) will likely experience reduced business volumes, potentially impacting employment in these sectors.
- Inventory Dynamics: While weakening demand might intuitively suggest an increase in available housing inventory, the situation is more nuanced. Many existing homeowners, having locked in historically low mortgage rates, are reluctant to sell their current homes, as doing so would mean buying a new property at significantly higher rates. This "lock-in effect" can ironically constrain new inventory, even as buyer demand cools, leading to a persistent imbalance in certain segments or geographies.
- Impact on New Construction: Developers and homebuilders are closely monitoring these trends. A sustained decline in purchase applications and buyer confidence could lead to a slowdown in new construction projects, impacting jobs in the construction sector and potentially contributing to longer-term housing supply shortages once demand eventually recovers.
- Monetary Policy Considerations: The Federal Reserve, while not directly setting mortgage rates, influences them through its broader monetary policy, particularly the federal funds rate, which impacts short-term interest rates and indirectly long-term yields. Persistent high inflation and a robust labor market have kept the Fed on a path of maintaining restrictive policy. While the housing market slowdown is a desired outcome of higher rates to cool inflation, policymakers will be watching closely to ensure the cooling doesn’t tip into a severe downturn that could destabilize the broader economy.
Perspectives from Key Stakeholders
- Prospective Homebuyers: For individuals and families aspiring to homeownership, the current environment presents formidable hurdles. Many are forced to either delay their home purchase, compromise on the size or location of their desired home, or accept significantly higher monthly payments than they would have faced just a couple of years ago. The decision to enter the market often involves difficult trade-offs.
- Existing Homeowners: Those with low fixed-rate mortgages are in a relatively secure position, but the option to leverage home equity through cash-out refinances or to move to a new home is significantly constrained. This creates a "golden handcuff" effect, where homeowners are incentivized to stay put, further dampening market activity.
- Mortgage Lenders: Lenders are navigating a period of reduced origination volume, which impacts profitability. They are adapting by focusing on niche products, streamlining operations, and competing more intensely for the shrinking pool of eligible borrowers.
- Real Estate Professionals: Real estate agents are facing a more challenging market, requiring greater skill in negotiations, pricing strategies, and guiding clients through complex financial landscapes. The rapid sales and bidding wars of previous years have largely receded, replaced by a more balanced, albeit slower, market.
Chronology and Context
The current state of the mortgage market is not an isolated event but rather the culmination of trends dating back several years. Following the historically low rates during the COVID-19 pandemic (which saw 30-year fixed rates dip below 3%), the Federal Reserve embarked on an aggressive campaign of interest rate hikes starting in early 2022 to combat surging inflation. This led to a rapid escalation in mortgage rates, with the 30-year fixed rate briefly touching 8% in late 2023, levels not seen in over two decades. While rates have moderated from those peaks, they have remained stubbornly elevated throughout 2024, 2025, and into 2026, largely due to persistent inflation and a resilient U.S. economy that has defied predictions of a recession.
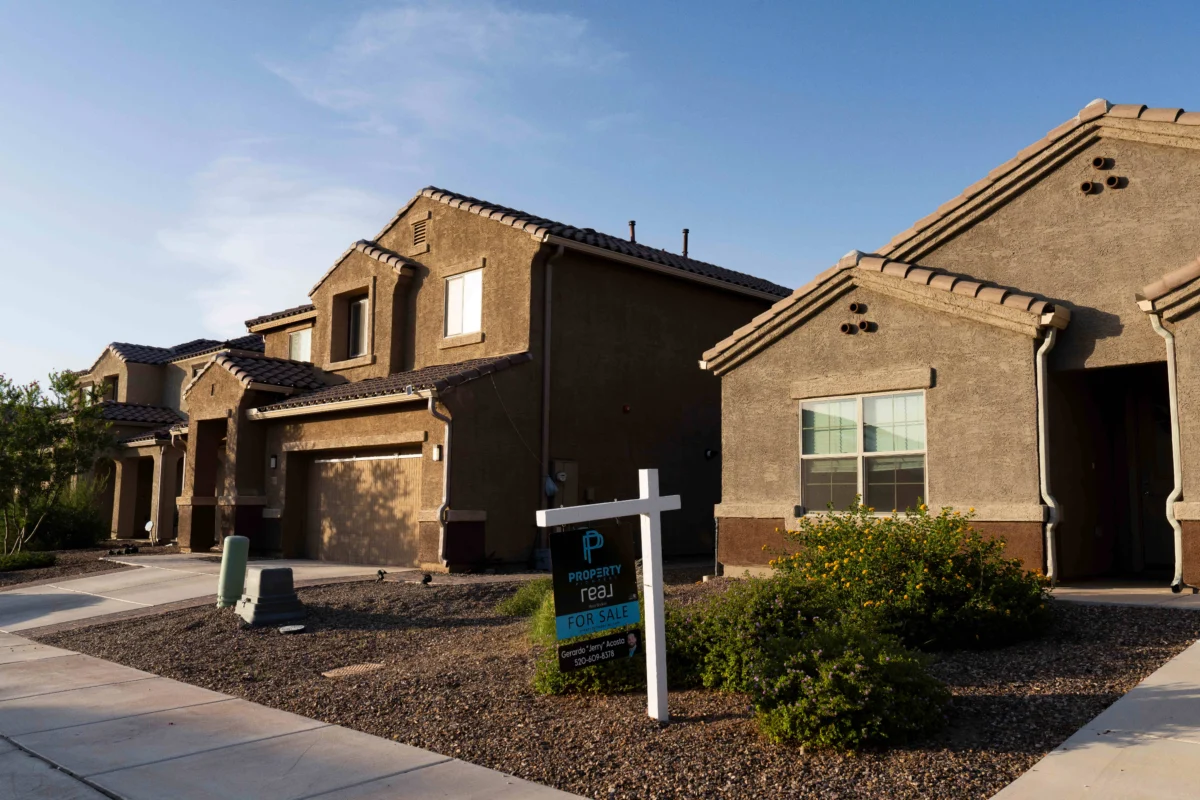
The image captured on Wednesday, August 5, 2026, of a "For Sale" sign outside a home in Marana, Arizona, serves as a poignant visual reminder of the ongoing activity in the housing market, albeit one increasingly shaped by these challenging economic headwinds. The MBA’s latest data, covering the week prior to this image, indicates that even in regions experiencing population growth, the fundamental economics of homebuying remain a significant determinant of market velocity. The reference to the average loan size for refinances being at its lowest since June 2025 further highlights a year-long trend of tightening conditions in the refinance sector.
Looking Ahead
The trajectory of mortgage rates and housing demand will largely depend on the future path of inflation, the Federal Reserve’s monetary policy decisions, and the broader economic performance. While the recent dip in rates tied to geopolitical news offers a fleeting glimpse of potential relief, sustained moderation would require a clearer signal that inflation is firmly under control, allowing the Fed to consider easing its restrictive stance. Until such a shift occurs, the housing market is likely to remain in a state of cautious adjustment, characterized by elevated borrowing costs, tempered demand, and an ongoing re-evaluation by both buyers and sellers of their roles in this evolving landscape. The housing market continues to be a critical barometer of economic health, and its performance will be closely watched by policymakers, investors, and the public alike.
