

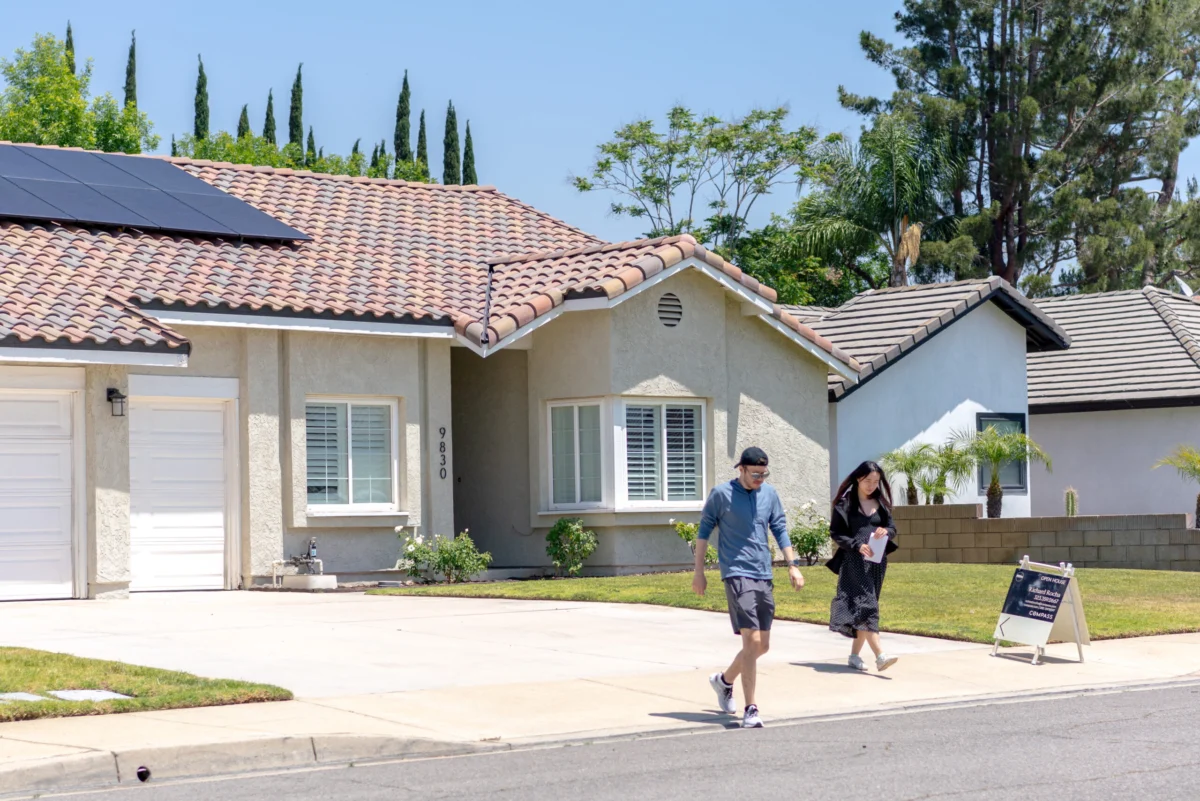
The residential real estate market is undergoing a significant recalibration, marked by a notable decline in the influence of all-cash transactions and a resurgence of buyers relying on mortgages. This evolving landscape signals a retreat from the intense competition that characterized the market for several years, providing new opportunities for a broader spectrum of prospective homeowners. As evidenced by a recent open house in Rancho Cucamonga, California, on Saturday, May 9, 2026, where prospective buyers were seen departing, the market dynamics are shifting towards a more balanced environment where cash is no longer an automatic winning hand.
A Market in Flux: The Fading Reign of Cash
For an extended period, particularly during the unprecedented housing boom spurred by the pandemic and subsequently exacerbated by rising interest rates, cash offers held an almost insurmountable advantage. The ability to close quickly, bypass financing contingencies, and offer certainty to sellers made cash "king" in highly competitive markets. However, recent data suggests this era is drawing to a close.
According to Realtor.com, which tracks both new and existing homes, the share of cash sales during the first four months of the current year stood at 31.4%, a noticeable dip from 32.3% recorded during the same period a year ago. This decline is not merely a proportional shift; the actual number of cash sales is falling at a faster rate than the overall market. Total home sales during this period were down 8.5% year-over-year, while the volume of cash transactions plummeted by 11.2%. This divergence underscores a fundamental change in buyer behavior and market conditions.
This shift coincides with a significant deceleration in home price growth. The national median price increased by a mere 0.2% annually, a stark contrast to the 1.8% growth observed in 2025 and a dramatic drop from the dizzying 15.4% peak witnessed in 2021. This moderation in prices, coupled with an increase in available inventory and a slight cooling of seller confidence, is creating a more level playing field for buyers who rely on mortgage financing.
"Cash buyers aren’t disappearing; they’re simply becoming less dominant as the housing market finds its footing," remarked Hannah Jones, senior economist at Realtor.com. "More inventory and moderating prices are giving financed buyers more opportunities to compete. Cash still matters, but today its biggest advantage isn’t just winning bidding wars. It’s also giving sellers confidence that a deal will close quickly and with fewer surprises." Her analysis highlights a transition from cash as a necessity for winning to cash as an attractive, but no longer exclusive, advantage.
Chronology of the Cash Craze: From Pandemic Boom to Current Adjustment
To fully appreciate the current market dynamics, it’s crucial to understand the trajectory that led to the dominance of cash.
- 2020-2021: The Pandemic-Fueled Boom: The onset of the COVID-19 pandemic, coupled with historically low interest rates, unleashed an unprecedented wave of demand in the housing market. Supply, already constrained, struggled to keep pace. Buyers, flush with savings or seeking more space, engaged in aggressive bidding wars. In this environment, an all-cash offer became the ultimate differentiator, allowing buyers to waive appraisal and financing contingencies, guaranteeing a swift and clean closing for sellers. Investors also entered the fray, leveraging cash to acquire properties for rental or quick resale.
- 2022-2024: Interest Rate Hikes and Persistent Cash Advantage: As inflation surged, the Federal Reserve embarked on a series of aggressive interest rate hikes starting in early 2022. Mortgage rates soared, significantly increasing the cost of borrowing for financed buyers. While this initially cooled overall market activity, cash buyers maintained their competitive edge. Their immunity to rising interest rates meant they could still make strong offers without the burden of higher monthly payments, effectively pricing out many financed buyers, particularly first-time homebuyers. The share of all-cash sales remained elevated during this period, often hovering around 30% or even higher in certain desirable markets. The National Association of Realtors (NAR) reported that the share of all-cash sales in July 2025 was 31%, indicating the sustained strength of cash offers even as the market began to normalize.
- 2025-2026: The Turning Point: The latter half of 2025 and early 2026 began to show definitive signs of a market shift. Inventory levels, while still below historical averages, started to gradually increase. Buyer fatigue, combined with continued high but stabilizing mortgage rates, led to fewer intense bidding wars. Sellers, facing a slightly less frenzied market, became more amenable to offers with financing, especially if those offers were robust and well-qualified. The NAR’s data for July of the current year showed a drop in all-cash sales to 26%, further cementing the trend of diminishing cash dominance.
This timeline illustrates a cyclical pattern where economic conditions, interest rates, and housing supply collectively dictate the power balance between cash and financed buyers. The current phase represents a move towards a more traditional market equilibrium.
Supporting Data and Economic Context
The weakening grip of cash buyers is underpinned by several interconnected economic indicators and market trends:
- Mortgage Rate Stability: While still elevated compared to the ultra-low rates of the pandemic era, mortgage rates have shown periods of stabilization or even slight dips from their peaks. This provides a degree of predictability and affordability for financed buyers, making the monthly payment more manageable and competitive. Lower rates reduce the appeal of an all-cash offer by narrowing the cost differential for borrowers.
- Increased Housing Inventory: New listings have gradually improved in many regions. More homes on the market mean buyers have more choices and face less pressure to make aggressive, all-cash offers to secure a property. This reduces the scarcity premium that once favored cash.
- Inflation and Consumer Confidence: Persistent inflation, even if moderating, can erode purchasing power and potentially reduce the pool of individuals with readily available cash for home purchases. Conversely, a stable economic outlook can encourage more people to enter the market with conventional financing.
- Investor Behavior: A significant portion of cash transactions traditionally comes from institutional and individual investors. As price appreciation slows and competition eases, the rapid returns that attracted cash investors during the boom period become less certain. This may lead some investors to pull back or re-evaluate their strategies, further reducing the overall share of cash transactions.
- Regional Disparities: While the national trend points to a decline in cash sales, some markets continue to defy this pattern. Pittsburgh, Austin, Texas, and San Francisco, for instance, have actually seen a rise in the share of cash transactions compared to a year ago. This isn’t merely due to fewer total sales; in these specific markets, the actual number of cash purchases increased. Such regional variations often reflect unique local economic drivers, specific housing supply constraints, or sustained investor interest in particular urban centers. Pittsburgh’s affordability and revitalization efforts, Austin’s tech boom, and San Francisco’s perennial high-value market could be contributing factors.
Expert Insights and Local Market Realities
The macro data is echoed by the experiences of real estate professionals on the ground. Dana Bull, a seasoned real estate agent operating in the competitive Boston area, confirms the national trend in her local market. "There was certainly a period of time when cash was king, which was right after interest rates climbed and aggressive bidding wars were commonplace. It’s been tapering off," Bull noted, reflecting on the shift.
Despite Boston remaining a highly desirable and often competitive market, Bull observes a reduction in the sheer volume of all-cash offers. She emphasizes that while the market is still demanding, the dynamics have evolved. For her clients, she now recommends a strategy of getting "pre-underwritten" rather than just "pre-approved" to enhance their competitiveness against cash offers in hotter neighborhoods. Pre-underwriting involves a more thorough review of a buyer’s financial situation by a lender, providing a higher level of assurance to sellers that the loan will close.
Bull’s anecdotal evidence provides compelling illustrations of this shift. "I had a client win a bidding war against about 15 offers this spring (financed with pre-underwriting), and my team member just beat out 27 other offers on a house in Arlington (also financed). I don’t think this would have happened in 2022-2025 during the cash craze," she explained. These instances highlight a critical development: the strength and certainty of a well-vetted financed offer can now rival, and even surpass, a simple cash offer in the eyes of a seller, particularly when faced with multiple options.
Broader Impact and Implications
The diminishing dominance of cash buyers carries significant implications for various stakeholders and the overall health of the housing market:
- For First-Time Homebuyers: This shift is overwhelmingly positive. First-time buyers, who disproportionately rely on mortgages, faced immense hurdles when competing against cash. A more balanced market reduces these barriers, potentially increasing homeownership rates and fostering greater equity. It means their carefully saved down payment and pre-approved mortgage stand a much better chance of success.
- For Sellers: While cash offers still present an attractive option due to speed and reduced risk, sellers may need to adjust their expectations. The market now rewards a strong, comprehensive offer more than just the immediate liquidity of cash. Sellers might need to be more patient, consider offers with reasonable contingencies, and prioritize buyers with robust pre-underwriting. The focus shifts from simply "getting a cash offer" to "getting the best overall offer."
- For Mortgage Lenders: The resurgence of financed buyers is a boon for the mortgage industry. It means increased origination volumes and a healthier pipeline of business. Lenders will continue to innovate with products and services, such as enhanced pre-underwriting processes, to empower their clients in a competitive, albeit less cash-dominated, environment.
- For Real Estate Agents: Agents must adapt their strategies to advise clients effectively. For buyers, this means emphasizing financial preparedness beyond basic pre-approval. For sellers, it involves setting realistic expectations and evaluating offers based on their holistic strength, not just the payment method.
- For Market Stability: A market less reliant on all-cash transactions is generally considered healthier and more sustainable. Excessive cash buying can inflate prices beyond what traditional buyers can afford, creating an artificial demand bubble. A more balanced mix of financed and cash transactions reflects genuine consumer demand and long-term investment, contributing to greater market stability and reducing volatility. It also suggests that a broader segment of the population can participate in homeownership, which has significant social and economic benefits.
The Future Outlook: A New Normal?
While the "cash is king" era may be fading, cash will always retain a place of significance in real estate transactions due to its inherent advantages of speed and certainty. However, the market appears to be settling into a "new normal" where financial preparedness and strong conventional offers can effectively compete.
The trajectory of this trend will depend on several factors, including future interest rate movements, the pace of new housing construction, and broader economic conditions. Should interest rates fall significantly, it could further empower financed buyers. Conversely, an unexpected economic downturn or credit crunch could once again elevate the appeal of cash as a safe haven.
For now, the landscape suggests a welcome shift towards greater accessibility and competition for a wider range of homebuyers. As the market continues to evolve, staying informed about these dynamics is crucial for anyone involved in buying or selling property. For those seeking deeper insights into the opportunities emerging in this changing real estate landscape, CNBC’s Property Play with Diana Olick offers weekly coverage delivered directly to your inbox. Subscribe to get access today and navigate the evolving market with expert guidance.
