

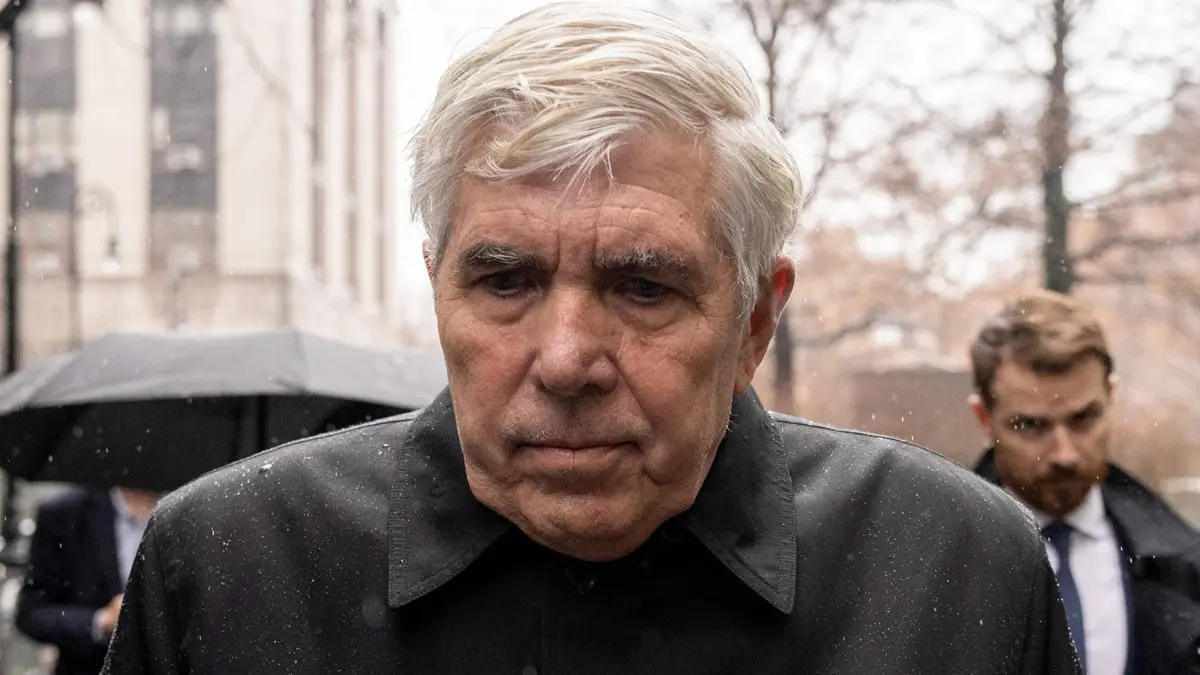
Ken Leech, the former co-chief investment officer at Western Asset Management Co. (WAMCO), has reached a $3 million settlement with the U.S. Securities and Exchange Commission (SEC) to resolve a lawsuit alleging he engaged in fraudulent "cherry-picking" of trades. The settlement, which requires judicial approval, addresses accusations that Leech unfairly allocated profitable trades to certain clients while burdening others with losses, thereby potentially steering over $600 million in gains to favored accounts. Leech has agreed to the penalty without admitting or denying the SEC’s allegations.
This resolution marks a significant development in a case that has cast a shadow over one of the world’s largest fixed-income asset managers. The SEC’s complaint detailed a pattern of alleged misconduct that, if proven, represents a profound breach of fiduciary duty – the legal obligation to act in the best interests of clients. Brent Wilner, associate director of the SEC’s Los Angeles Regional Office, characterized the conduct as an "egregious breach of fiduciary obligations to their clients," underscoring the gravity of the charges.
The allegations center on a practice known as cherry-picking, where a trader allocates profitable trades to specific client accounts while assigning losing trades to others. This selective allocation can create a significant advantage for favored clients, enhancing their returns at the expense of those who are less fortunate or intentionally disadvantaged. In Leech’s case, the SEC claimed this practice was not an occasional error but a systematic approach that benefited certain investors while harming others, over a period of years.
A Timeline of Allegations and Resolutions
The legal proceedings against Ken Leech and Western Asset Management have unfolded over an extended period, with key milestones shaping the current landscape.
Initial Investigation and SEC Action: The SEC’s investigation into Leech’s trading practices began, leading to formal allegations of fraud and breaches of fiduciary duty. These investigations typically involve reviewing trading records, client communications, and internal firm policies.
WAMCO’s Settlement: In June of the previous year, Western Asset Management itself agreed to a substantial $100 million settlement with the SEC. This resolution addressed the firm’s alleged failure to adequately detect and prevent Leech’s trading patterns. Furthermore, WAMCO committed to establishing a fund for the distribution of monies to investors who were adversely affected by the alleged cherry-picking. At the time of their settlement, WAMCO stated that the agreement allowed the firm "to put this matter behind it and focus fully on its clients," while also emphasizing that they did not admit to the SEC’s findings. This move by the firm suggests an effort to contain the reputational and financial damage while also signaling a commitment to rectifying any systemic issues.
Criminal Charges and Guilty Plea: In parallel with the SEC’s civil action, Leech faced criminal charges. In June of the same year as WAMCO’s settlement, Leech pleaded guilty to lying to SEC investigators during the regulator’s probe into his trading activities. This guilty plea signifies an acknowledgment of wrongdoing in the context of obstructing the regulatory investigation, which is a separate but related offense. Sentencing in this criminal case is anticipated in the coming weeks, adding another layer of legal consequence to Leech’s actions.
Leech’s Civil Settlement: The most recent development is Leech’s agreement to the $3 million civil settlement with the SEC. This resolves the agency’s claims of fraudulent cherry-picking, though it is important to note that the settlement is contingent upon approval by a judge. His legal team has declined to comment on the specifics of this agreement.
Understanding Cherry-Picking and Fiduciary Duty
The concept of cherry-picking in financial markets is particularly concerning because it violates the fundamental principles of fair dealing and fiduciary responsibility. Investment managers owe their clients a duty of loyalty and care, meaning they must act with undivided loyalty and in the best interests of their clients. This includes ensuring that all investment decisions are made impartially and that the allocation of trades is equitable.
When a manager cherry-picks, they are essentially playing favorites. This can manifest in several ways:
- Preferential Treatment: Profitable trades might be directed to accounts of clients who are favored, perhaps due to their size, relationship with the manager, or other undisclosed reasons.
- Loss Allocation: Conversely, losing trades might be strategically placed in the accounts of clients who are less likely to complain or whose losses will have a less immediate impact on the manager’s overall performance metrics.
- Market Manipulation: In some extreme cases, cherry-picking can be part of a broader scheme to manipulate markets or create artificial performance for certain accounts.
The SEC’s allegations against Leech suggest a pattern of such behavior, where gains were allegedly "steered" to favored clients, implying intent and a deliberate effort to benefit some at the expense of others. The scale of the alleged gains, over $600 million, highlights the significant financial impact this practice could have had on investors.
The Role of Compliance and Oversight
The case also raises critical questions about internal controls and compliance within large asset management firms. The SEC’s action against WAMCO points to a failure in the firm’s systems to detect and prevent Leech’s alleged misconduct. This suggests potential weaknesses in:
- Trade Allocation Systems: Ensuring that algorithms and human processes for allocating trades are fair and transparent.
- Surveillance and Monitoring: Implementing robust systems to monitor trading activity for suspicious patterns.
- Whistleblower Protections: Encouraging employees to report potential misconduct without fear of retaliation.
- Independent Oversight: The role of compliance departments and senior management in ensuring adherence to ethical and regulatory standards.
The fact that WAMCO agreed to pay $100 million and establish a remediation fund indicates that the firm acknowledged its responsibility in the oversight of Leech’s activities. The settlement with WAMCO, while substantial, also underscores the regulatory pressure on firms to maintain strong compliance frameworks and to actively police the conduct of their employees.
Broader Implications for the Investment Industry
The resolution of the Ken Leech case carries significant implications for the broader investment management industry.
- Increased Regulatory Scrutiny: This case, along with other recent enforcement actions, signals an intensified focus by the SEC and other regulators on trading practices, particularly those involving potential conflicts of interest and breaches of fiduciary duty. Asset managers can expect continued scrutiny of their internal controls and compliance procedures.
- Emphasis on Fiduciary Responsibility: The SEC’s strong language about "egregious breach of fiduciary obligations" serves as a stark reminder to all investment professionals of their fundamental duties to clients. The industry must continually reinforce ethical standards and ensure that client interests are paramount.
- Reputational Risk Management: The reputational damage to both Leech and Western Asset Management highlights the critical importance of robust ethics and compliance programs. Even if a firm is not found to have engaged in wrongdoing, allegations can lead to significant client attrition and public distrust.
- Investor Protection: Ultimately, cases like this serve to protect investors by holding bad actors accountable and by encouraging firms to strengthen their internal controls. The SEC’s commitment to recovering funds for defrauded investors, as seen in the remediation fund established by WAMCO, is a key aspect of its mission.
The $3 million settlement by Ken Leech, while a substantial personal penalty, is part of a larger narrative involving the firm’s significant settlement and his guilty plea in a criminal case. These interconnected legal actions paint a comprehensive picture of alleged misconduct and its consequences. The judicial approval of Leech’s civil settlement will mark the final closure of the SEC’s direct action against him, but the broader implications for Western Asset Management and the investment industry at large will continue to be felt. The case serves as a potent reminder that adherence to ethical principles and robust compliance are not merely regulatory necessities but foundational pillars of trust and integrity in the financial world.
