

The year 2026 has been marked by pronounced volatility across global financial markets, presenting a complex landscape where specific investment strategies have yielded significant rewards while others have incurred substantial losses. This dynamic environment has prompted leading financial experts to re-evaluate portfolio allocations, with a resounding consensus emerging: the imperative to diversify beyond the concentrated winners that have dominated recent market cycles.
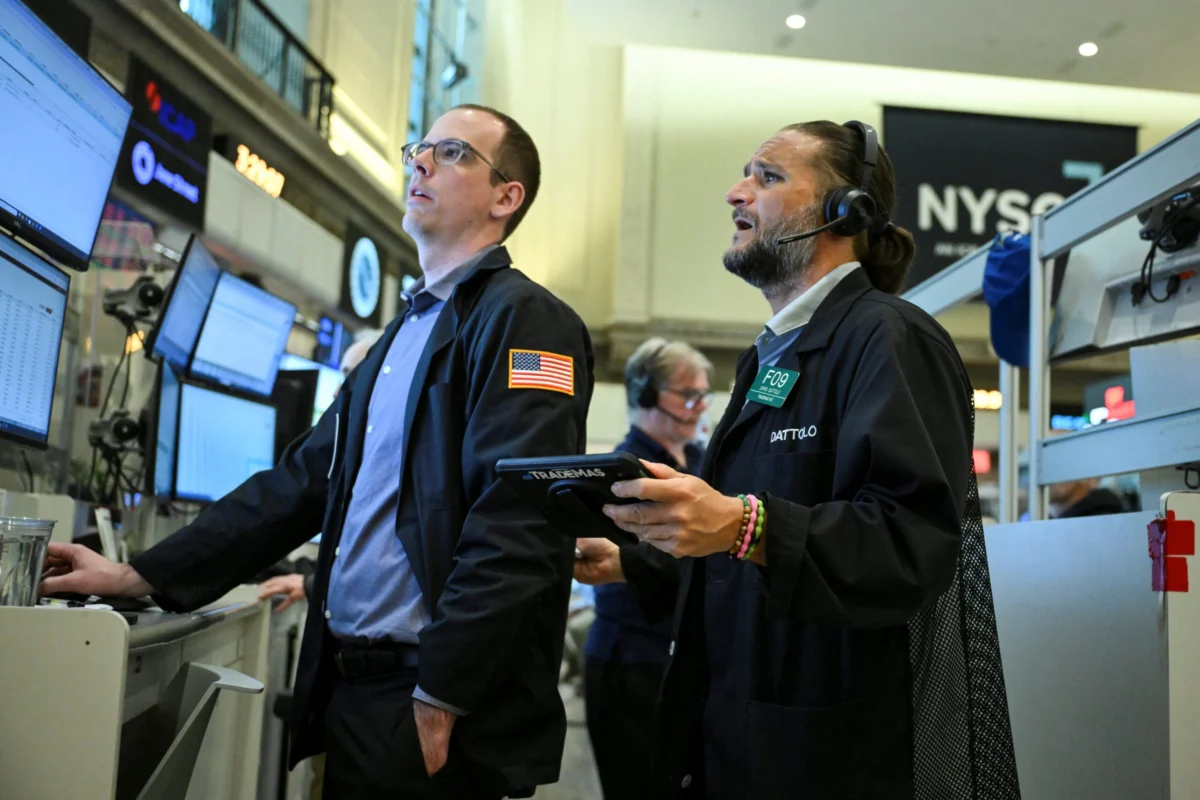
On July 23, 2026, as traders worked diligently on the floor of the New York Stock Exchange (NYSE), the undercurrent of strategic repositioning was palpable. The year’s trading patterns, characterized by rapid shifts in sector leadership and macroeconomic uncertainties, have underscored the fragility of overly concentrated portfolios. CNBC recently engaged six prominent investors to dissect the most pressing risks they foresee and to understand the sophisticated adjustments they are making to their portfolios. Despite varied interpretations of the most formidable threats, a singular, overarching recommendation consistently surfaced: strategically broaden exposures and de-emphasize reliance on the high-flying assets that have garnered significant attention and capital throughout the year.
The Landscape of 2026: A Volatile Chronology
The market’s journey through 2026 has been a turbulent one, building on the foundations of 2025. Following a period of robust U.S. market performance driven largely by a handful of mega-cap technology companies—dubbed the "Magnificent Seven"—the start of 2026 saw continued momentum, particularly in sectors linked to artificial intelligence. However, this bullish sentiment began to face significant headwinds.
By late Q1 and into Q2, escalating geopolitical tensions, particularly the "Iran war" (as referenced by experts), introduced a sharp uptick in energy prices and disruptions to global supply chains. This immediately reignited inflationary concerns, which central banks had been diligently working to tame through a cycle of interest rate hikes in 2024 and 2025. The interplay between persistent inflation, the need for continued monetary tightening, and the potential for economic slowdown created a delicate balancing act for policymakers and a challenging environment for investors.
Mid-year, strong U.S. corporate earnings reports offered a partial reprieve, showcasing resilience in specific sectors. However, this strength was often concentrated, failing to mask underlying fragilities in broader market sentiment. The focus then shifted to the sustainability of the AI boom itself, with debates emerging around the sheer scale of capital expenditure and its long-term financial viability. This chronology of events—from concentrated tech dominance to geopolitical shocks and renewed inflation fears—has shaped the urgent call for diversification.
Fading U.S. Exceptionalism and the Perils of Concentration
A primary concern articulated by investment managers centers on the diminishing advantage of U.S. markets and the inherent dangers of overconcentration. Chris Rush, an investment manager at IBOSS, highlighted to CNBC that a significant risk many investors are inadvertently taking is being "too concentrated in the winners of the past and missing other opportunities around the world." This sentiment directly challenges the prevailing narrative of U.S. market dominance, particularly that driven by a handful of mega-cap technology companies often dubbed the "Magnificent Seven."
Rush elaborated on the perils of short-term focus, noting, "It is easy to focus on the short-term noise. But with U.S. equities already making up such a large proportion of global portfolios, we think concentration is a bigger risk." The historical outperformance of U.S. equities, especially in the years leading up to 2025, led to many global portfolios becoming heavily weighted towards American assets. However, Rush observed that "U.S. exceptionalism has also started to fade from the levels seen before 2025," suggesting a normalization or even a relative decline in the unique advantages that propelled U.S. stocks. This shift can be attributed to several factors, including increasingly competitive global innovation hubs, the maturing growth cycles of some U.S. tech giants, and the cumulative impact of higher interest rates making future growth prospects less appealing in discounted valuations. For instance, regulatory scrutiny on tech monopolies has intensified globally, while advancements in AI and other technologies are now emerging from a broader array of nations, eroding the perception of singular U.S. leadership.

Furthermore, Rush pointed to the "rising debt levels among the Magnificent Seven" as an additional layer of risk. While many of these companies boast impressive cash reserves, they have also leveraged debt significantly for aggressive expansion, strategic acquisitions, or substantial share buyback programs aimed at boosting shareholder value. In an environment of potentially sustained higher interest rates or increased regulatory scrutiny on corporate balance sheets, elevated debt could become a more material concern, impacting their financial flexibility, credit ratings, and future growth trajectories. Chasing these same companies, Rush warned, "add[s] to the risks of continuing to chase the same companies," suggesting diminishing marginal returns and increased vulnerability.
In response to these burgeoning risks, IBOSS is actively broadening its portfolio exposures. Real estate investment trusts (REITs) are one such asset class Rush’s team is favoring. "REITs," he noted, "have been out of favor for years but now look increasingly attractive" from a valuation perspective. After several years of underperformance, largely due to rising interest rates impacting property valuations and borrowing costs, the sector is potentially poised for a rebound. Specific sub-sectors within REITs, such as data centers, logistics, and certain specialized industrial properties, continue to see robust demand, offering attractive yields and diversification benefits. Alongside REITs, IBOSS is increasing allocations to U.K. equities, which have often been undervalued post-Brexit uncertainties, and stocks listed in Asia and emerging markets. The FTSE 100, for example, has historically offered higher dividend yields and a more diversified sector exposure than some of its U.S. counterparts, making it appealing from a valuation standpoint.
Within the Asian markets, Rush specified particular interest. "Investors have understandably been focused on the AI winners in Korea and Taiwan," he acknowledged, referencing the semiconductor and hardware giants driving the artificial intelligence boom. Companies like Samsung and TSMC have seen immense capital inflows due to their critical role in the AI supply chain. However, he also underscored the resilience of China, stating, "China has performed particularly well during the most recent pullback and we think it remains well positioned." This suggests a belief in China’s capacity for recovery and growth, possibly driven by domestic policy support, a rebound in consumer spending, or specific sector-led opportunities, despite ongoing geopolitical tensions and regulatory uncertainties that have previously deterred some foreign investors.
Navigating the Choppy Waters of Specific Volatility: "Don’t Die Trying to Be a Hero"
Beyond broad market concentrations, the very nature of volatility itself has become a critical challenge. Ben Kumar, Head of Strategy for Wealth, Investment and Public Policy at British asset management firm 7IM, emphasized this distinction to CNBC. He explained that the major challenge for investors this year "hasn’t been managing overall volatility, it’s been managing specific volatility." Unlike years where entire market segments moved in unison, 2026 has seen a dizzying rotation of winners and losers, often with little warning.
"The winners and losers have kept chopping and changing," Kumar observed. While the aggregate market performance might appear robust, "overall, the wins have been bigger than the losses… but being too exposed to any one theme, sector or style has been very tricky." He provided concrete examples: energy stocks, often influenced by geopolitical events and supply-demand dynamics, have been both the best and worst performers twice within the year. For instance, an early-year surge in oil prices due to initial regional instability in the Middle East saw energy companies soar, only for a temporary de-escalation to trigger a sharp sell-off, before renewed tensions pushed prices back up. Similarly, the highly dynamic IT sector, encompassing everything from software to hardware and AI, has experienced comparable swings, with sub-sectors rapidly falling in and out of favor. "Everything has worked at some points, nothing has worked at all points," Kumar summarized, painting a vivid picture of a market demanding agility and broad exposure.
For 7IM, the solution has been clear: "Diversification has helped hugely – across sectors and regions." Kumar championed a strategy that prioritizes resilience over chasing short-term, high-risk gains. He noted that investors who maintained a diversified approach, spreading their capital across various industries and geographical locations, were better insulated from the sharp reversals experienced by concentrated portfolios. "And if, like us, you’re prepared not to go all in on winners (and risk being a loser), it’s been a pretty good year." His advice for investors seeking to navigate this environment is pragmatic and cautionary: "You don’t need to be a hero in this market – just let it work for you, and keep your exposures broad." He concluded with a memorable maxim: "Don’t die trying to be a hero," a poignant reminder against excessive risk-taking in pursuit of outsized, but often fleeting, returns.
The Shadow of Geopolitics and the Peril of Complacency
Geopolitical tensions continue to cast a long shadow over market sentiment, a risk highlighted by Ben Seager-Scott, Chief Investment Officer at London-based Forvis Mazars. He identified "two powerful forces" exerting opposing pressures on markets: the ongoing "Iran war" and robust U.S. corporate earnings. The conflict in the Middle East, while presenting acute risks, also runs the danger of market complacency. Seager-Scott warned that markets risked becoming complacent around events in the Middle East, inflationary pressures, and the evolving dynamics of the AI trade.
The "Iran war" reference, likely alluding to an escalation of regional conflicts impacting global oil supplies and shipping lanes, introduces significant uncertainty. Such events can trigger immediate spikes in commodity prices, particularly crude oil, impacting global inflation and corporate input costs across various sectors, from manufacturing to transportation. The Strait of Hormuz, a critical choke point for global oil shipments, has been a particular area of concern, with any disruption immediately sending shockwaves through energy markets. Simultaneously, strong U.S. corporate earnings, driven by resilient consumer demand, technological innovation, and effective cost-cutting measures, provide a bullish counterpoint. This creates a challenging environment for investors, where fundamental strengths are juxtaposed against unpredictable external shocks.

In response, Forvis Mazars has been "finessing" its portfolios. "We have cut back some of our equity risk overweight (whilst remaining marginally overweight) and have rotated more out of the mega-cap technology names into ordinary U.S. stocks, mostly by shifting from market cap weighted exposures to equal weight exposures," Seager-Scott explained. This strategy involves reducing exposure to the largest companies, whose valuations might be stretched and whose future growth may be priced in, and increasing holdings in a broader basket of U.S. companies, where the growth potential might be more evenly distributed. Shifting from "market cap weighted" (where larger companies have a greater impact on an index, e.g., the S&P 500) to "equal weight" (where all companies in an index have the same weight) is a deliberate move to reduce concentration risk and capture broader market performance, potentially favoring mid-cap and value stocks over growth giants.
The persistent threat of inflation, fueled by supply chain disruptions, elevated energy costs from geopolitical events, and strong consumer demand, further complicates the outlook. Combined with the dynamic shifts within the AI sector, where investment trends and profitability models are still evolving rapidly, the market demands constant vigilance and adaptive strategies to avoid being caught off guard by unforeseen developments.
The Central Bank Conundrum: An Uncomfortable Trade-Off
A profound systemic risk, according to Charlie Ambler, Co-Chief Investment Officer and Partner at Saltus, is the policy bind confronting central banks regarding interest rates. Ambler noted that "Central banks are struggling to bring long-term rates under control at precisely the moment the economy is absorbing a massive AI infrastructure buildout, which is capital-hungry and inflationary at the margin." This creates a delicate balancing act for monetary authorities worldwide.
The global push for AI infrastructure – involving massive investments in data centers, advanced semiconductor manufacturing, and significant energy consumption – requires substantial capital. This burgeoning demand, coupled with the potential for increased labor costs for skilled professionals and scarcity of critical resources, contributes to inflationary pressures across the economy. Typically, the "required tonic" for inflation is raising short-term interest rates to cool demand. However, Ambler warns that this action "has become harder to pull." Central banks face an "uncomfortable trade-off" between aggressively controlling inflation through higher rates, which risks stifling economic growth and potentially triggering a recession, and maintaining financial stability, which might necessitate a more cautious approach, potentially allowing inflation to persist above target levels.
In anticipation of central banks potentially not "get[ting] it cleanly right," Saltus’s strategy is to "broaden out." Ambler elaborated, "Rather than concentrating risk in the areas that have driven recent returns, we’re widening our exposures across equities, fixed income and alternatives." A key focus within alternatives is on assets whose returns are not simply correlated with traditional equity and bond markets. This includes strategies like private equity, hedge funds, certain commodities, and infrastructure investments, which can offer diversification benefits and potentially generate returns regardless of broader market movements, acting as a crucial hedge against systemic risks.
Echoing this sentiment, Steve Brice, Global Chief Investment Officer at Standard Chartered, identified the biggest cyclical risk as "something
