

Last year, nearly £60 million worth of art and cultural artifacts transitioned from private ownership into the United Kingdom’s public collections, facilitated by government tax incentive schemes. This figure, representing 32 cases, signifies a substantial 33 per cent increase compared to the previous year and marks the second-highest total recorded since 2015, according to data released by Arts Council England. These figures underscore a growing trend of high-net-worth individuals and their estates leveraging fiscal advantages to preserve national heritage for public enjoyment and scholarly research.
For affluent collectors, the primary mechanisms for achieving this are the Acceptance in Lieu (AIL) scheme and the Cultural Gifts Scheme (CGS). These programs offer a sophisticated method for mitigating tax liabilities, particularly Inheritance Tax (IHT). Instead of liquidating a prized artwork to meet tax obligations, owners can opt to transfer its ownership to the state. This process, however, is not a simple transaction. Each proposed item undergoes rigorous scrutiny by experts to ascertain its cultural, artistic, historical, or scientific significance, ensuring that only items of exceptional merit enter public collections.

Understanding the Tax Incentive Schemes
The Acceptance in Lieu (AIL) scheme, with its origins dating back to 1910, functions primarily as a mechanism to address death duties and inheritance tax. Under AIL, the owner receives a tax credit equivalent to the agreed-upon value of the artwork. A crucial component of this scheme is the "douceur," a French term signifying a "sweetener," which adds an extra incentive valued at 25 per cent of the IHT that would otherwise be payable. This combined value is then factored into the calculation of the tax relief.
In contrast, the Cultural Gifts Scheme (CGS), established in 2013, offers a different pathway for tax relief. CGS provides exemptions against income tax and capital gains tax for qualifying gifts made during an individual’s lifetime. Clarissa Levi, art and heritage counsel at Wedlake Bell, highlights the fundamental distinction: "AIL is essentially a death-and-inheritance-tax mechanism, while CGS was introduced to allow a similar public benefit during the owner’s lifetime." This temporal difference means CGS is designed for individuals who wish to see their cultural contributions benefit the public while they are still alive, whereas AIL is often utilized by estates to settle tax liabilities upon the owner’s passing.
Notable Acquisitions and Geographic Distribution
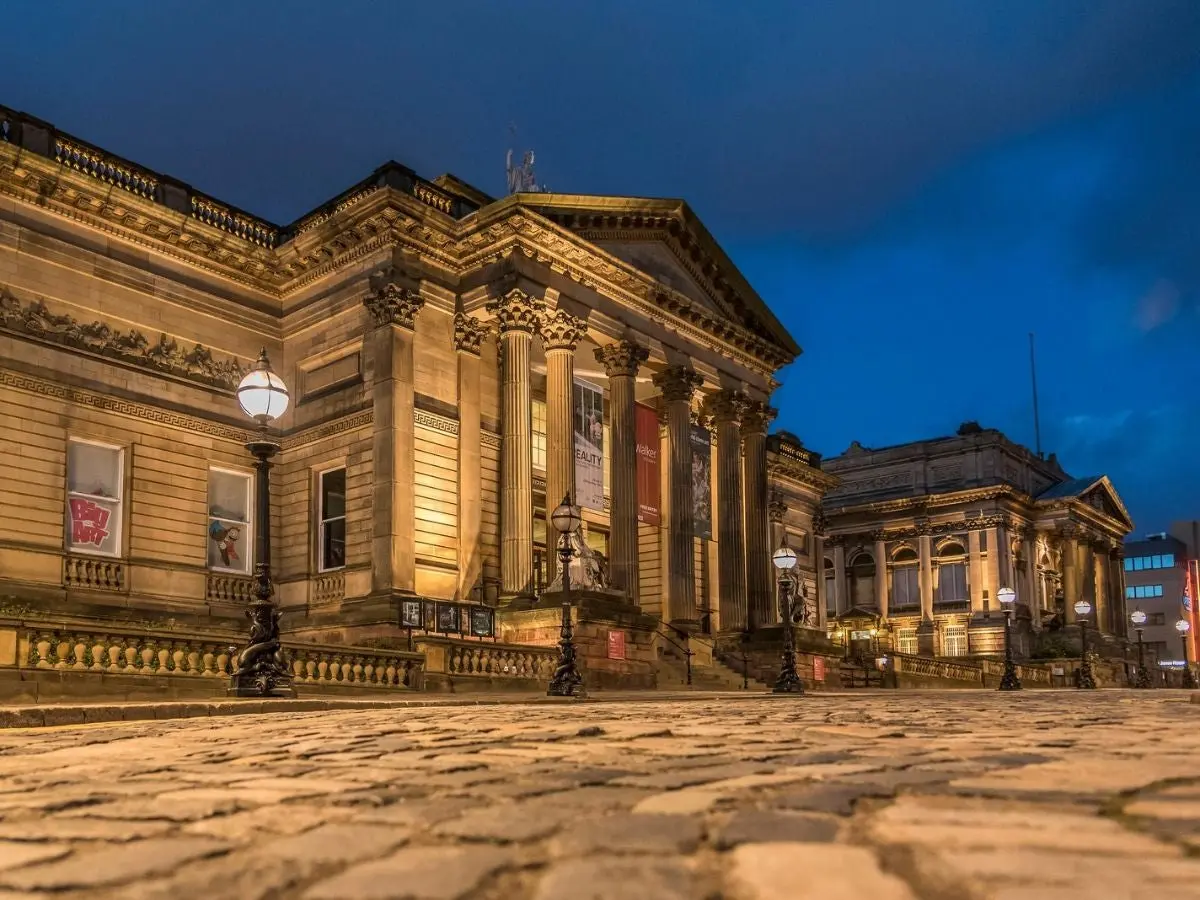
Recent significant acquisitions under the AIL scheme include Claude Monet’s evocative landscape, L’Epte à Giverny, which has found a new home at Liverpool’s Walker Art Gallery. Another notable transfer is Barbara Hepworth’s Orpheus (Maquette 1), now part of the collection at The Hepworth Wakefield. Historically, London’s major museums have been the principal recipients of objects through AIL. However, Levi, who also serves on the government’s Heritage Advisory Board, actively encourages her clients to consider donating to regional museums. Her rationale is compelling: "Gifts to regional institutions can often make a greater impact, allowing smaller museums to significantly enhance their collections and reach." This strategic encouragement aims to foster a more equitable distribution of national heritage across the country, enriching cultural landscapes beyond the capital.

The image accompanying this report showcases Monet’s L’Epte à Giverny at the Walker Art Gallery, illustrating the tangible outcome of the AIL scheme in enriching public access to Impressionist masterpieces. Similarly, Barbara Hepworth’s Orpheus (Maquette 1), a significant sculpture by a pioneering modernist artist, now resides at The Hepworth Wakefield, further solidifying the institution’s focus on British sculpture.
Addressing Perceptions and the True Purpose
While the schemes might superficially appear as tax avoidance strategies for the wealthy, legal and heritage experts emphasize that their primary purpose is far more profound. "The purpose of the AIL scheme is to protect our heritage objects in this country for future generations, and to stop them being sold abroad," states Levi. This perspective frames the schemes not as tax dodges, but as vital tools for national preservation, safeguarding cultural assets from private overseas sale and ensuring their continued accessibility for public benefit and scholarly study.
Shifting Tax Landscape and Future Implications
The total value of art donated to the government could see further increases due to evolving tax legislation. Recent changes to Business Property Relief (BPR), designed to ensure more equitable distribution of wealth, may inadvertently lead to higher Inheritance Tax bills for some affluent families. This shift could make the AIL scheme an even more attractive option for those seeking to manage their tax liabilities while simultaneously contributing to national heritage.

Furthermore, the overhaul of the non-domicile regime, which has traditionally offered tax advantages to individuals residing in the UK but domiciled elsewhere, is expected to bring more international wealth under the purview of UK Inheritance Tax. Under the new residence-based system, some mobile individuals previously outside the scope of UK IHT may find their global assets, including significant art collections held overseas, now subject to the tax. This could potentially create new avenues for AIL applications, though significant complexities remain.
Navigating International Collections and Challenges
However, the prospect of a significant influx of overseas collections into British museums is tempered by several practical considerations. Sunir Watts, a partner at Hunters Law, points out that the stringent artistic significance tests remain a formidable hurdle. Moreover, the schemes have a combined annual limit of £40 million in tax foregone, a cap that could be reached if applications surge. Overseas collections also present a unique set of complications, including navigating export restrictions, potential foreign tax liabilities, and the substantial costs associated with transporting delicate artworks to the UK.
"The impact [of BPR changes] on art collections will largely be indirect," Watts observes. While the non-dom reforms might expose more internationally held collections to UK IHT, he questions whether this will automatically translate into a proportional increase in AIL applications, given the inherent logistical and regulatory challenges.
Strategic Planning for AIL Applications
For families contemplating the AIL scheme, experts universally advise early and thorough planning. Commencing the process well in advance of any imminent IHT liability is crucial. Watts recommends obtaining accurate, up-to-date valuations of potential artworks early in the process. Identifying specific works that are likely to meet the demanding "pre-eminence test" – a benchmark for exceptional cultural or historical importance – is also vital. Equally important is considering potential recipient institutions, ensuring a suitable public collection can appropriately house and display the gifted item.
A common pitfall, Watts cautions, is the assumption that an artwork’s substantial monetary value alone guarantees its eligibility. "A work may be worth a substantial amount and yet not possess the pre-eminence necessary for acceptance," he explains. The pre-eminence test goes beyond market value, focusing on intrinsic artistic, historical, or scientific merit that contributes to the nation’s heritage.
Stewardship and Legacy: The Driving Motivations
Ultimately, the individuals most drawn to the Acceptance in Lieu scheme are often motivated by a profound sense of stewardship rather than purely financial gain. "They regard themselves as custodians of culturally important objects," explains Levi. There is a distinct satisfaction in seeing a family’s long-held art acquisition transition into public ownership. "It makes a bit of a legacy of it because their objects can become part of the national collection," she adds. This sentiment underscores the schemes’ success in aligning private wealth with public good, ensuring that significant cultural treasures are preserved and appreciated by generations to come. The ongoing success of these schemes is a testament to a shared commitment between private collectors and the UK government to safeguard the nation’s rich cultural tapestry.
