

The International Sustainability Standards Board (ISSB) is rapidly advancing its mission to establish a comprehensive global baseline for disclosing sustainability-related risks and opportunities that fundamentally impact corporate financial performance. Since its inception, the board has sought to harmonize a fragmented landscape of non-financial reporting, moving toward a future where environmental, social, and governance (ESG) data is treated with the same rigor and comparability as traditional financial statements. As of mid-2024, nearly 50 jurisdictions—representing a significant portion of the global economy—have signaled their intent to adopt or align with the ISSB’s standards, marking a pivotal shift in the evolution of corporate transparency.
The drive toward a single global standard is a response to the "alphabet soup" of reporting frameworks that has historically plagued the business community. While regional priorities and governmental agendas differ vastly across the globe, the ISSB’s framework is increasingly viewed as the most viable candidate for a universal language of sustainability. This momentum is driven by the release of two core standards: IFRS S1, which covers general requirements for disclosure of sustainability-related financial information, and IFRS S2, which focuses specifically on climate-related disclosures. Together, these standards aim to provide investors with a clear, comparable view of how sustainability factors shape a company’s long-term value.
The Evolution of the ISSB: A Chronology of Harmonization
The journey toward a unified standard began in earnest at the 2021 United Nations Climate Change Conference (COP26) in Glasgow. It was here that the International Financial Reporting Standards (IFRS) Foundation announced the creation of the ISSB. The move was designed to consolidate several existing organizations, including the Climate Disclosure Standards Board (CDSB) and the Value Reporting Foundation (VRF)—which itself was a merger of the International Integrated Reporting Council (IIRC) and the Sustainability Accounting Standards Board (SASB).
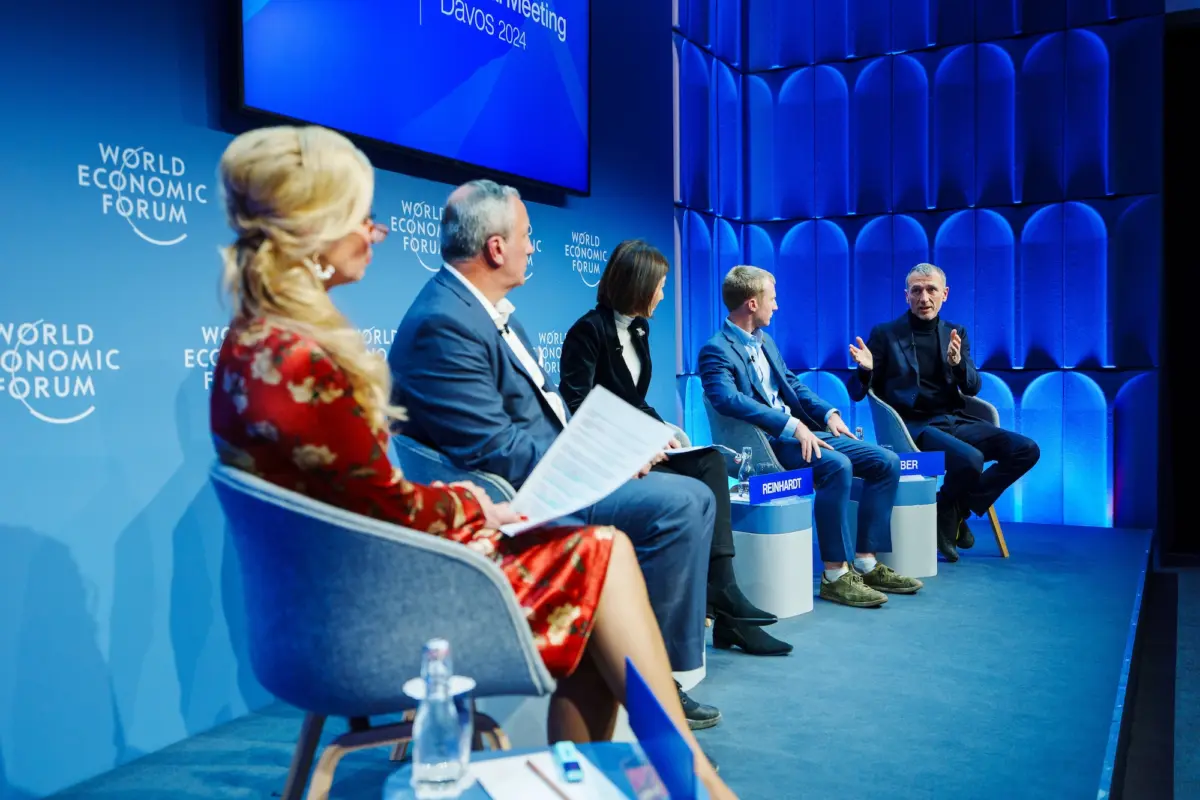
By June 2023, the ISSB officially issued its first two standards, S1 and S2. These were built upon the recommendations of the Task Force on Climate-related Financial Disclosures (TCFD), which had already gained widespread voluntary adoption. In early 2024, during the World Economic Forum Annual Meeting in Davos, ISSB Chair Emmanuel Faber emphasized the board’s commitment to creating a "global passport" for sustainability reporting. This concept envisions a system where a single report, prepared according to ISSB standards, could satisfy the regulatory requirements of multiple jurisdictions, thereby reducing the compliance burden on multinational corporations.
In 2025, the IFRS Foundation expanded its Jurisdictional Working Group to include a broader array of countries, particularly from emerging markets. This expansion was a strategic effort to ensure that the standards remain applicable and implementable in diverse economic contexts. Looking ahead to 2026 and 2027, the board is focusing on deepening the implementation of its climate standards while simultaneously developing new guidance on nature, biodiversity, and human capital.
Adoption Trends and the Strategy of "Neutrality"
The ISSB’s success in gaining international traction can be attributed to its positioning as a neutral, technical body. Unlike the European Union’s Corporate Sustainability Reporting Directive (CSRD), which is often viewed as a politically driven regional mandate, the ISSB operates under the umbrella of the IFRS Foundation—the same entity that oversees the financial reporting standards used in over 140 countries. This institutional heritage provides an immediate layer of credibility with institutional investors and CFOs.
Furthermore, the ISSB has benefited from recent regulatory shifts in major markets. In the United States, the Securities and Exchange Commission (SEC) faced significant legal and political pushback regarding its proposed climate disclosure rules, leading to a perceived roll-back in ambition. In Europe, while the CSRD remains the most comprehensive regulation, its complexity has led to confusion among businesses. Amidst this volatility, the ISSB standards have emerged as a practical, middle-ground framework that avoids specific national or regional political baggage.
For many nations in the Middle East, Africa, and Southeast Asia, adopting the ISSB framework is a strategic move to elevate local reporting requirements to international levels rapidly. This "adoption by stealth" allows countries to attract foreign investment by providing the high-quality, comparable data that global asset managers demand, without having to develop their own complex regulatory structures from scratch.
Regional Variations: A Fragmented Implementation Landscape
While the goal is a global baseline, the reality of implementation remains nuanced. Although approximately 50 countries are on the path to adoption, they are not all following the same blueprint. The ISSB allows for "transition relief," giving companies time to build the necessary data infrastructure. For instance, the core framework suggests that companies report their direct (Scope 1) and indirect (Scope 2) emissions in the first year, with value chain (Scope 3) emissions following in the second year.

Several countries, including Chile, Malaysia, Nigeria, and Singapore, have moved to transpose the ISSB standards directly into their local laws without modification. However, other major economies have introduced significant variations:
- The United Kingdom: The UK has endorsed the ISSB standards for voluntary use but has adjusted the transition timelines. The Financial Conduct Authority (FCA) confirmed that the framework would eventually replace existing rules on a "comply or explain" basis, with mandatory Scope 1 and 2 reporting for listed companies starting in 2028.
- Australia: While mirroring the core ISSB framework, Australian regulators have removed references to industry-specific climate metrics, focusing instead on a more generalized approach to climate risk.
- Brazil: One of the earliest adopters, Brazil originally planned for mandatory reporting by 2026 but recently shifted to a "comply or explain" model, though it still expects independent assurance for those who do report.
- China: Perhaps the most significant deviation comes from China. While aligning with the ISSB’s technical structure, Chinese regulators have favored "double materiality" over the ISSB’s "financial materiality."
The Materiality Debate: Financial vs. Double Materiality
The distinction between financial materiality and double materiality remains a central point of contention in the global reporting landscape. The ISSB focuses on financial materiality—how sustainability issues affect a company’s cash flows, access to finance, and overall value. This approach is designed specifically to meet the needs of investors.
In contrast, double materiality (the cornerstone of the EU’s CSRD and China’s emerging framework) requires companies to report not only on how sustainability affects them but also on how their operations impact the environment and society. Critics of the ISSB’s narrower focus argue that it ignores the long-term systemic risks created by corporate activities. However, proponents of the ISSB approach suggest that over time, impacts on the planet eventually become financial risks. Climate change is the primary example: what began as an environmental impact has now evolved into a direct financial threat to assets and supply chains.
The EU recently explored a proposal for stronger alignment between the CSRD and the ISSB to allow companies to integrate disclosures into a single report. However, this was met with resistance from French banking and business federations, who feared that such alignment might lead to a two-tier system where investor-focused financial data would overshadow broader impact reporting. Consequently, for the time being, companies operating in both the EU and ISSB-adopting jurisdictions may still face overlapping requirements.
Supporting Data: Economic Reach and Corporate Readiness
The economic weight behind the ISSB is substantial. According to data released by the IFRS Foundation, the jurisdictions currently adopting or moving toward ISSB alignment represent approximately 60 percent of global GDP. This includes a significant portion of the G20, which has repeatedly voiced support for the board’s work in its communiqués.
From a corporate perspective, the demand for standardized data is high. A 2024 survey of institutional investors revealed that 82 percent believe that the current lack of comparable sustainability data is a significant barrier to effective capital allocation. Furthermore, the inclusion of the SASB standards under the ISSB umbrella provides a practical toolkit for businesses. The SASB standards cover 77 industries, offering specific metrics that are already familiar to many sustainability professionals.
However, the "readiness gap" remains a concern. While large multinational corporations often have the resources to track Scope 3 emissions and conduct climate scenario analysis, small and medium-sized enterprises (SMEs) within their supply chains often do not. This is why the ISSB’s transition relief and the "comply or explain" models adopted by various countries are seen as essential for a successful global rollout.
Future Outlook: Biodiversity and Beyond
The ISSB is not stopping at climate. The board is currently working on a practice statement for biodiversity, ecosystems, and ecosystem services. This work is being closely modeled on the Taskforce for Nature-related Financial Disclosures (TNFD) framework, which has gained significant traction in the last year. A draft of this nature-related guidance is expected to be a major focus of the board’s work through late 2024 and 2025.
Additionally, the ISSB is tasked with updating the SASB standards to ensure they remain relevant in a rapidly changing economic environment. This includes refining industry-specific metrics to account for technological shifts and new scientific understandings of environmental risks.
As the ISSB moves toward its 2027 goal of widespread adoption, the primary challenge will be maintaining the integrity of the "global baseline" while allowing for necessary local variations. If successful, the ISSB standards will provide the foundation for a new era of corporate accountability, where a company’s environmental and social footprint is as transparent and scrutinized as its balance sheet. For global businesses, the message is clear: the era of fragmented, voluntary reporting is ending, and the era of standardized, mandatory disclosure is here.
