

The pursuit of a harmonized global framework for corporate sustainability reporting has reached a critical juncture as the International Sustainability Standards Board (ISSB) gains unprecedented momentum across major economies. Led by Chair Emmanuel Faber, the ISSB is successfully positioning its standards as the "global baseline" for disclosing sustainability-related risks and opportunities, aiming to provide investors with a clear, comparable, and decision-useful view of how environmental and social factors impact a company’s financial health. As of late 2024, nearly 50 jurisdictions—representing approximately 60 percent of global gross domestic product (GDP)—have taken concrete steps toward adopting or aligning with the ISSB’s inaugural standards, IFRS S1 and IFRS S2. This shift marks a departure from the "alphabet soup" of voluntary reporting frameworks that once dominated the landscape, moving toward a regulated era of transparency that treats non-financial data with the same rigor as traditional financial accounting.
The Genesis of a Global Baseline: From COP26 to Davos
The ISSB was established in November 2021 during the UN Climate Change Conference (COP26) in Glasgow. Its creation was a direct response to urgent calls from the G20, the Financial Stability Board, and the international investment community for a unified set of standards. Prior to its formation, companies were often overwhelmed by competing reporting requests from various frameworks, including the Global Reporting Initiative (GRI), the Sustainability Accounting Standards Board (SASB), and the Task Force on Climate-related Financial Disclosures (TCFD).
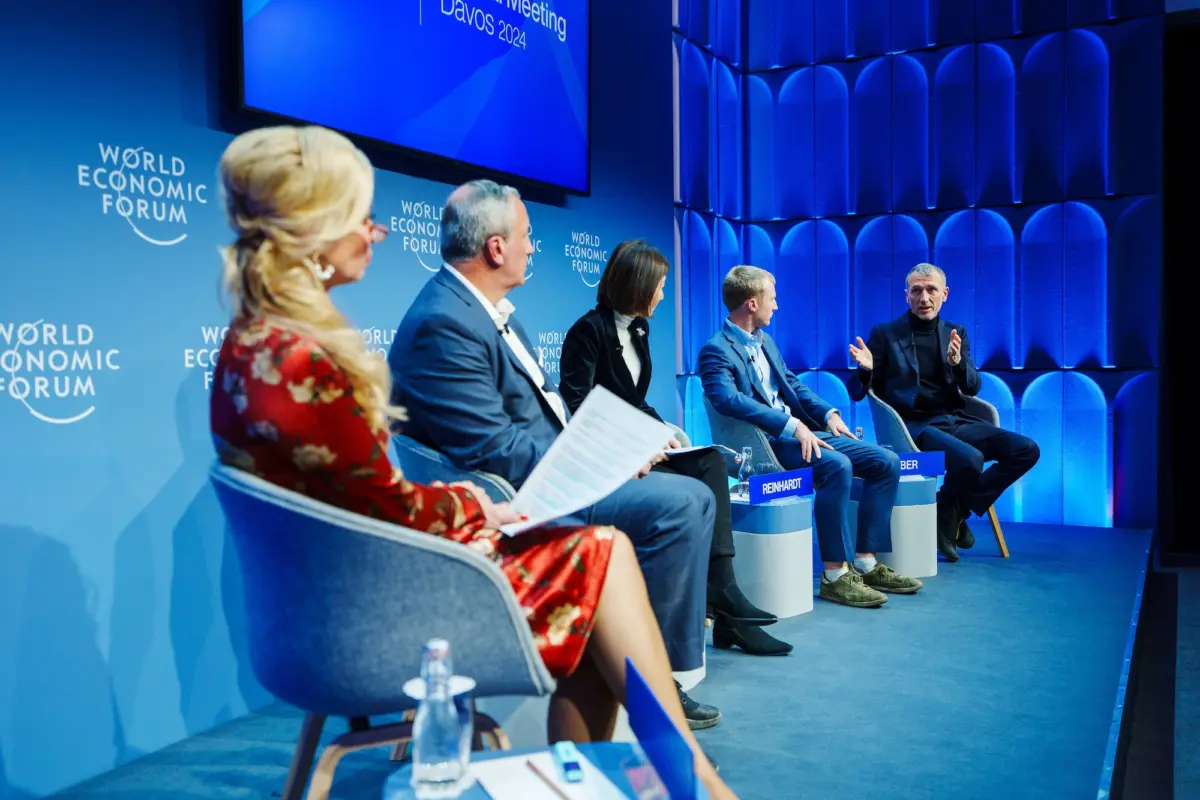
By operating under the umbrella of the International Financial Reporting Standards (IFRS) Foundation—the same body that oversees the accounting rules used in over 140 countries—the ISSB launched with immediate institutional credibility. In June 2023, the board released its first two standards: IFRS S1, which covers general requirements for disclosure of sustainability-related financial information, and IFRS S2, which focuses specifically on climate-related disclosures. At the 2024 World Economic Forum in Davos, Emmanuel Faber emphasized that these standards are not merely about environmental protection, but about the "language of capital," ensuring that sustainability risks are integrated into the core of corporate valuation and risk management.
A Chronology of Implementation and Global Momentum
The timeline of the ISSB’s development reflects a rapid acceleration from conceptualization to regulatory integration. Following the release of the standards in mid-2023, the International Organization of Securities Commissions (IOSCO) endorsed them in July 2023, calling on its members—who regulate more than 95 percent of the world’s financial markets—to incorporate the standards into their respective regulatory frameworks.
Throughout 2024, the "adoption wave" moved from theory to practice. In January, the standards became officially effective for use, and by the second quarter, countries such as Singapore, Australia, and Nigeria had announced specific roadmaps for mandatory implementation. In May 2024, during the Beijing International Sustainability Conference, the ISSB confirmed that jurisdictions representing over half of the world’s economy were actively moving toward the framework. By 2025, the foundation expects the number of adopting countries to exceed 50, with many looking toward 2026 or 2027 as the first mandatory reporting years for large public interest entities.
The Strategy of Neutrality and Stealth Adoption
The success of the ISSB is largely attributed to its perceived political neutrality. Unlike the European Union’s Corporate Sustainability Reporting Directive (CSRD), which is often seen as highly prescriptive and rooted in European social values, the ISSB standards are framed as purely technical and investor-focused. This distinction has allowed the ISSB to bypass the "ESG backlash" seen in parts of the United States, where sustainability reporting has become a polarized political issue.
For many emerging markets, particularly in Africa and the Middle East, adopting the ISSB framework is a strategic move to attract foreign direct investment. By aligning local reporting requirements with an international standard, these countries signal to global investors that their corporate data is reliable and comparable to that of companies in developed markets. Nigeria, for instance, was one of the first to commit to the standards, viewing them as a tool to improve the transparency and competitiveness of its capital markets.
Divergent Paths: The Challenge of Uniformity
While the ISSB aims for a universal baseline, the reality of global adoption is characterized by significant local variations. Regulators in different jurisdictions are "cherry-picking" or modifying elements of the standards to suit local economic conditions, a trend that threatens to dilute the goal of total comparability.
The United Kingdom’s Pragmatic Approach
The U.K. has been a vocal supporter of the ISSB, yet it has tailored the framework to fit its existing regulatory landscape. The Financial Conduct Authority (FCA) intends to replace existing climate reporting rules with the ISSB standards on a "comply or explain" basis. Notably, the U.K. opted to strip out certain "transition reliefs" provided by the ISSB, pushing for earlier disclosure of value chain emissions (Scope 3) than the baseline might otherwise require for voluntary adopters.

China and the Materiality Debate
Perhaps the most significant deviation comes from China. While the Chinese Ministry of Finance has expressed support for a unified global standard, it has signaled a preference for "double materiality." This concept, also used in the EU, requires companies to report not just on how sustainability issues affect their financial performance (financial materiality), but also on how the company’s operations impact the environment and society (impact materiality). The ISSB’s core focus remains strictly on financial materiality, creating a potential rift in how data is reported and interpreted between East and West.
Regional Variations in Asia and the Americas
Other nations have adjusted the implementation clock. Australia’s standards mirror the ISSB but have removed certain industry-specific metrics, focusing initially on high-level climate disclosures. In Latin America, Brazil initially planned for mandatory reporting by 2026 but later shifted to a "comply or explain" model, though it still emphasizes the need for independent assurance—a step not strictly mandated by the core ISSB framework but encouraged for credibility.
Data and the "Scope 3" Hurdle
One of the most contentious aspects of the ISSB standards is the requirement to report Scope 3 emissions—the indirect greenhouse gas emissions that occur in a company’s value chain. For many industries, Scope 3 accounts for more than 70 percent of their total carbon footprint, yet it is notoriously difficult to measure accurately.
To address this, the ISSB included a one-year "transition relief" for Scope 3 disclosures, allowing companies to focus on Scope 1 (direct) and Scope 2 (indirect energy) emissions in their first year of reporting. Supporting data from the IFRS Foundation suggests that this relief was essential for gaining the support of smaller companies and those in jurisdictions with less developed data infrastructure. However, as the relief periods expire, the pressure on global supply chains to provide accurate climate data will intensify, likely leading to a surge in demand for sustainability consulting and digital reporting tools.
Official Responses and Stakeholder Reactions
The reaction from the corporate world has been a mix of relief and apprehension. Major institutional investors, such as BlackRock and State Street Global Advisors, have largely welcomed the ISSB standards, noting that fragmented data has long been a barrier to effective risk assessment. In official statements, investor groups have emphasized that "comparability is the currency of the capital markets," and the ISSB provides the best hope for achieving it.
Conversely, some business advocacy groups, particularly the Mouvement des Entreprises de France (MEDEF), have expressed concern about the potential for a "two-tier" reporting system. They argue that if the ISSB standards become the primary focus for investors, the broader "impact" disclosures required by the EU’s CSRD might be sidelined, leading to a focus on short-term financial risks at the expense of long-term environmental health.
Broad Impact and Future Implications
The long-term impact of the ISSB extends beyond simple compliance. It is driving a fundamental shift in corporate governance. As sustainability disclosures move into annual financial filings, they fall under the purview of Chief Financial Officers (CFOs) and audit committees, rather than just sustainability departments. This "financialization" of ESG data means that companies must implement internal controls and data verification processes as robust as those used for revenue and profit reporting.
Looking ahead, the ISSB is not resting on its climate-first laurels. The board is currently developing a practice statement for biodiversity and ecosystem services, leveraging the work of the Taskforce for Nature-related Financial Disclosures (TNFD). A draft of this guidance is expected to be a major focus of the 2025 reporting cycle. Furthermore, the ISSB is working on a "global passport" initiative to help harmonize the various national versions of its standards, aiming to reduce the reporting burden for multinationals that currently face a patchwork of requirements.
Ultimately, the ISSB’s journey from a COP26 announcement to a global regulatory pillar represents one of the fastest shifts in the history of financial regulation. While the "baseline" is currently being tested by national interests and differing definitions of materiality, the momentum toward a single, investor-focused language for sustainability appears irreversible. For global businesses, the message is clear: the era of voluntary, high-level sustainability narratives is ending, replaced by a rigorous, data-driven framework that will define corporate value in the 21st century.
