

The International Sustainability Standards Board (ISSB) is rapidly approaching a critical inflection point in its mission to establish a comprehensive global baseline for sustainability-related financial disclosures. Led by Chair Emmanuel Faber, the board has transitioned from a conceptual initiative born at the COP26 climate summit to a functional regulatory architect, with nearly 50 jurisdictions now signaling their intent to adopt or align with its standards. This movement represents a fundamental shift in how the global capital markets value environmental, social, and governance (ESG) factors, moving them from the periphery of "corporate social responsibility" into the core of financial reporting and risk management.
As of late 2024, the ISSB’s framework—specifically the IFRS S1 (General Requirements for Disclosure of Sustainability-related Financial Information) and IFRS S2 (Climate-related Disclosures)—is being integrated into the national regulatory fabrics of economies representing approximately 60 percent of global Gross Domestic Product (GDP). The momentum behind these standards reflects a growing consensus among investors, who have long complained about the "alphabet soup" of fragmented reporting frameworks that made it nearly impossible to compare the sustainability performance of companies across different borders and sectors.
The Genesis and Evolution of a Global Baseline
The journey toward a unified standard began in earnest in November 2021 at the United Nations Climate Change Conference (COP26) in Glasgow. The IFRS Foundation, which oversees the accounting standards used in over 140 jurisdictions, announced the creation of the ISSB to meet the urgent demand for high-quality, transparent, and comparable sustainability data.
The strategy was one of consolidation rather than invention. By absorbing the Climate Disclosure Standards Board (CDSB) and the Value Reporting Foundation—which housed the Integrated Reporting Framework and the Sustainability Accounting Standards Board (SASB) standards—the ISSB inherited a wealth of technical expertise and market buy-in. This allowed the board to release its inaugural standards, IFRS S1 and S2, in June 2023.
These standards are designed to ensure that companies provide information about their sustainability-related risks and opportunities alongside their financial statements. The objective is clear: to provide investors with a holistic view of a company’s ability to generate value over the short, medium, and long term, accounting for the physical and transitional risks posed by a changing climate and shifting social expectations.
A Chronology of Global Adoption and Implementation
Since the formal publication of the standards in mid-2023, the timeline of adoption has been remarkably swift for a global regulatory framework.
In late 2023 and throughout 2024, several "first-mover" nations began the legislative process to mandate ISSB-aligned reporting. Brazil and Turkey were among the first to announce mandatory requirements, followed by Singapore and Hong Kong, which recognized the importance of these standards in maintaining their status as premier global financial hubs.
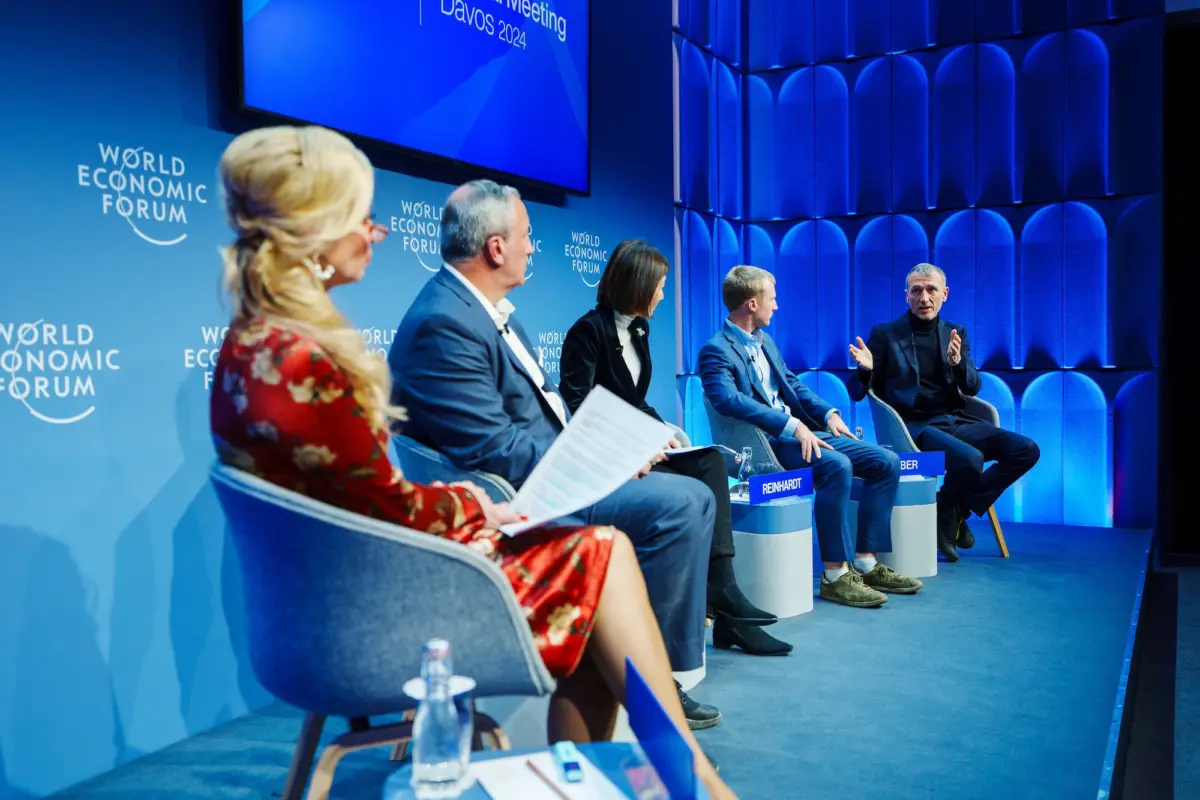
In early 2024, at the World Economic Forum in Davos, Emmanuel Faber emphasized that the "interoperability" of these standards would be the key to their success. By mid-2024, the United Kingdom, Australia, and Canada had all moved forward with national consultation processes to integrate IFRS S1 and S2 into their domestic frameworks, albeit with specific local adjustments.
Looking ahead to 2025 and 2026, the first wave of mandatory reporting is expected to take effect for large listed entities in several jurisdictions. By 2027, the ISSB anticipates that over 50 countries will have fully integrated the standards, creating a "global passport" for corporate sustainability data that can be used by investors in any market.
The Strategy of Adoption by Stealth and Technical Neutrality
One of the primary reasons for the ISSB’s rapid ascent is its perceived independence and technical focus. Unlike the European Union’s Corporate Sustainability Reporting Directive (CSRD), which is often seen as a politically driven instrument of EU policy, the ISSB is viewed as a neutral, market-led body. This has allowed national governments to endorse the framework without appearing to succumb to foreign political agendas.
The ISSB standards act as a "floor," not a "ceiling." This allows countries in the Middle East, Africa, and Southeast Asia to rapidly elevate their local reporting requirements to an international standard, thereby attracting foreign direct investment from institutional players who require standardized ESG data to meet their own fiduciary duties.
Furthermore, by building on the Task Force on Climate-related Financial Disclosures (TCFD) recommendations, the ISSB provided a familiar starting point. Because many large corporations had already spent years aligning with the TCFD, the transition to IFRS S2 felt like an evolution rather than a disruption.

Navigating the Challenges of Regional Variations
While the goal is a unified global baseline, the reality on the ground is a patchwork of "comply or explain" models and localized modifications. The "catch" in the current adoption phase is the lack of total uniformity, which still leaves multinational corporations (MNCs) navigating slight differences in requirements.
In the United Kingdom, the Financial Conduct Authority (FCA) has indicated that the ISSB standards will eventually replace existing rules for listed companies, but with a specific focus on "comply or explain" for certain sustainability-related disclosures. Meanwhile, Australia has taken a more targeted approach, stripping out some industry-specific metrics to focus more heavily on climate-related financial risks in the immediate term.
Developing nations have also sought "transition relief." The ISSB framework inherently allows for a phased approach, such as permitting companies to report on Scope 1 and Scope 2 emissions in the first year before requiring the more complex Scope 3 (value chain) emissions reporting in the second year. Nigeria and Malaysia, for example, are leveraging these transition periods to allow their domestic industries time to build the necessary data collection infrastructure.
The Materiality Debate: Financial vs. Double Materiality
A significant point of divergence remains the definition of "materiality." The ISSB focuses on "financial materiality"—how sustainability issues affect the company’s financial health and value. In contrast, the European Union’s CSRD utilizes "double materiality," which requires companies to report not only on how sustainability affects them but also on how their operations affect the environment and society.
China has emerged as a fascinating test case in this debate. Despite the ISSB’s focus on financial materiality, China’s recently proposed reporting guidelines for its largest listed companies lean toward a double materiality perspective. This suggests that the ISSB standards may serve as a core component of a broader reporting regime that includes wider social and environmental impacts, depending on national priorities.
The debate over materiality is more than just academic; it has practical implications for what data is collected and how it is audited. The ISSB is currently working with the European Commission and EFRAG (the European Financial Reporting Advisory Group) to ensure that companies reporting under CSRD can also meet ISSB requirements without duplicative effort. However, the rejection of a recent proposal for closer alignment in early 2024 highlights the ongoing tension between investor-focused data and stakeholder-focused transparency.
Implications for the Business Community and Investors
For global multinationals, the rise of the ISSB is a double-edged sword. On one hand, it promises to streamline the reporting process by replacing multiple voluntary frameworks with a single, globally recognized standard. On the other hand, the shift from voluntary to mandatory reporting increases the legal and financial stakes.
Companies are now being advised to treat sustainability data with the same rigor as financial data. This involves:
- Gap Analysis: Evaluating current disclosures against IFRS S1 and S2 to identify missing data points, particularly in the supply chain (Scope 3).
- Internal Controls: Establishing robust internal systems to ensure the accuracy and auditability of non-financial metrics.
- Assurance: Preparing for third-party assurance requirements, which are already being mandated in jurisdictions like Mexico and Brazil.
Investors stand to benefit the most from this transition. With standardized data, asset managers can more accurately price climate risk into their portfolios and identify companies that are genuinely positioned to thrive in a low-carbon economy, rather than those merely engaging in "greenwashing."
Future Horizons: Biodiversity and the Expansion of SASB
The ISSB is not stopping at climate and general sustainability. The board is currently expanding its remit to include nature-related disclosures, acknowledging that biodiversity loss and ecosystem collapse pose systemic risks to the global economy. A practice statement on biodiversity and ecosystems is currently in development, heavily influenced by the Taskforce on Nature-related Financial Disclosures (TNFD).
Additionally, the ISSB is in the process of updating the SASB standards, which provide industry-specific guidance for over 70 sectors. These updates are intended to ensure that the standards remain relevant in a rapidly changing technological and regulatory landscape.
As the ISSB continues to expand its "Jurisdictional Working Group" and refine its "global passport" initiative, the path forward is clear. While regional nuances will persist, the era of fragmented, voluntary sustainability reporting is drawing to a close. For the corporate world, the message from Davos 2024 and beyond is unambiguous: sustainability is no longer an optional narrative—it is a financial fundamental.
