

The International Sustainability Standards Board (ISSB) is rapidly advancing toward its primary objective of establishing a comprehensive global baseline for disclosing sustainability-related risks and opportunities. As corporations face increasing pressure from investors, regulators, and the public to provide transparent data regarding their environmental and social impacts, the ISSB’s framework has emerged as the leading candidate for a unified reporting language. By focusing on how sustainability issues impact a company’s financial health, the board seeks to provide the capital markets with the same level of rigor and comparability found in traditional financial accounting.
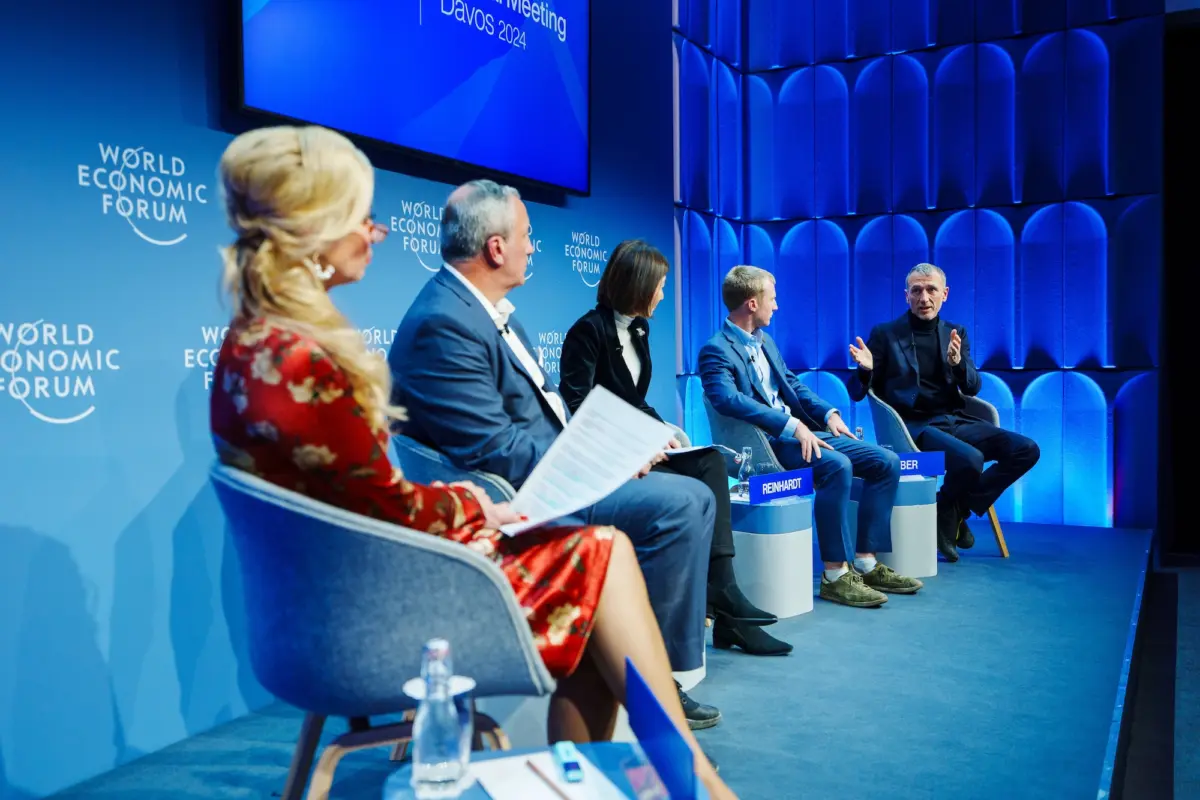
The momentum behind this movement was palpable during the 2024 World Economic Forum in Davos, where ISSB Chair Emmanuel Faber emphasized that the era of fragmented, voluntary ESG reporting is drawing to a close. With nearly 50 jurisdictions—representing approximately 60 percent of global Gross Domestic Product (GDP)—now taking steps to adopt or align with ISSB standards, the financial world is witnessing a historic shift in how corporate value is measured and reported.
The Genesis of a Global Baseline: From COP26 to Present
The path to a unified standard began in earnest at the 2021 United Nations Climate Change Conference (COP26) in Glasgow. It was here that the International Financial Reporting Standards (IFRS) Foundation announced the creation of the ISSB. The foundation, which already oversees the accounting standards used in over 140 countries, recognized that the "alphabet soup" of existing voluntary frameworks—such as the Sustainability Accounting Standards Board (SASB), the Task Force on Climate-related Financial Disclosures (TCFD), and the Climate Disclosure Standards Board (CDSB)—was creating confusion and allowing for "greenwashing."
By June 2023, the ISSB officially released its first two standards: IFRS S1 and IFRS S2. IFRS S1 sets out general requirements for disclosing sustainability-related financial information, ensuring that companies report on all significant risks and opportunities that could reasonably be expected to affect their cash flows or access to finance. IFRS S2 is more specific, focusing on climate-related disclosures, including greenhouse gas emissions and physical climate risks.
The logic behind these standards is rooted in "financial materiality." Unlike some frameworks that focus solely on a company’s impact on the planet, the ISSB standards are designed to tell investors how the planet’s changing climate and social landscape will impact the company’s bottom line. This investor-centric approach has been the catalyst for the board’s rapid acceptance across diverse political and economic regions.
Adoption by Stealth: The Strategy of Neutrality
One of the most striking aspects of the ISSB’s rise is what experts call "adoption by stealth." Unlike the European Union’s Corporate Sustainability Reporting Directive (CSRD), which is often viewed as a politically driven regulatory overhaul, the ISSB standards are perceived as neutral, technical benchmarks. Because the ISSB operates under the IFRS Foundation, it carries the inherent credibility of a professional accounting body rather than a government agency.
This perceived neutrality has allowed national governments to endorse the framework without appearing to succumb to foreign political agendas. For many emerging economies in the Middle East, Africa, and Southeast Asia, adopting the ISSB framework is a strategic move to attract international capital. By aligning local reporting requirements with global standards, these nations can signal to global investors that their markets are transparent, stable, and prepared for the transition to a low-carbon economy.
Furthermore, the ISSB has successfully consolidated the legacy of previous frameworks. By absorbing the SASB and TCFD, the ISSB ensured that companies already using those tools would find the transition to IFRS S1 and S2 relatively seamless. This "evolutionary" rather than "revolutionary" approach has lowered the barrier to entry for many multinational corporations.
A Fragmented Reality: Variations in Global Implementation
Despite the widespread endorsement of the ISSB, the dream of a perfectly uniform global standard remains elusive. As different countries move to transpose these standards into national law, many are introducing local variations, adjustments to timelines, and specific carve-outs.
The United Kingdom and the "Comply or Explain" Model
The U.K. has been a vocal supporter of the ISSB, yet its implementation strategy reflects a measured approach. The Financial Conduct Authority (FCA) has indicated that the ISSB framework will eventually replace existing TCFD-aligned rules for listed companies. However, the U.K. has stripped out some of the "transition relief" provided in the original ISSB text. Under current plans, listed companies in Britain will be required to report direct emissions (Scope 1 and 2) starting in 2028, with value chain emissions (Scope 3) following in 2029.
The Multi-Tiered Approach in Asia and Latin America
Nations such as Chile, Malaysia, Nigeria, and Singapore have opted to adopt the standards largely unchanged, seeking maximum alignment with international norms. In contrast, Australia has taken a more selective approach. While its proposed standards mirror the ISSB framework, Australian regulators have removed certain industry-specific climate metrics to better suit the domestic economic landscape.

In Mexico, the standards are being adopted without alteration, but with an added layer of complexity: mandatory external assurance. While the core ISSB framework does not strictly require third-party auditing, Mexican regulators are insisting on it to ensure data reliability. Brazil, an early adopter, initially planned for mandatory reporting by 2026 but has since shifted to a "comply or explain" basis, reflecting the difficulties companies face in gathering high-quality data.
China’s Departure: The Double Materiality Test
Perhaps the most significant deviation comes from China. While the Chinese Ministry of Finance has expressed support for a global baseline, its domestic proposal favors "double materiality." This concept requires companies to report not only on how sustainability issues affect their financial performance but also on how their operations impact society and the environment. This aligns more closely with the European Union’s philosophy than with the ISSB’s strictly financial focus, creating a potential divergence in how Chinese firms are evaluated by global versus domestic investors.
The Materiality Debate: Impact vs. Risk
The divergence between "financial materiality" and "double materiality" remains the central tension in the world of sustainability reporting. The ISSB’s focus on financial materiality is intended to serve the needs of the "primary users of general-purpose financial reports"—namely, investors and lenders. The goal is to provide a clear picture of how ESG factors influence a company’s enterprise value.
However, critics and some regulators argue that this focus is too narrow. The European Union’s CSRD is built on the premise that a company’s impact on the world is inherently linked to its long-term financial survival. For instance, a company that depletes local water sources may not face an immediate financial risk, but the eventual regulatory backlash or loss of "social license to operate" represents a massive latent risk.
In April 2026, a proposal to harmonize the EU’s CSRD with the ISSB framework was floated to allow companies to use a single report for both. However, the proposal was ultimately dropped after business groups expressed concerns that a "two-tier" system would emerge, where investors would ignore the "impact" data in favor of the "financial" data. This debate underscores a fundamental challenge: while the world wants a single standard, there is still no global consensus on what information is truly "material."
Future Horizons: Biodiversity and the "Global Passport"
The ISSB is not resting on its laurels. Behind the scenes, the board is working on an initiative dubbed the "global passport." This project aims to iron out the jurisdictional variations currently plaguing the rollout. By working with the Jurisdictional Working Group—which was expanded in 2025 to include more countries—the ISSB hopes to create a mechanism where a report prepared according to ISSB standards is accepted in any jurisdiction, regardless of minor local tweaks.
Additionally, the scope of reporting is expanding beyond climate. The ISSB is currently developing a practice statement for biodiversity, ecosystems, and ecosystem services. This work is being closely modeled on the Taskforce for Nature-related Financial Disclosures (TNFD) framework. With the first draft expected shortly, companies will soon be expected to provide the same level of transparency regarding their "nature footprint" as they currently do for their carbon footprint.
Furthermore, the ISSB is in the process of updating the SASB standards, which provide industry-specific guidance for over 70 sectors. These updates are intended to ensure that the metrics remain relevant in a rapidly changing technological and economic environment.
Strategic Implications for Global Business
For multinational corporations, the rise of the ISSB offers both a challenge and an opportunity. On one hand, the consolidation of standards reduces the administrative burden of reporting to multiple different frameworks. On the other hand, the move toward mandatory, audited disclosures means that "sustainability" can no longer be a function of the marketing department; it must be integrated into the core financial and accounting operations of the firm.
Experts suggest that companies should take three immediate steps to prepare:
- Gap Analysis: Map current ESG disclosures against the IFRS S1 and S2 requirements to identify where data collection systems are lacking.
- Scope 3 Readiness: Even in jurisdictions where value chain reporting is delayed, companies should begin engaging with suppliers. Scope 3 emissions often account for over 70 percent of a company’s total carbon footprint, and gathering this data is a multi-year process.
- Internal Governance: Ensure that the board of directors and the CFO’s office are fully literate in ISSB requirements. As these disclosures become part of annual filings, the legal and financial liability associated with them increases significantly.
While the "global baseline" is still under construction, the direction of travel is clear. The ISSB has successfully moved sustainability reporting from the periphery of corporate social responsibility to the center of global finance. As more countries join the 50 jurisdictions already on the path to adoption, the ISSB standards are set to become the definitive "global passport" for corporate transparency in the 21st century.
