

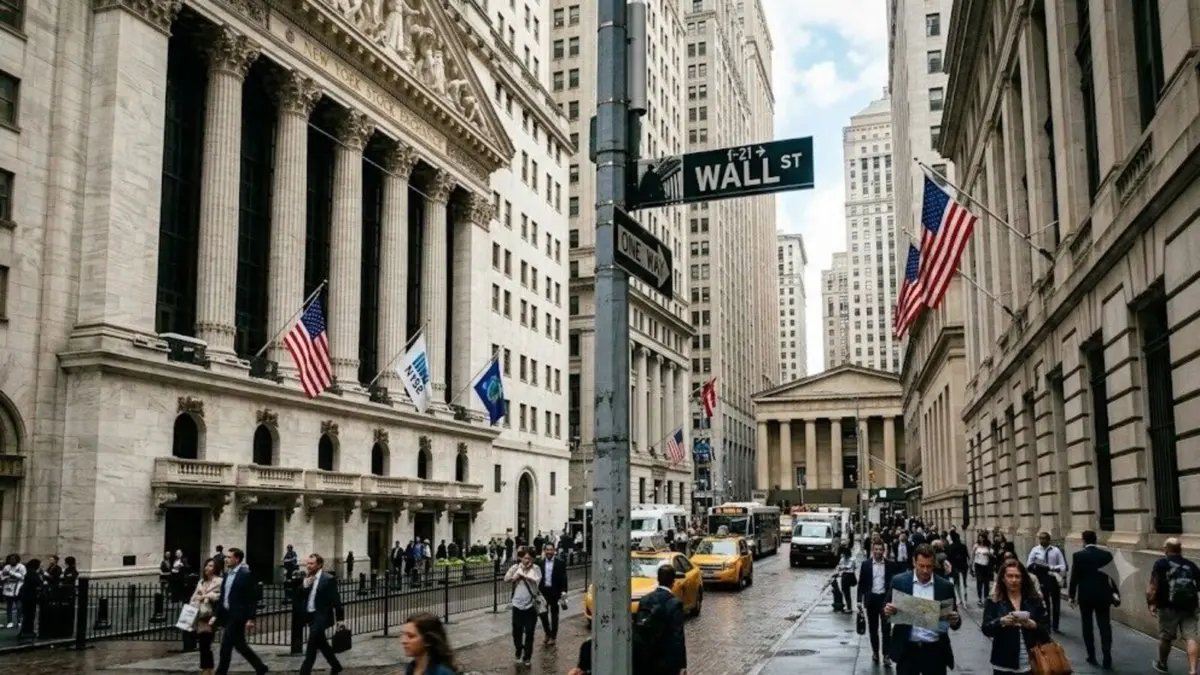
Wall Street is bracing for a pivotal week as a confluence of high-stakes economic data and the unofficial start of the corporate earnings season promises to test the resilience of the current market rally. At the center of this financial storm is the September Consumer Price Index (CPI) report, scheduled for release on Wednesday. This data point is expected to serve as the primary barometer for the Federal Reserve’s next move, specifically whether the central bank will opt for another interest rate hike in December or maintain a pause to allow previous tightening measures to fully permeate the economy.
The upcoming week represents a critical juncture for investors who are navigating a complex landscape of cooling labor markets, stubborn inflationary pressures, and a banking sector that is under intense scrutiny. Following a period of relative volatility, the major US indices—the S&P 500, Dow Jones Industrial Average, and Nasdaq Composite—all posted gains in the preceding week, but market participants remain wary that a hotter-than-expected inflation reading could swiftly reverse these advances.
The Inflation Litmus Test: CPI and PPI
The September CPI report arrives at a time when the Federal Reserve’s "higher for longer" mantra is being weighed against signs of economic moderation. In September, the Fed raised interest rates for the first time since 2023, a move that signaled its commitment to returning inflation to its 2% target, even at the risk of dampening growth. The Wednesday report will provide the first comprehensive look at price action following that rate hike.
Economists are particularly interested in the "core" CPI, which excludes volatile food and energy prices. While headline inflation often grabs the spotlight, the Fed prioritizes core data to understand underlying trends. If the data shows that service-sector inflation remains sticky or that shelter costs—a significant component of the CPI—are not cooling as quickly as anticipated, the probability of a December rate hike will likely surge.
Complementing the CPI data is the Producer Price Index (PPI), which measures inflation from the perspective of manufacturers and wholesalers. Often viewed as a leading indicator, the PPI can signal future changes in consumer prices as businesses pass on higher production costs to the public. Together, these two reports will form the backbone of the Fed’s data-dependent strategy heading into its late-October policy meeting.
Banking Giants Step into the Spotlight
As the macroeconomic debate rages, the microeconomic picture will come into sharper focus with the release of third-quarter earnings from the nation’s largest financial institutions. The banking sector is often considered a "canary in the coal mine" for the broader economy, reflecting the health of both corporate America and the average consumer.
On Tuesday, the market will receive results from JPMorgan Chase, Goldman Sachs, Citigroup, and Wells Fargo. These will be followed on Wednesday by reports from Morgan Stanley and Bank of America. Investors will be dissecting these reports for several key metrics:
- Net Interest Income (NII): With interest rates at elevated levels, banks have seen a boost in the difference between what they earn on loans and what they pay on deposits. However, as the cost of funding rises, analysts are looking for signs that NII growth may be peaking.
- Loan Loss Provisions: An increase in the amount of capital set aside to cover potential bad loans would signal that banks are preparing for a downturn or observing rising delinquency rates among consumers.
- Investment Banking Revenue: After a prolonged slump in mergers, acquisitions, and initial public offerings (IPOs), any uptick in activity at firms like Goldman Sachs and Morgan Stanley would be seen as a sign of returning corporate confidence.
- Consumer Sentiment: Commentary from bank CEOs regarding credit card spending and personal loan demand will provide a real-time pulse on the US consumer’s financial stamina.
Beyond the banking sector, other heavyweights including Johnson & Johnson, UnitedHealth Group, and BlackRock are also slated to report, offering a broader view of the healthcare and asset management industries.
Deciphering the Labor Market and Consumer Spending
The urgency surrounding the upcoming inflation data is amplified by the recent September jobs report, which showed a significant deceleration in hiring. The US economy added a mere 29,000 jobs in September, a figure that fell well below analyst expectations and sent shockwaves through the trading floor. Concurrently, the unemployment rate ticked up to 4.2%.
This cooling of the labor market presents a double-edged sword for the Federal Reserve. On one hand, a softer labor market reduces wage-push inflation, supporting the case for a pause in rate hikes. On the other hand, if hiring slows too abruptly, it raises the specter of a recession.

Retail sales data, also due this week, will further clarify this picture. Since consumer spending accounts for approximately 70% of the US Gross Domestic Product (GDP), any significant pullback in retail activity would suggest that high interest rates are finally curbing household appetites. Conversely, robust retail figures would indicate that the "soft landing" scenario—where inflation falls without a major economic contraction—remains a viable outcome.
Industrial Production and the Manufacturing Outlook
On Friday, the focus shifts to the industrial side of the economy with the release of September’s industrial production and capacity utilization data. The manufacturing sector has faced headwinds over the past year, including high borrowing costs and fluctuating global demand.
A strong showing in industrial production would suggest that the "real" economy is still expanding, potentially giving the Fed more "room to run" with restrictive monetary policy. However, continued weakness in manufacturing could bolster the arguments of those who believe the central bank has already tightened sufficiently.
Market Performance and Technical Context
Despite the looming uncertainty, Wall Street managed to end the previous week on a high note. The S&P 500 closed at 7,811.54, up 1.2% for the week. The Dow Jones Industrial Average finished at 51,654.95, a weekly gain of 0.9%, while the tech-heavy Nasdaq Composite rose to 27,366.17, gaining 0.6% over the five-day period.
The bond market has also seen significant action, with the yield on the 10-year US Treasury note settling at 5.24%. This yield is a critical benchmark for everything from mortgage rates to corporate debt, and its upward trajectory reflects the market’s expectation that interest rates will remain elevated for the foreseeable future.
In the commodities space, Brent crude oil prices have shown volatility, influenced by ongoing geopolitical tensions in the Middle East and shifting global supply dynamics. Energy costs remain a "wild card" for inflation; any sustained spike in oil prices could bleed into the CPI, complicating the Fed’s path toward its 2% target.
Chronology of Key Events for the Week Ahead
To navigate the coming days, investors are keeping a strict timeline of releases:
- Monday: A relatively quiet start to the week, with market participants positioning themselves ahead of the data deluge.
- Tuesday: The banking "Big Four" (JPMorgan, Goldman, Citi, Wells Fargo) release quarterly earnings before the opening bell. Market reaction will likely dictate the tone for the financial sector.
- Wednesday: The "Main Event." The Bureau of Labor Statistics releases the September CPI report at 8:30 AM ET. This is followed by earnings from Morgan Stanley and Bank of America.
- Thursday: PPI data is released, providing a secondary layer of inflation insight, alongside weekly initial jobless claims.
- Friday: Retail sales and industrial production data are released, offering the final pieces of the economic puzzle for the week.
Broader Implications and Analytical Outlook
The convergence of these events suggests that the "wait-and-see" approach adopted by many institutional investors is coming to an end. The Fed is currently in a delicate balancing act. If they hike rates in December, they risk over-tightening and triggering a sharp recession. If they pause while inflation remains above target, they risk losing credibility and allowing price expectations to become unanchored.
The banking results will be particularly telling regarding the impact of the 2026 interest rate environment. If the major banks report healthy margins but express caution about the future, it may signal that while the "engine" of the economy is still running, it is beginning to strain under the weight of debt costs.
Furthermore, the political climate cannot be ignored. With ongoing discussions regarding fiscal policy and the upcoming electoral cycles, any economic data point is likely to be viewed through a political lens, potentially adding to market volatility.
In summary, the week ahead is about more than just numbers; it is about the narrative of the US economy. Is the US heading for a controlled descent into price stability, or is it on the verge of a more turbulent economic adjustment? By Friday, the clarity provided by the CPI, retail sales, and bank earnings should provide a much firmer answer to that question, setting the stage for the final trading months of the year.
