

The U.S. housing market is once again navigating turbulent waters, as a recent uptick in conventional mortgage rates has prompted a discernible shift among borrowers towards adjustable-rate mortgages (ARMs). This pivot, a significant indicator of buyer sensitivity to borrowing costs, reflects the ongoing struggle for affordability in a market still grappling with elevated home prices and evolving economic pressures. As of the week preceding August 5, 2026, demand for ARMs surged, reaching its highest level since June, signaling a growing willingness among prospective homeowners to embrace a degree of interest rate risk in pursuit of lower initial payments.
Data released by the Mortgage Bankers Association (MBA) reveals that adjustable-rate mortgages constituted 8.5% of all mortgage applications last week, marking an increase from 8% in the prior week. This figure stands in stark contrast to the early years of the pandemic, specifically when mortgage rates plummeted to historic lows, and ARM demand languished at barely 3% of total applications. The current resurgence underscores a market environment where even marginal savings on interest rates can significantly impact a borrower’s monthly budget, particularly as the average contract interest rate for 30-year fixed-rate mortgages with conforming loan balances (capped at $832,750) climbed to 6.85% from 6.79% the previous week. Accompanying this rise, points — fees paid to the lender at closing to lower the interest rate — also increased to 0.67 from 0.65, including the origination fee, for loans with a 20% down payment. In contrast, the average rate for a five-year ARM saw a decrease, falling to 5.82% from 5.94%, presenting an attractive spread for rate-sensitive consumers.
The Resurgence of Adjustable-Rate Mortgages (ARMs)
Adjustable-rate mortgages are loans where the interest rate can change periodically after an initial fixed-rate period. Modern ARMs, often referred to as hybrid ARMs, typically feature an introductory fixed-rate term of 3, 5, 7, or 10 years, after which the rate adjusts annually based on a pre-selected index plus a margin. Crucially, these loans usually come with caps that limit how much the interest rate can increase or decrease in any given adjustment period and over the lifetime of the loan, offering a degree of protection against extreme rate volatility that was less common in the more speculative ARM products of the pre-2008 housing crisis era.
The current appeal of ARMs stems directly from their ability to offer significantly lower initial interest rates compared to their fixed-rate counterparts. For a borrower facing a nearly 7% rate on a 30-year fixed mortgage, a 5.82% rate on a 5-year ARM represents a substantial reduction in initial monthly payments. This difference can be the decisive factor for many struggling to meet affordability thresholds in increasingly expensive housing markets. The increased demand suggests that many borrowers are either betting on future rate declines before their fixed period expires, or they anticipate moving or refinancing within the initial fixed term, thus avoiding the potential for payment shock when rates adjust upwards. However, this strategy carries inherent risks, particularly if interest rates continue their upward trajectory or if market conditions prevent easy refinancing or sale in the future.
Economic Undercurrents Driving Rate Increases
The sustained upward pressure on mortgage rates is deeply intertwined with broader macroeconomic factors, primarily persistent inflation and the nation’s burgeoning federal budget deficit. Joel Kan, vice president and deputy chief economist at the MBA, articulated this connection, stating, "Mortgage rates moved higher last week, driven by ongoing investor concerns over inflation and the federal budget deficit. The 30-year fixed rate increased to 6.85 percent, the highest since June 2025 and 36 basis points higher than a year ago."
Inflationary Pressures: The Federal Reserve’s primary mandate includes maintaining price stability, and as such, it closely monitors key inflation indicators like the Consumer Price Index (CPI) and the Personal Consumption Expenditures (PCE) price index. Despite aggressive monetary tightening measures initiated in 2022 and continuing into 2023 and 2024, inflation has proven stubbornly persistent. Factors contributing to this include:
- Supply Chain Resilience: While improving, some global supply chains continue to experience disruptions, preventing a full return to pre-pandemic efficiency and contributing to higher input costs.
- Strong Labor Market: A historically tight labor market, characterized by low unemployment and consistent wage growth, fuels consumer spending power, which can, in turn, exert upward pressure on prices for goods and services.
- Geopolitical Events: Ongoing geopolitical tensions and conflicts can impact energy prices and global trade, adding another layer of inflationary complexity.
Investors react to these signals by demanding higher yields on bonds to compensate for the erosion of purchasing power, which directly translates to higher long-term interest rates, including those for mortgages.
Federal Budget Deficit: The nation’s federal budget deficit has ballooned in recent years, driven by increased government spending and, at times, reduced revenue. When the government issues more debt (Treasury bonds) to finance its operations, it increases the supply of these bonds in the market. To attract buyers for this increased supply, the government must offer higher yields. These Treasury yields serve as a benchmark for other long-term interest rates, including mortgage rates. The sheer volume of government borrowing competing with private sector demand for capital can therefore put upward pressure on borrowing costs across the economy.
Federal Reserve Policy: While the Fed directly influences short-term rates through the federal funds rate, its actions, particularly its stance on quantitative tightening (reducing its balance sheet by letting bonds mature without reinvesting), indirectly impact long-term rates. Market participants constantly assess the Fed’s future moves, and any signals indicating a prolonged fight against inflation or a less accommodative stance can immediately translate into higher mortgage rates as lenders price in these expectations.
Impact on Mortgage Application Volume
The rising cost of borrowing has inevitably dampened overall mortgage demand. Total application volume declined by 2.7% for the week, according to the MBA’s seasonally adjusted index. This decline is not uniform across all segments of the market.
Refinance Applications: The refinance market has been hit particularly hard. Applications to refinance a home loan plummeted by 6% for the week, and perhaps more tellingly, stood 25% lower than the same week one year ago. This represents the slowest pace for refinance activity since May 2025. With rates significantly higher than the historic lows of the pandemic era, and even higher than the rates many homeowners secured in the preceding years, the incentive to refinance has largely evaporated for a vast segment of the market. Only those with exceptionally high existing rates or those looking to tap into equity for home improvements or debt consolidation might find refinancing viable, and even then, the cost-benefit analysis has become increasingly stringent.
Purchase Applications: Applications for a mortgage to purchase a home were essentially flat, registering a marginal decline of 0.2% for the week. However, in a slight glimmer of resilience, these applications were still 4% higher than the same week one year ago. This suggests that while higher rates are undoubtedly a deterrent, underlying demand for homeownership persists, driven by demographic shifts, evolving housing needs, and a slowly improving inventory situation in some markets. Joel Kan elaborated, "Higher mortgage rates continue to weigh on prospective homebuyers looking to act, even as housing inventory has increased in many markets." This highlights the ongoing tension between buyer desire and financial capability.
Expert Perspectives and Market Sentiment
The prevailing sentiment among industry experts is one of cautious observation, given the confluence of economic factors at play. Beyond the direct commentary from Joel Kan, the broader real estate and financial sectors are echoing similar concerns and observations.
A hypothetical statement from Sarah Chen, a senior real estate analyst at Horizon Realty Group, might capture the market’s pulse: "We’re seeing a bifurcation in the buyer pool. Those who are truly motivated and financially robust are still in the market, often leveraging increased inventory to negotiate. However, the marginal buyer, particularly first-time homebuyers, is feeling the squeeze intensely. The pivot to ARMs is a clear indication that affordability remains the paramount challenge, even if it means taking on more risk." This perspective underscores the resilience of a segment of buyers while acknowledging the significant barriers for others.
From a financial advisory standpoint, the shift to ARMs prompts warnings about prudent financial planning. Dr. Michael O’Connell, a financial economist specializing in personal finance, could offer: "While ARMs offer immediate payment relief, borrowers must approach them with a clear understanding of the embedded risks. It’s crucial to model out potential payment increases under various interest rate scenarios and to have a robust plan for either refinancing or selling before the fixed period expires, especially if rates are projected to rise further. The ARMs of today are generally safer than those of two decades ago, but they are by no means risk-free." Such advice would emphasize the need for individual financial due diligence.
A Deeper Look at the Housing Market Landscape
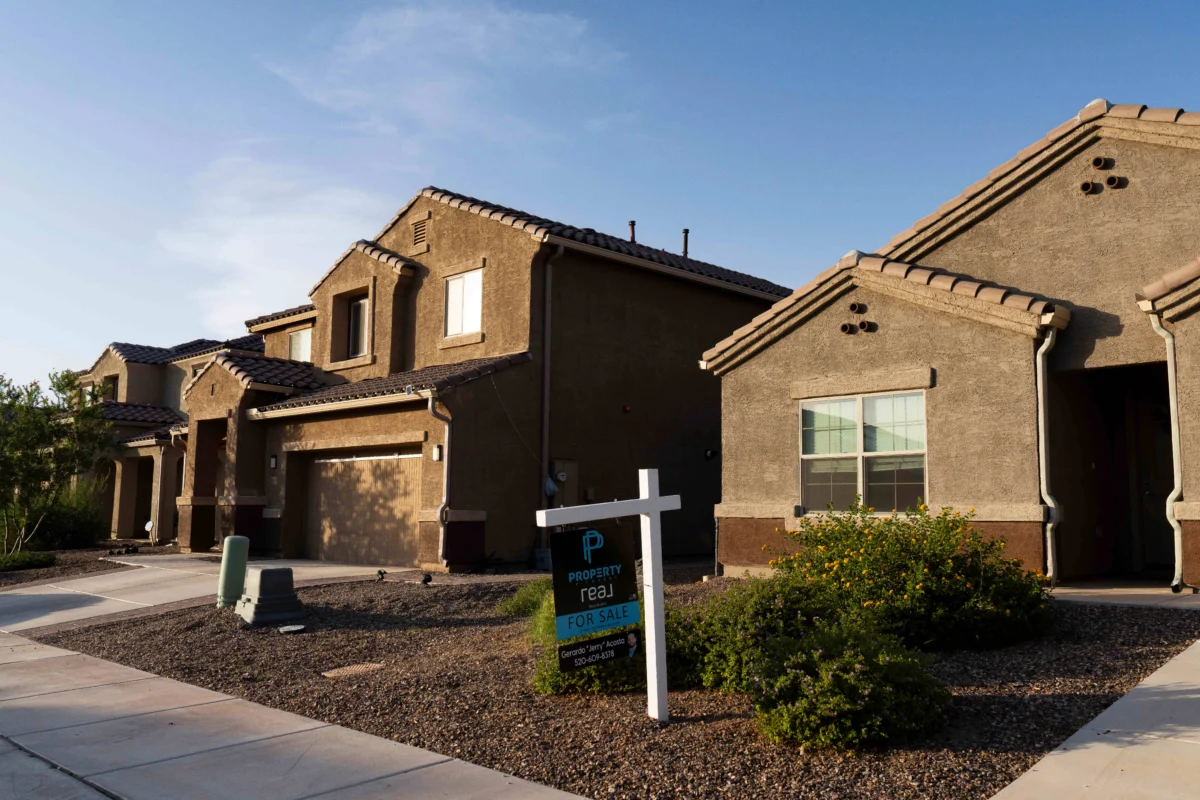
The dynamics observed in mortgage applications are a direct reflection of the broader housing market landscape across the United States. While national data provides an overarching view, local markets exhibit nuanced behaviors. The "For Sale" sign captured in Marana, Arizona, on August 5, 2026, serves as a microcosm of the national trend: properties are on the market, but the path to ownership is becoming more complex.
National Trends: Nationally, home prices, while cooling from their peak pandemic-era appreciation rates, remain significantly elevated in many metropolitan areas. Inventory levels have indeed shown signs of increasing in certain regions, offering buyers more choices and, in some cases, slightly easing the intense bidding wars that characterized earlier periods. However, this increase in supply has not been sufficient to fully offset the impact of higher interest rates on affordability. The median existing-home price continues to challenge potential buyers, especially when combined with mortgage payments that have dramatically increased compared to just a few years ago.
Challenges for First-Time Homebuyers: First-time homebuyers, who often have less equity to leverage and rely more heavily on financing, are particularly disadvantaged in the current environment. High down payments, closing costs, and now higher monthly mortgage payments create a formidable barrier to entry, pushing many to delay their homeownership dreams or to consider smaller, less desirable properties further from urban centers. The slight increase in purchase applications year-over-year, despite rising rates, might indicate a strong underlying demographic demand from millennials and Gen Z entering prime home-buying ages, who are simply finding ways to adapt, including exploring ARMs.
The Delicate Balance: The housing market is in a delicate balance. On one side, persistent demand, coupled with still-limited inventory in desirable areas, provides a floor for prices. On the other side, rising interest rates and affordability constraints act as a ceiling, preventing prices from escalating unchecked and potentially slowing transaction volumes.
The Risks and Rewards of Adjustable-Rate Mortgages
For borrowers currently turning to ARMs, the decision hinges on a careful weighing of immediate benefits against potential future risks.
Benefits:
- Lower Initial Payments: This is the primary draw. A lower initial interest rate translates directly to a lower monthly mortgage payment during the fixed-rate period, making homeownership more accessible in the short term.
- Increased Purchasing Power (Initially): By reducing the monthly payment, an ARM can theoretically allow a borrower to qualify for a larger loan amount than they would with a 30-year fixed mortgage at a higher rate, thus expanding their housing options.
- Potential for Savings if Rates Fall: If market interest rates decline before the fixed-rate period expires, or even during the adjustable period, the borrower could benefit from lower payments or have a better opportunity to refinance into a fixed-rate loan.
Risks:
- Payment Shock: The most significant risk. When the fixed-rate period ends and the rate adjusts, if interest rates have risen, the borrower’s monthly payment could increase substantially, potentially straining their budget.
- Inability to Refinance: If interest rates remain high or climb further, or if the borrower’s financial situation deteriorates, refinancing into a more stable fixed-rate loan might become difficult or impossible, leaving them exposed to fluctuating payments.
- Negative Equity: While less prevalent with modern ARM structures, a sharp decline in home values combined with rising rates could theoretically lead to a situation where the home is worth less than the outstanding mortgage balance, complicating any plans to sell or refinance.
- Market Volatility: ARMs introduce a direct link between a homeowner’s monthly expenses and the broader financial markets, making them more susceptible to economic shifts beyond their control.
Understanding the terms, including the index the ARM is tied to (e.g., SOFR, CMT), the margin, and all applicable caps (initial, periodic, and lifetime), is paramount for any borrower considering this option.
Forward Outlook: Navigating Future Rate Movements
The immediate trajectory of mortgage rates hangs significantly on upcoming economic data. Investors and economists are keenly awaiting monthly inflation numbers, which are scheduled for release later this week. These figures, particularly the Consumer Price Index (CPI), will provide crucial insights into whether inflationary pressures are truly abating or remaining stubbornly high.
Potential Scenarios:
- Inflation Cools More Than Expected: A significant downturn in inflation data could signal to the Federal Reserve that its monetary policy is having the desired effect. This might lead to expectations of a pause or even future rate cuts, which could prompt bond yields and, consequently, mortgage rates to fall sharply.
- Inflation Remains Elevated: Conversely, if inflation figures come in hotter than anticipated, it would reinforce concerns about persistent price pressures. This scenario would likely lead investors to anticipate further tightening from the Fed or a longer period of high rates, pushing mortgage rates even higher.
- Mixed Signals: Often, economic data presents a mixed picture, leading to continued market volatility and uncertainty, with rates moving in a narrow range or experiencing minor fluctuations.
The Federal Reserve’s next policy meetings will be critical. Their communications regarding future interest rate hikes, balance sheet reduction, and economic outlook will continue to heavily influence market sentiment and, by extension, mortgage rates. Prospective homebuyers and those considering refinancing will need to remain highly attuned to these developments, as rate locks and strategic timing could become even more crucial in managing their borrowing costs. Financial advisors will undoubtedly recommend pre-approval to lock in rates when possible, and to thoroughly review the terms of any adjustable-rate product.
In conclusion, the U.S. housing market on August 5, 2026, finds itself at a pivotal juncture. Rising mortgage rates, driven by persistent inflation and the federal budget deficit, are pushing a growing segment of borrowers towards the riskier yet initially more affordable adjustable-rate mortgages. While this shift reflects a resilient desire for homeownership, it also underscores the increasing financial strain on buyers and the complex interplay of economic forces shaping the real estate landscape. The coming weeks, with the release of key inflation data, will offer further clarity on the path ahead, but for now, uncertainty and strategic adaptation remain the defining characteristics of the American housing dream.
