

The final week of October 2026 has solidified a transformative period for the global financial landscape, as the integration of Environmental, Social, and Governance (ESG) factors moves from a voluntary framework into a strictly regulated mandate across major economies. As of November 1, 2026, the focus for institutional investors and corporate boards has shifted from the mere declaration of sustainability goals to the rigorous verification of performance data. This transition is underscored by the first full year of implementation for several key international reporting directives, creating a new era of transparency and accountability that was once viewed as a peripheral concern for the C-suite.
The week’s developments reflect a broader trend identified by ESG Today’s founder, Mark Segal, who has spent the last several years tracking the intersection of investment management and sustainability. With a background in U.S. equities and sell-side research, Segal’s analysis of the current market suggests that the "ESG backlash" of the mid-2020s has largely been replaced by a "pragmatic integration" phase. In this phase, the financial materiality of climate risk and social equity is no longer a matter of ideological debate but a fundamental component of fiduciary duty and risk management.
The Convergence of Global Reporting Standards
A primary theme of the past week has been the increasing harmonization between the International Sustainability Standards Board (ISSB) and the European Financial Reporting Advisory Group (EFRAG). As 2026 draws to a close, over 40 jurisdictions—including the United Kingdom, Australia, Singapore, and Brazil—have now formally integrated ISSB’s S1 (General Requirements) and S2 (Climate-related Disclosures) into their national regulatory frameworks.
This convergence is aimed at reducing the "reporting burden" on multinational corporations that previously navigated a fragmented landscape of disclosure requirements. According to data released this week by the Global Reporting Initiative (GRI), approximately 82% of the Fortune 500 now utilize a unified digital tagging system for their ESG data, allowing for real-time analysis by institutional investors. This standardization is critical as companies begin preparing their annual reports for the 2026 fiscal year, which for many will be the first time their sustainability data is subjected to the same level of auditing as their financial statements.
Chronology of Key Events: October 26 – November 1, 2026
The week began with a significant announcement from the European Commission regarding the second wave of the Corporate Sustainability Reporting Directive (CSRD). On Monday, October 26, the Commission released updated guidance for non-EU companies that meet the turnover threshold within the Eurozone, clarifying that these entities must provide "equivalent" reporting to their European counterparts starting in 2027. This move ensures a level playing field and prevents "jurisdictional arbitrage" where companies might move operations to avoid stringent environmental laws.
On Wednesday, October 28, the U.S. Securities and Exchange Commission (SEC) provided a status update on its climate-related disclosure rules. Following years of litigation and political maneuvering, the 2026 reporting cycle has seen the first successful implementation of Scope 1 and Scope 2 emissions reporting for large accelerated filers. The SEC’s Division of Corporation Finance noted a "marked improvement" in the specificity of climate-risk disclosures, particularly regarding the physical risks to supply chains posed by extreme weather events.
By Friday, October 30, the focus shifted to the voluntary carbon market (VCM). The Integrity Council for the Voluntary Carbon Market (ICVCM) announced that over 60% of all credits traded in the third quarter of 2026 now carry the "Core Carbon Principle" (CCP) label. This milestone is seen as a vital step in restoring trust in carbon offsets, which faced significant skepticism in 2023 and 2024 due to concerns over permanence and additionality.
Supporting Data: The Economic Reality of the Transition
The scale of the shift is perhaps best illustrated by the capital flows recorded throughout 2026. According to the BloombergNEF Global Energy Transition Investment Report, total investment in low-carbon energy technologies reached a record $2.1 trillion in the first three quarters of 2026. This represents a 25% increase from the same period in 2025.
Key data points from the past week include:
- Green Bond Issuance: Global issuance of green, social, and sustainability-linked bonds surpassed $1.2 trillion in October 2026, driven largely by sovereign issuers in emerging markets seeking to fund climate adaptation projects.
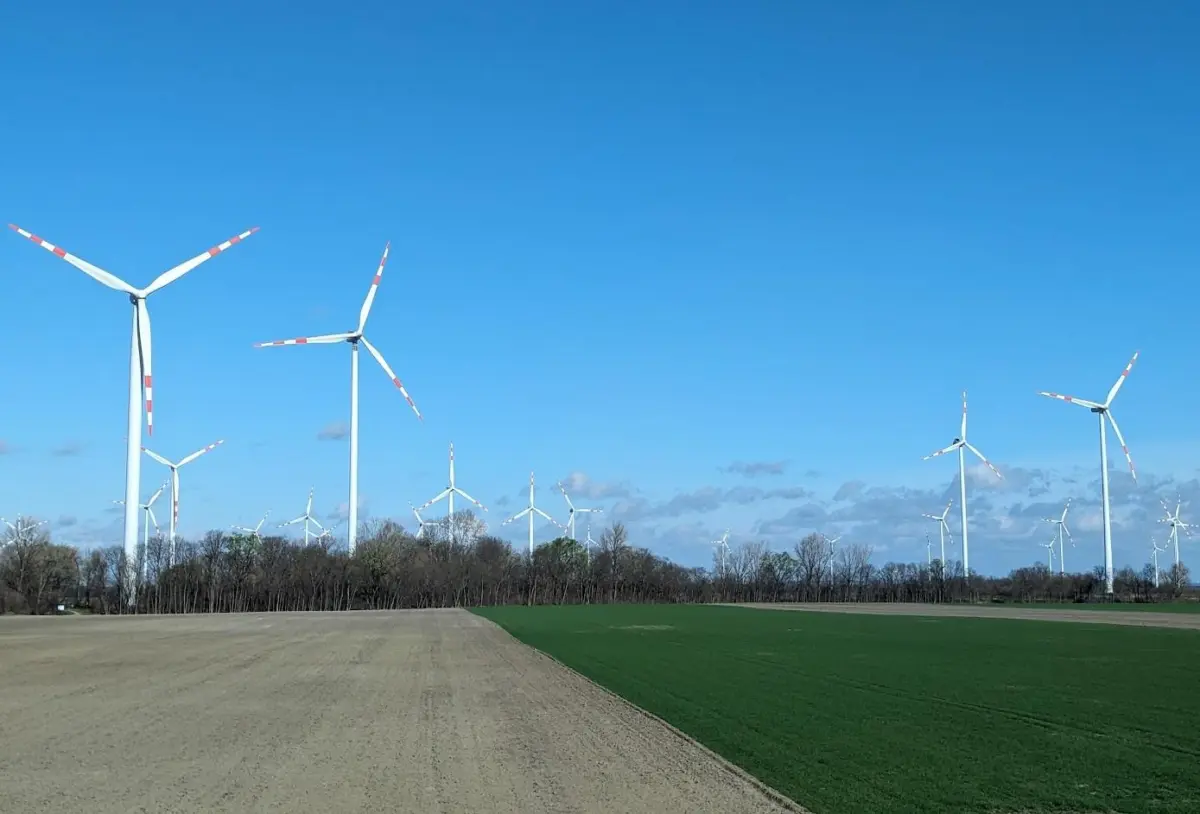
- Renewable Energy Capacity: The International Energy Agency (IEA) reported that wind and solar power now account for 38% of the global electricity mix, up from 28% in 2023. The image of Austrian wind farms, featured in this week’s review, serves as a testament to the infrastructure pivot occurring across the European continent.
- Human Capital Disclosure: A survey of 500 global asset managers revealed that 74% now consider "human capital management" (including workforce diversity and labor rights) to be as important as carbon footprints when determining the "S" component of ESG scores.
Official Responses and Industry Reactions
The week’s developments have drawn a range of reactions from industry leaders and policymakers. Emmanuel Faber, Chair of the ISSB, released a statement on October 29, emphasizing that the era of "greenwashing" is effectively over. "The infrastructure for a global baseline of sustainability disclosures is now in place," Faber stated. "Investors no longer have to guess which data is reliable; the rigor of the S1 and S2 standards provides a clear lens through which to view corporate resilience."
In the United States, several prominent asset managers have expressed a "return to basics" approach. Speaking at a conference in New York on October 30, a senior executive at a leading investment firm noted, "We are moving away from the political labels and focusing on the math. If a company isn’t accounting for the transition to a low-carbon economy, they are ignoring a fundamental risk to their terminal value. That isn’t politics; that’s portfolio management."
However, challenges remain. Small and Medium Enterprises (SMEs) continue to voice concerns about the cost of compliance. In a joint letter to the European Parliament, several trade associations argued that while the CSRD is well-intentioned, the data collection requirements for Scope 3 emissions (value chain emissions) remain prohibitively expensive for smaller firms that lack the sophisticated ERP systems of global conglomerates.
Broader Impact and Implications for 2027
As the world looks toward 2027, the implications of this week’s news cycle are clear. The "normalization" of ESG means that sustainability is no longer a separate department within a company but is being integrated into finance, legal, and operations.
1. The Role of Artificial Intelligence in ESG Data
One of the most significant undercurrents of the 2026 reporting cycle has been the role of Artificial Intelligence (AI). AI-driven platforms are now being used to scrape vast amounts of unstructured data—from satellite imagery of methane leaks to social media sentiment regarding labor practices—to verify corporate claims. This "outside-in" verification is making it increasingly difficult for companies to hide discrepancies between their public statements and their operational realities.
2. Transition Finance vs. Divestment
The debate between "divestment" and "engagement" has largely been settled in favor of transition finance. Rather than simply dumping stocks in high-carbon sectors, 2026 has seen a surge in "transition bonds" and "sustainability-linked loans" designed to help heavy industries—such as steel, cement, and shipping—decarbonize. This shift acknowledges that a global net-zero future requires the transformation of the existing economy, not just the funding of new green startups.
3. The "Social" Pillar Gains Ground
While climate has dominated the ESG conversation for a decade, 2026 marks the year the "Social" pillar achieved parity in terms of data quality. New regulations regarding supply chain due diligence, particularly in the EU and North America, have forced companies to provide granular data on human rights, fair wages, and safety standards across their entire global footprint.
Analysis of the Long-term Outlook
The trajectory established in this week’s review suggests that the global economy is in the midst of its most significant structural realignment since the Industrial Revolution. Mark Segal’s observations at ESG Today highlight a crucial point: the financial industry is the primary engine of this change. As a CFA charterholder with decades of experience in equity research, Segal notes that the demand for ESG data is coming from the "bottom up"—from the asset owners, pension funds, and individual investors who are increasingly concerned about the long-term viability of their holdings in a changing climate.
The week ending November 1, 2026, serves as a reminder that sustainability is no longer a "nice-to-have" or a marketing exercise. It is a core component of economic competitiveness. The companies that have invested in robust data systems, transparent reporting, and genuine operational changes are beginning to see a lower cost of capital and higher valuation multiples. Conversely, those that have lagged in their ESG integration are finding themselves increasingly marginalized by both regulators and the capital markets.
As we move into the final two months of 2026, the focus will remain on the upcoming COP31 negotiations, where the "New Collective Quantified Goal" (NCQG) for climate finance is expected to be a central topic. The progress made this week in standardized reporting and carbon market integrity provides a necessary foundation for those high-level political discussions, ensuring that the financial commitments made by nations are backed by transparent and verifiable corporate action.
In summary, the week has been characterized by a move toward maturity. The "wild west" of ESG is being replaced by a structured, audited, and financially relevant system that promises to redefine how value is measured in the 21st century. For investors and corporate leaders alike, the message is clear: the data is here, the regulations are in force, and the transition is well underway.
