

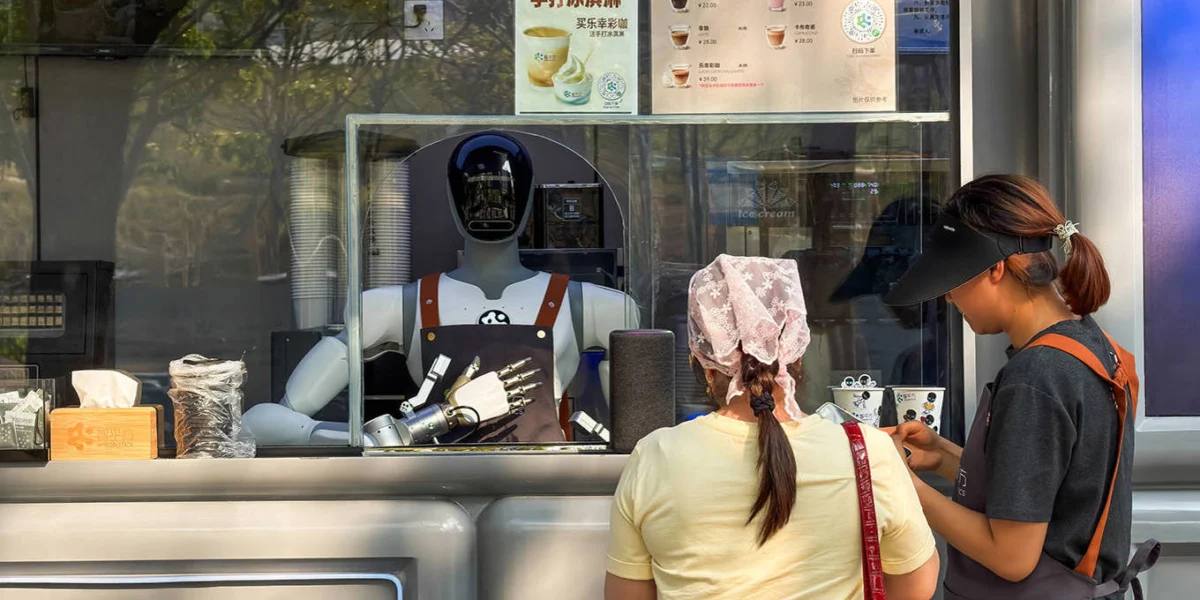
The renminbi has staged a notable recovery against the dollar since the second half of 2025, prompting renewed discussion about how much further it can rise. In China, AI-driven productivity gains will most likely be in non-tradable services, which could push down relative prices and put downward pressure on the renminbi’s real exchange rate. To ensure that this does not also mean lower income and weaker demand, policymakers should ensure that the productivity dividend is broadly shared.
Economic Landscape: A Shifting Tide for the Renminbi
Following a period of relative stability, the Chinese renminbi (RMB) has demonstrated a significant upward trajectory against the US dollar since the latter half of 2025. This resurgence has reignited conversations among economists, financial analysts, and international observers regarding the currency’s future appreciation potential. While a stronger renminbi can signal economic robustness and potentially lower import costs, its trajectory is intricately linked to the nation’s evolving economic structure, particularly the impact of Artificial Intelligence (AI) on productivity.
The primary thesis posits that AI-driven productivity enhancements in China will disproportionately manifest within the non-tradable services sector. This sector, encompassing areas like domestic retail, healthcare, education, and personal services, is less exposed to international competition than the manufacturing or export-oriented industries. As AI technologies streamline operations, improve efficiency, and potentially reduce labor costs within these domestic services, a surplus of production capacity relative to domestic demand could emerge. This scenario, according to economic theory, would lead to a decrease in the relative prices of these non-tradable goods and services within China.
The Mechanics of Relative Price Shifts and Real Exchange Rates
The concept of a "real exchange rate" is crucial here. It measures the relative price of goods and services between two countries, taking into account the nominal exchange rate. If domestic prices in China fall relative to international prices (even with a stable nominal exchange rate), the real exchange rate would depreciate. Conversely, if domestic prices rise faster than international prices, the real exchange rate appreciates.
In the context of AI-driven productivity gains in China’s non-tradable services, the expectation is that the cost of providing these services will decrease. This could translate into lower prices for consumers. If these price reductions are substantial enough, they could outpace any inflation in the tradable goods sector or in other countries. This divergence in price levels would exert downward pressure on the renminbi’s real exchange rate.
Potential Pitfalls: Deflationary Risks and Weakening Demand
While a stronger nominal renminbi might seem like an unqualified positive, the potential for a real exchange rate depreciation due to falling domestic service prices presents a nuanced challenge. If the productivity gains are not accompanied by commensurate increases in aggregate demand, the scenario could inadvertently lead to a deflationary environment. Falling prices, if widespread and sustained, can disincentivize spending as consumers and businesses anticipate even lower prices in the future. This can create a vicious cycle of reduced demand, lower production, and further price declines.
Moreover, a significant real depreciation of the renminbi, even if nominal appreciation is occurring, could signal underlying economic imbalances. It might suggest that China’s economy is struggling to absorb its own output, particularly in the services sector, leading to a situation where the country is becoming relatively cheaper for domestic consumption but not necessarily more competitive on the global stage in terms of its overall economic output value. This could ultimately translate into weaker overall domestic income growth and a dampening of consumer and business confidence, thereby weakening aggregate demand.
Historical Context: China’s Economic Evolution and AI’s Role
China’s economic trajectory over the past few decades has been characterized by rapid industrialization and export-led growth. However, in recent years, the government has been actively seeking to rebalance the economy towards domestic consumption and services. This shift is driven by a recognition of the limitations of an export-heavy model, including susceptibility to global economic downturns and rising trade protectionism.
The integration of AI technologies represents a significant accelerant for this ongoing economic transformation. AI’s potential to automate tasks, optimize processes, and generate new insights is particularly well-suited to the service sector, which is often more labor-intensive and less amenable to traditional automation than manufacturing. For instance, AI-powered customer service chatbots can handle a significant volume of inquiries, AI-driven diagnostic tools can assist medical professionals, and personalized learning platforms can enhance educational delivery.
Timeline of Renminbi Movements and AI Integration
- Early to Mid-2020s: Initial discussions and pilot programs for AI integration across various Chinese industries, including early-stage applications in customer service and data analysis. The renminbi experiences fluctuations influenced by global economic conditions and trade tensions.
- Late 2025: A discernible shift in the renminbi’s performance against the US dollar. This period marks the beginning of a sustained recovery, potentially reflecting a combination of factors including China’s economic resilience, policy interventions, and an increasing confidence in its growth prospects. Concurrently, the adoption of AI technologies begins to show more tangible impacts on productivity, particularly in domestic-facing sectors.
- 2026 and Beyond: The focus intensifies on the specific impact of AI-driven productivity gains in non-tradable services. Economists begin to analyze the implications for relative price levels and the real exchange rate. The potential for deflationary pressures and weakened domestic demand becomes a central concern for policymakers.
Supporting Data and Economic Indicators
While specific data on AI’s impact on non-tradable service prices in China is still emerging, several indicators offer insights:
- Consumer Price Index (CPI) for Services: Monitoring the CPI component specifically attributed to services can reveal trends in domestic price levels. A sustained decline or significant slowdown in service price inflation, even as the overall CPI might be stable or rising due to other factors, would support the hypothesis. For example, if the services component of CPI grows at a rate significantly lower than the overall CPI, it could indicate productivity gains are dampening price increases.
- Labor Productivity in Services: Official statistics on labor productivity growth within sectors like retail, hospitality, healthcare, and education can provide evidence of efficiency improvements. Higher productivity growth in these sectors, especially when outpacing capital investment in those areas, would suggest technological adoption, including AI, is playing a role.
- Renminbi Nominal vs. Real Exchange Rate Data: Tracking both the nominal exchange rate (e.g., RMB/USD) and measures of the real exchange rate, which adjust for inflation differentials between China and its trading partners, is critical. A divergence where the nominal rate appreciates but the real rate depreciates would strongly support the argument.
- Foreign Direct Investment (FDI) in Technology and Services: While not directly a price indicator, FDI flows into AI development and service-oriented businesses can signal investment trends and anticipated growth in these areas.
Official Responses and Policy Considerations
The Chinese government and the People’s Bank of China (PBoC) are keenly aware of the dual potential of AI-driven productivity. Policymakers are likely to be considering a multi-pronged strategy:
- Broadening the Distribution of Productivity Gains: The core recommendation from analysts is to ensure the benefits of AI are shared broadly. This could involve policies aimed at:
- Wage Growth: Encouraging businesses to pass on productivity savings through higher wages for workers, thereby boosting household income and consumption.
- Tax Reductions or Subsidies: Targeted fiscal measures that put more disposable income into the hands of consumers.
- Investment in Human Capital: Ensuring that the workforce is equipped with the skills needed to work alongside AI, potentially through retraining programs and educational reforms. This would help maintain demand for labor and prevent widespread wage stagnation.
- Stimulating Domestic Demand: Beyond simply distributing gains, active measures to boost consumption might be necessary. This could include:
- Fiscal Stimulus: Government spending on infrastructure, social welfare programs, or direct consumer rebates.
- Monetary Policy Adjustments: While the PBoC might be cautious about overly stimulating an economy already facing potential deflationary pressures, finely tuned interest rate adjustments or targeted liquidity injections could be considered.
- Diversifying AI Applications: Encouraging AI development and adoption in tradable sectors as well, to balance the impact and enhance overall export competitiveness. This could involve AI-driven innovations in manufacturing, logistics, and R&D.
- Monitoring Inflationary and Deflationary Pressures: The PBoC will need to closely monitor price indices and economic activity to preemptively address any signs of sustained deflation or excessive inflation.
Broader Impact and Implications
The implications of AI-driven productivity in China extend beyond its borders:
- Global Trade Dynamics: A stronger renminbi, even with real depreciation, could influence global trade patterns. Lower domestic service costs could make Chinese goods and services relatively more affordable for domestic consumers, potentially impacting global demand for certain imports.
- Investment Flows: The perception of China’s economic health, influenced by its ability to manage AI’s impact, will continue to shape international investment decisions.
- Technological Leadership: China’s success in leveraging AI for broad-based economic gains could solidify its position as a global leader in AI development and application, influencing the pace and direction of technological innovation worldwide.
- The Future of Work: The widespread adoption of AI in services raises fundamental questions about the future of employment and the skills required in an increasingly automated economy. China’s experience will offer valuable case studies for other nations grappling with similar transitions.
In conclusion, the renminbi’s recent strength is a positive development, but its sustainability and the broader economic implications hinge on China’s ability to effectively manage the complex interplay between AI-driven productivity, domestic price levels, and aggregate demand. A proactive and inclusive policy approach will be crucial to ensure that the AI revolution translates into widespread prosperity rather than a deflationary spiral. The coming years will be a critical test of China’s economic policymaking prowess in navigating this new technological frontier.
