

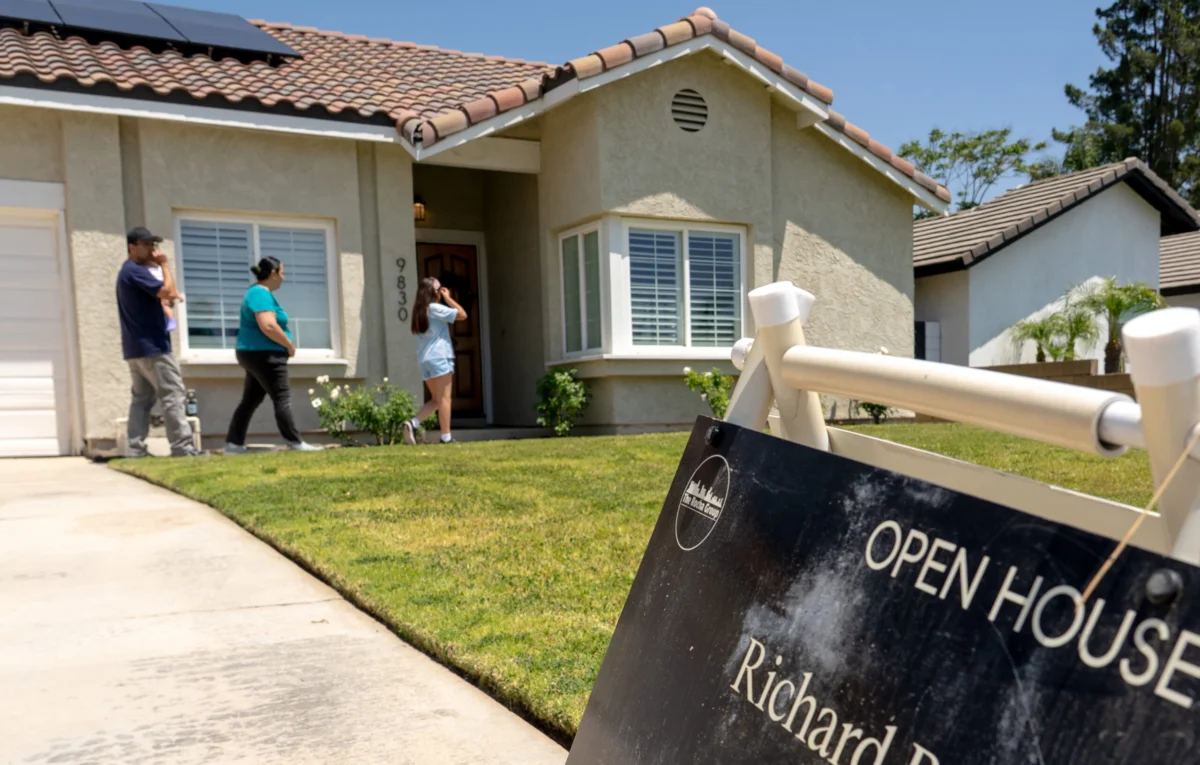
Against a backdrop of stubbornly persistent inflationary pressures, yields on longer-term U.S. Treasury bonds have been steadily climbing, a trend that experts widely agree is poised to keep borrowing costs elevated across the economy. This impact is particularly pronounced for long-term fixed-rate loans such as residential mortgages, which directly track these benchmark rates. The financial markets have reacted with a cautious reassessment of the economic landscape, factoring in both domestic inflationary dynamics and significant geopolitical influences.
On Tuesday, the yield on the bellwether U.S. 30-year Treasury bond notably surged to 5.323%, marking a 19-year high before slightly receding to just under 5.3%. Concurrently, the 10-year Treasury yield, a critical benchmark for the pricing of fixed mortgage rates and various other longer-term loans, hovered above 4.7%. This represents a significant increase when compared to the period preceding the onset of the Iran War at the end of February, when the 10-year yield was comfortably below 4%. This upward trajectory in bond yields clearly signals growing discomfort among investors regarding the long-term outlook for inflation and the Federal Reserve’s capacity to rein it in effectively.
Understanding the Inflationary Environment and Geopolitical Catalysts
The current inflationary climate is a complex tapestry woven from various economic and geopolitical threads. Prior to the escalation of the Iran War, specifically in January of the current year, the annual inflation rate, as measured by the Consumer Price Index (CPI), stood at 2.4%. While above the Federal Reserve’s long-term target of 2%, it suggested a gradual deceleration from previous peaks. However, the eruption of hostilities in Iran significantly altered this trajectory.
The conflict immediately triggered a spike in global energy prices, particularly crude oil, due to concerns about supply disruptions in a crucial oil-producing region. Energy costs are a fundamental component of the overall inflation picture, impacting everything from transportation and manufacturing to consumer goods and services. As Jeff DerGurahian, LoanDepot’s chief investment officer and head economist, observed, higher energy prices "stemming from the Iran conflict remain an important part of the inflation picture." This external shock exacerbated pre-existing supply chain vulnerabilities and domestic demand pressures, pushing the annual rate of inflation to 3.4% in July, a substantial increase and well beyond the Fed’s desired target.
The Federal Reserve’s Mandate and Market Expectations
The Federal Reserve’s dual mandate is to achieve maximum employment and maintain price stability, with the latter often translated into a 2% average inflation target. In response to persistent inflationary pressures, the Fed has undertaken a series of aggressive monetary policy tightening measures over the past year and a half, including multiple interest rate hikes and quantitative tightening (reducing its balance sheet). The objective of these actions is to cool demand, thereby bringing inflation back down to target.
However, the sustained rise in longer-term bond yields suggests that bond investors are increasingly skeptical about the Fed’s ability to achieve its 2% inflation target without further, potentially more aggressive, action or that inflation will simply remain elevated for a longer period than previously anticipated. Lawrence Yun, chief economist for the National Association of Realtors, articulated this sentiment clearly: "The higher bond yields on long-dated securities, like the 30-year Treasury, clearly indicate discomfort over persistently high inflation in the future." This "discomfort" translates into investors demanding a higher premium (yield) to hold long-term debt, as they perceive a greater risk of their returns being eroded by future inflation. The market’s perception of the Fed’s resolve and the actual trajectory of inflation are therefore intertwined, creating a dynamic environment for bond pricing.

What Bond Yields Mean for Mortgage Rates: A Direct Correlation
The most direct and immediate impact of rising Treasury yields is felt in the housing market, specifically through mortgage rates. Fixed-rate mortgages, particularly the popular 15- and 30-year terms, are closely tied to the performance of the 10-year Treasury note. When the yield on the 10-year Treasury rises, so too do the costs for lenders to fund new mortgages, which they then pass on to consumers in the form of higher interest rates.
As of Tuesday, the average rate for a 30-year, fixed-rate mortgage had climbed to 6.75%, an increase from 6.69% just last week, according to data from Mortgage News Daily. This upward trend is a clear reflection of the broader movement in bond markets. Lawrence Yun reiterated, "The impact on mortgage rates is directly related to higher bond yields. Independent of the Federal Reserve policy, higher inflation and higher overall long-term borrowing costs will mean higher mortgage rates." His assessment underscores a grim reality for prospective homebuyers: a meaningful decline in mortgage rates is not to be expected in the near future.
The implications for the housing market are substantial. Higher mortgage rates significantly erode buyer affordability, as monthly payments increase even if home prices remain stagnant or decline slightly. This can lead to reduced purchasing power, prompting some buyers to delay purchases, seek smaller homes, or move to more affordable regions. The sustained pressure on rates could also cool demand in the housing market, potentially impacting home sales volumes and price appreciation.
For consumers navigating this challenging environment, experts offer some strategic considerations. Yun suggested that "some may want to consider shorter-term mortgage rates, like seven-year [adjustable-rate mortgages], which lock in fixed mortgage payments for the first seven years of the loan before readjusting." This option can be particularly appealing for individuals who are confident they will move or refinance within that initial fixed period, thus mitigating the risk of future rate adjustments. Other strategies could include making a larger down payment to reduce the loan amount, or "buying down" the interest rate by paying discount points upfront, although these options require additional capital.
Broader Economic Ripple Effects: Other Consumer Loans
The influence of rising bond yields extends far beyond mortgages, permeating nearly all facets of consumer credit. Rates on car loans, credit cards, and student debt are all either directly or indirectly affected by the broader movements in bond markets and the Federal Reserve’s policy decisions.
Auto Loans: The auto loan market is highly susceptible to these broader economic factors. Jessica Caldwell, head of insights at Edmunds, noted that "auto loan rates don’t move in a vacuum, but sustained pressure on Treasury yields inevitably pushes up borrowing costs across the financing spectrum." Consumers are already grappling with elevated interest rates, with average new-vehicle APRs hovering around 7% and used vehicle APRs even higher at 10.6%. If bond yields continue to keep overall interest rates high, auto lenders will have little choice but to maintain or even increase these APRs, further straining consumer budgets already under pressure from high inflation and other rising costs. This dynamic could lead to a slowdown in vehicle sales, particularly for new cars, as affordability becomes a significant barrier for many buyers.
Credit Cards: Variable credit card rates are closely pegged to the prime rate, which, in turn, is heavily influenced by the Federal Reserve’s benchmark interest rate and overall inflation expectations. As Brett House, an economics professor at Columbia Business School, highlighted, "It typically is an immediate pass-through to some consumer rates. Variable and some fixed-rate borrowing will reset rates on a daily basis." This means that as the Fed maintains or raises its policy rates in response to inflation, the cost of carrying a credit card balance automatically increases for consumers, compounding their debt burden. For those with significant credit card debt, the combination of high principal and escalating interest rates creates a formidable financial challenge.

Student Loans: While federal student loan rates are generally fixed for the life of the loan once disbursed, the rates for new borrowers are directly linked to the 10-year Treasury note auction results. For instance, rates for new federal student loans for the upcoming academic year rose based on the last 10-year Treasury note auction conducted in May. This means that students taking out new federal loans face higher borrowing costs than their predecessors, adding to the long-term financial burden of higher education. Private student loans, which often have variable rates or fixed rates tied to market benchmarks, are also subject to the same upward pressure from rising bond yields.
The "Double Whammy" and Broader Implications
The confluence of high inflation and elevated borrowing costs creates a "double whammy" for consumers, as aptly described by Ted Rossman, a principal consumer finance analyst at Money Management International. "When prices are high, and borrowing costs are high — as they are now — you feel like you’re getting squeezed from all sides," Rossman explained. This squeeze impacts discretionary spending, savings, and overall financial well-being. Households are forced to allocate a larger portion of their income to essential goods and services (due to inflation) and debt servicing (due to higher interest rates), leaving less for other expenditures or investment.
Beyond individual consumers, the ripple effects extend to the broader economy. Elevated borrowing costs can stifle business investment and expansion plans. Companies facing higher interest rates on their corporate bonds or bank loans may postpone or scale back capital expenditures, hiring, and research and development. This reduction in private sector activity can, in turn, dampen overall economic growth. Furthermore, the U.S. government itself faces higher costs to service its massive national debt when Treasury yields rise, potentially impacting future fiscal policy decisions and resource allocation.
Expert Outlook and Future Trajectories
The prevailing sentiment among economists and financial analysts is that the current environment of elevated bond yields and higher borrowing costs is likely to persist for some time. Jeff DerGurahian articulated this perspective, suggesting that "Longer-term bond investors may need more evidence that the post-pandemic inflation cycle is truly behind us and that the economy is returning to a slower-growth, slower-inflation environment before 10- and 30-year Treasury yields move meaningfully lower." This implies a need for sustained, unambiguous data showing a deceleration in inflation across multiple indicators, not just temporary dips.
Key factors that will shape the future trajectory include:
- Inflation Data: Continued monitoring of CPI, Producer Price Index (PPI), and the Personal Consumption Expenditures (PCE) price index (the Fed’s preferred measure) will be crucial.
- Employment and Wage Growth: The strength of the labor market and the pace of wage increases are significant drivers of inflation.
- Geopolitical Stability: Developments in the Iran War and other global hotspots, particularly those impacting energy markets, will continue to exert influence.
- Federal Reserve Communications: The Fed’s rhetoric, projections, and actual policy decisions will be closely scrutinized for signals about future interest rate movements.
While some analysts hold out hope for a "soft landing" where inflation recedes without triggering a severe recession, the current bond market signals a more challenging path. The sustained demand for higher yields indicates a market grappling with the realities of sticky inflation and the potential for a more prolonged period of tighter monetary conditions.
In conclusion, the recent surge in longer-term Treasury yields serves as a stark reminder of the interconnectedness of inflation, monetary policy, and the cost of borrowing for consumers and businesses alike. With the 30-year Treasury yield hitting a 19-year high and the 10-year yield remaining elevated, the era of readily available cheap credit appears to be firmly in the rearview mirror. This new reality demands careful financial planning and strategic decision-making from households and corporations as they navigate an economic landscape defined by persistent inflationary pressures and a Federal Reserve committed to price stability, even if it means sustained higher borrowing costs. The ongoing vigilance over economic indicators and policy shifts will be paramount for understanding the evolving financial environment.
