

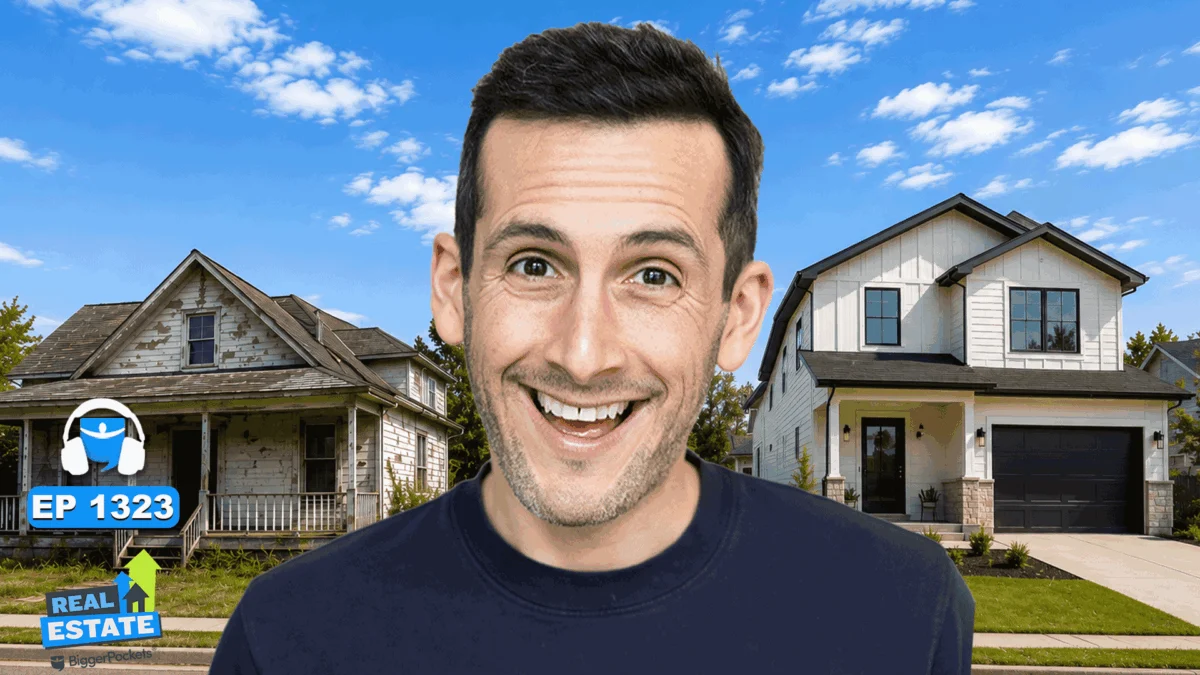
The real estate investment sector in 2026 is witnessing a historic shift in strategy as the traditional dominance of the "Buy, Rehab, Rent, Refinance, Repeat" (BRRRR) method faces unprecedented competition from new construction properties. For over a decade, professional investors prioritized distressed assets, utilizing forced appreciation to build equity and recycle capital. However, a unique convergence of high builder inventory, aggressive developer incentives, and a narrow price gap between new and existing homes has forced a re-evaluation of the optimal path to portfolio scaling.
The 2026 Market Pivot: Why New Construction is Gaining Ground
Historically, new construction carried a significant premium that deterred most rental property investors. In a standard market, a newly built home could cost 20% to 30% more than a comparable existing property. By 2026, this dynamic has inverted in several key U.S. regions. Data from the National Association of Home Builders (NAHB) indicates that the median price for a newly built home has occasionally dipped below that of existing homes, with recent analyses showing new builds selling for an average of $1,400 less than their older counterparts.
This anomaly is driven by a "builder inventory overhang." Unlike individual homeowners, who may choose to delist their properties if they do not achieve a specific price, large-scale developers operate on a volume-based business model. Carrying finished inventory on their balance sheets incurs significant holding costs, including interest on construction loans and property taxes. To clear these assets, major national builders like Lennar have introduced investor-specific marketplaces, offering incentives that are largely unavailable in the resale market.
The Anatomy of Builder Incentives
The primary catalyst making new construction viable for investors in 2026 is the "mortgage rate buydown." While market interest rates for investment properties have hovered around 7%, builders are utilizing their massive capital reserves to offer financing as low as 4.5% to 5.5%.
These incentives typically manifest in three forms:
- Permanent Rate Buydowns: The builder pays an upfront fee to the lender to lower the interest rate for the entire 30-year term of the mortgage.
- Closing Cost Credits: Developers often cover 100% of the closing fees, which can save an investor between $3,000 and $6,000 in upfront capital.
- Upgraded Finishes: To move units in less competitive subdivisions, builders are including high-end appliances, landscaping packages, and extended warranties as standard features.
Comparative Case Study: Sherman, Texas
To understand the practical implications of these two strategies, analysts have looked toward high-growth secondary markets such as Sherman, Texas. Located north of the Dallas-Fort Worth metroplex, Sherman has become a focal point for real estate activity due to massive industrial investment. Texas Instruments is currently executing a $60 billion expansion in the area, a move expected to create thousands of high-paying technical jobs and a subsequent surge in housing demand.
Scenario A: The New Construction Model
In the Sherman market, a new construction home from a major developer currently lists for approximately $243,000. This 1,700-square-foot, four-bedroom, two-bathroom property represents the "builder grade" standard: functional, modern, and highly appealing to the current tenant demographic.
Financial Snapshot:
- Purchase Price: $243,000
- Interest Rate: 4.5% (via builder buydown)
- Monthly Rent: $2,000
- Maintenance Reserve: 5% (lower due to warranties)
- Cash-on-Cash Return: Approximately 3.25% to 4%
The primary advantage here is predictability. With a 10-year structural warranty and brand-new systems (HVAC, roof, plumbing), the investor faces minimal capital expenditure (CapEx) risk for the first decade of ownership.
Scenario B: The BRRRR (Value-Add) Model
A comparable existing home in an established Sherman neighborhood might list for $160,000. This 1960s-era ranch-style home offers a similar 1,700-square-foot footprint but requires significant modernization, including kitchen remodeling, flooring replacement, and the removal of dated aesthetic features like popcorn ceilings.
Financial Snapshot:
- Purchase Price: $160,000
- Renovation Budget: $35,000
- All-In Cost: $195,000
- After Repair Value (ARV): $260,000
- Interest Rate: 7.0% (standard investor rate)
- Cash-on-Cash Return: 3.3% (pre-refinance)
While the initial cash-on-cash return is similar to the new build, the BRRRR strategy generates $65,000 in immediate equity. This equity can be harvested through a cash-out refinance, allowing the investor to recover their initial down payment and renovation capital to fund the next acquisition.
Analyzing the Compound Annual Growth Rate (CAGR)
The divergence between the two strategies becomes most apparent when examining long-term wealth accumulation. The new construction deal in the 2026 market typically yields a CAGR of roughly 10%. This is a respectable return that competes with the historical average of the S&P 500 while providing the tax advantages inherent in real estate, such as depreciation.
Conversely, the BRRRR deal offers a projected CAGR of 17% or higher. This superior growth is not derived from monthly cash flow—which is often lower due to higher interest rates—but from the massive equity injection achieved during the renovation phase. For investors focused on "velocity of money," the ability to create $65,000 in value through a $35,000 investment remains the most powerful tool for rapid portfolio expansion.
Operational Considerations: Maintenance and Renter Demand
A critical factor often overlooked in the 2026 landscape is the "tenant preference" shift. Modern renters, particularly those in the burgeoning tech sectors of North Texas, show a marked preference for new construction. Features such as energy-efficient windows, smart home integration, and open-concept floor plans allow new builds to command higher rents and experience lower vacancy rates.
Furthermore, the "Harvest Phase" of investment must be considered. For veteran investors looking to reduce their management burden, new construction is the superior choice. An older BRRRR property, even after a renovation, retains aging "bones." Issues with 60-year-old foundations, sewer lines, or electrical grids can lead to "lumpy" cash flow, where a single major repair wipes out an entire year’s profit. New construction provides a "smoothed" cash flow profile that is highly attractive for those nearing retirement or those working full-time jobs who cannot oversee frequent repairs.
Strategic Recommendations for 2026 Investors
The choice between value-add and new construction in 2026 is no longer a matter of one being objectively better than the other; rather, it depends on the investor’s current phase of growth.
The Scaling Investor
For those in the early stages of building a portfolio with limited capital, the BRRRR method remains the gold standard. The ability to "recycle" the same $50,000 through three or four properties over five years is the only way to achieve exponential growth. These investors should focus on "non-disclosure" states like Texas, where finding undervalued gems requires more localized expertise and boots-on-the-ground networking.
The Passive or High-Net-Worth Investor
For individuals with significant liquid capital or high-stress full-time careers, the new construction route offers a "turnkey" experience with institutional-grade support. The combination of a 4.5% interest rate and a builder warranty creates a bond-like investment with the upside of real estate appreciation. This group should prioritize developers with "investor marketplaces" that streamline the acquisition and management process.
The Transitioning (Harvest) Investor
Investors who have spent the last decade managing intensive renovations may find 2026 the ideal time to consolidate. By selling off older, high-maintenance assets through 1031 exchanges and moving that equity into a portfolio of new construction homes, they can maintain their income levels while drastically reducing their operational headaches.
Broader Economic Impact and Future Outlook
The rise of investor interest in new construction is beginning to influence broader housing policy. As builders pivot to serve the investor class, there is increased pressure on municipalities to approve high-density subdivisions specifically designed for the "Build-to-Rent" (BTR) model. This trend is helping to alleviate the chronic undersupply of rental housing in fast-growing corridors like Sherman, TX, and the "Silicon Prairie."
However, analysts warn that the current window of builder incentives may not stay open indefinitely. As the inventory overhang clears and if the Federal Reserve begins to lower benchmark rates, the gap between market rates and builder-subsidized rates will narrow. For now, the 2026 real estate market presents a rare "equilibrium" where both the grit of the renovator and the strategy of the new-build buyer can find significant paths to success. The determining factor for the "better" investment remains the math, but for the first time in years, that math is increasingly pointing toward the smell of fresh paint and new lumber.
