

The United States labor market presented a puzzling dichotomy in July, with nonfarm payrolls experiencing an unexpected decline while the unemployment rate simultaneously decreased. This contradictory data has left investors and economists grappling with how to interpret the latest employment figures, offering mixed signals about the trajectory of the nation’s economic recovery and the Federal Reserve’s potential policy decisions. The discrepancy between job creation and unemployment suggests a nuanced labor market dynamic that defies simple interpretations, prompting a deeper examination of the underlying economic forces at play.
The July Jobs Report: A Tale of Two Metrics
In July, the U.S. economy saw a net loss of 100,000 nonfarm payroll jobs, a figure that defied the consensus expectations of economists who had predicted modest job growth. This decline marks a significant deviation from the generally upward trend observed in recent months, raising concerns about a potential cooling in labor market expansion. However, in a move that further complicated the narrative, the unemployment rate for the same month fell to 3.4%, reaching a new multi-decade low. This simultaneous decrease in job numbers and the unemployment rate suggests a complex interplay of factors, including shifts in labor force participation and variations in how jobs are counted.
The unexpected dip in nonfarm payrolls has been attributed by some analysts to a combination of seasonal factors and a slowing demand for labor in certain sectors. While the headline number paints a picture of contraction, the falling unemployment rate indicates that individuals who may have been previously discouraged from seeking work have re-entered the labor force and found employment. This could also be a reflection of individuals moving between jobs, leading to a temporary dip in the net payroll count even as overall employment opportunities remain robust for those actively seeking work.
Expert Reactions: Navigating the Mixed Signals
The perplexing nature of the July jobs report has elicited a range of responses from financial experts, highlighting the difficulty in formulating a clear outlook.
Kevin Gordon, head of macro research and strategy at the Schwab Center for Financial Research, described the report as "like a hall of mirrors, tricking investors with different signals about whether labor’s recovery is stalling." This analogy underscores the conflicting messages embedded within the data, making it challenging for market participants to discern the true health of the economy.
Aditya Bhave, a U.S. economist at Bank of America, acknowledged the report’s "dovish" implications, suggesting it leans towards a less aggressive stance from the Federal Reserve. However, he maintained his forecast for a 75 basis point interest rate hike later in the year, emphasizing the Fed’s continued focus on inflation. "We agree that the [July] jobs report was a bit dovish on net. But we are sticking with our call that the Fed will hike by 75 [basis points] this year, starting in [September]. The Fed is likely to remain more focused on inflation than labor. The [July] CPI report is a bigger event than today’s jobs numbers," Bhave stated. This perspective suggests that while the labor market data might offer some respite, the persistent challenge of inflation will likely remain the primary driver of monetary policy.
Peter Graf, chief investment officer at Amova Asset Management Americas, offered a more cautious outlook, advising investors to remain vigilant. "Although the stock market is likely to welcome the dovish implications of the report, investors should be wary of the future growth potential of an economy where fewer people are working," Graf commented. His statement raises a critical point: while a less aggressive Fed might be perceived positively by the stock market in the short term, a decline in job creation could signal underlying weaknesses that may impact long-term economic growth.
Background Context: The Evolving Labor Landscape
The July jobs report arrives at a critical juncture for the U.S. economy. Throughout the post-pandemic recovery, the labor market has been a bright spot, characterized by robust job growth and a rapidly declining unemployment rate. This strength has been a key factor in the Federal Reserve’s decision to aggressively raise interest rates in an effort to combat soaring inflation.
In recent months, there have been signs of a potential moderation in the labor market. While job gains have remained positive, the pace of hiring has shown some deceleration. This has led to a debate among economists about whether the labor market is undergoing a soft landing or if a more significant slowdown is on the horizon. The July report, with its contradictory signals, has intensified this debate.
The Federal Reserve, under Chair Jerome Powell, has repeatedly emphasized its commitment to bringing inflation back to its 2% target, even if it means some pain in the labor market. The central bank has been closely monitoring employment data as one of the key indicators of economic health and the effectiveness of its monetary policy. The July report’s mixed signals present a challenge for policymakers, as they attempt to balance the need to curb inflation with the desire to avoid a significant increase in unemployment.
Supporting Data and Historical Trends
To understand the significance of the July figures, it is important to consider them within a broader historical context. Prior to the pandemic, the U.S. unemployment rate hovered around historic lows, a testament to a prolonged period of economic expansion. The rapid rebound in employment following the initial COVID-19 shock was a remarkable feat, but it also contributed to inflationary pressures as demand outstripped supply.
The nonfarm payroll figures are a critical measure of job creation across various sectors of the economy, excluding agricultural workers, private household employees, and non-profit organization employees. A consistent decline in this metric can indicate a weakening economic environment. Conversely, a falling unemployment rate, when accompanied by job growth, typically signals a strengthening labor market. The anomaly in July’s report—a decline in payrolls alongside a falling unemployment rate—suggests that the traditional interpretation of these metrics may need to be nuanced.
For instance, if individuals who previously stopped looking for work are now actively seeking and finding employment, this would contribute to a lower unemployment rate even if the net number of jobs added is not robust. This phenomenon, often referred to as an increase in labor force participation, can be a positive sign of economic confidence. However, if this is occurring against a backdrop of declining overall job creation, it could also signal that the available jobs are not sufficient to absorb a growing pool of job seekers, potentially leading to increased competition for positions.
Broader Impact and Implications
The implications of the July jobs report extend beyond the immediate reactions of investors. The data will undoubtedly influence the Federal Reserve’s upcoming monetary policy decisions. If the Fed interprets the decline in nonfarm payrolls as a sign of significant economic cooling, it might temper its aggressive interest rate hike campaign. However, the persistently low unemployment rate could provide them with the confidence to continue their fight against inflation, believing that the labor market can withstand further tightening.
The stock market’s reaction is also a significant factor. Typically, a weaker jobs report can be viewed positively by the stock market as it might suggest a less hawkish Federal Reserve, potentially leading to lower borrowing costs and increased corporate profits. However, as highlighted by Peter Graf, a declining number of jobs can also be a harbinger of slower economic growth, which could negatively impact corporate earnings in the long run.
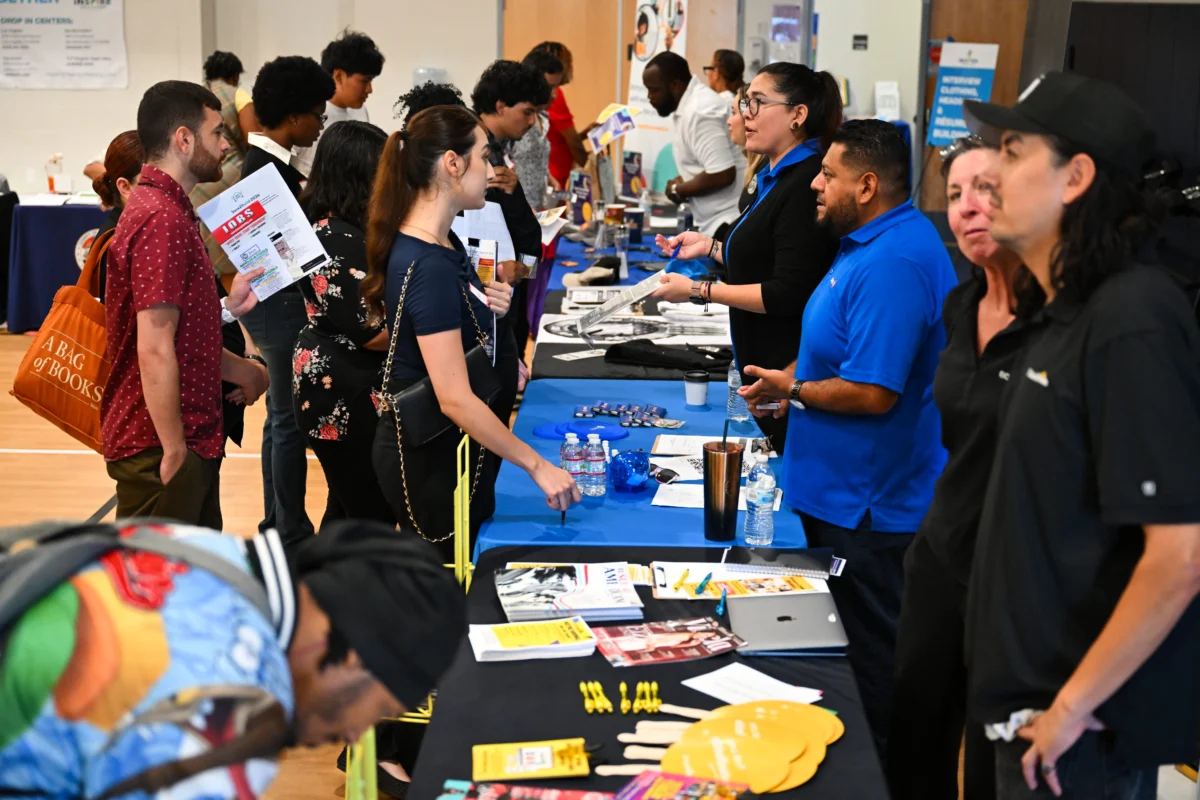
For job seekers, the report presents a mixed bag. While the falling unemployment rate suggests that opportunities are available, the decline in nonfarm payrolls might indicate a more competitive job market. This could lead to longer job search periods and potentially slower wage growth in certain sectors. The Inspire Together job and resource fair, as depicted in the accompanying image from Los Angeles, California on July 29, 2026, serves as a tangible representation of the ongoing efforts to connect job seekers with employers, highlighting the persistent demand for employment services even amidst fluctuating economic indicators. Such events are crucial in navigating the complexities of the labor market, offering resources and direct engagement with potential employers.
Chronology of Recent Economic Events
To fully grasp the context of the July jobs report, a brief chronological overview of recent economic developments is beneficial:
- Early 2022: The Federal Reserve begins a series of aggressive interest rate hikes in response to accelerating inflation.
- Mid-2022: Inflation remains stubbornly high, prompting the Fed to continue its tightening cycle. Signs of a potential slowdown in the housing market and consumer spending begin to emerge.
- Late 2022 – Early 2023: The labor market remains resilient, with consistent job growth and low unemployment, defying some predictions of a recession. However, the pace of job gains begins to moderate.
- Spring/Summer 2023: Economic data presents a complex picture. Inflation shows signs of easing, but remains above the Fed’s target. Concerns about a potential recession persist, while the labor market continues to exhibit strength, albeit with some signs of cooling.
- July 2026 (as per image date): The Inspire Together job and resource fair takes place in Los Angeles, indicating ongoing efforts to facilitate employment.
- July 2026 (reported figures): The U.S. Bureau of Labor Statistics releases the July jobs report, showing a decline in nonfarm payrolls and a fall in the unemployment rate.
This timeline illustrates the dynamic and often unpredictable nature of the current economic environment, where data points can be interpreted in multiple ways, leading to ongoing debate and uncertainty among policymakers and market participants alike. The July jobs report is merely the latest chapter in this complex economic narrative, underscoring the need for careful analysis and a nuanced understanding of the interplay between inflation, employment, and overall economic growth.
