

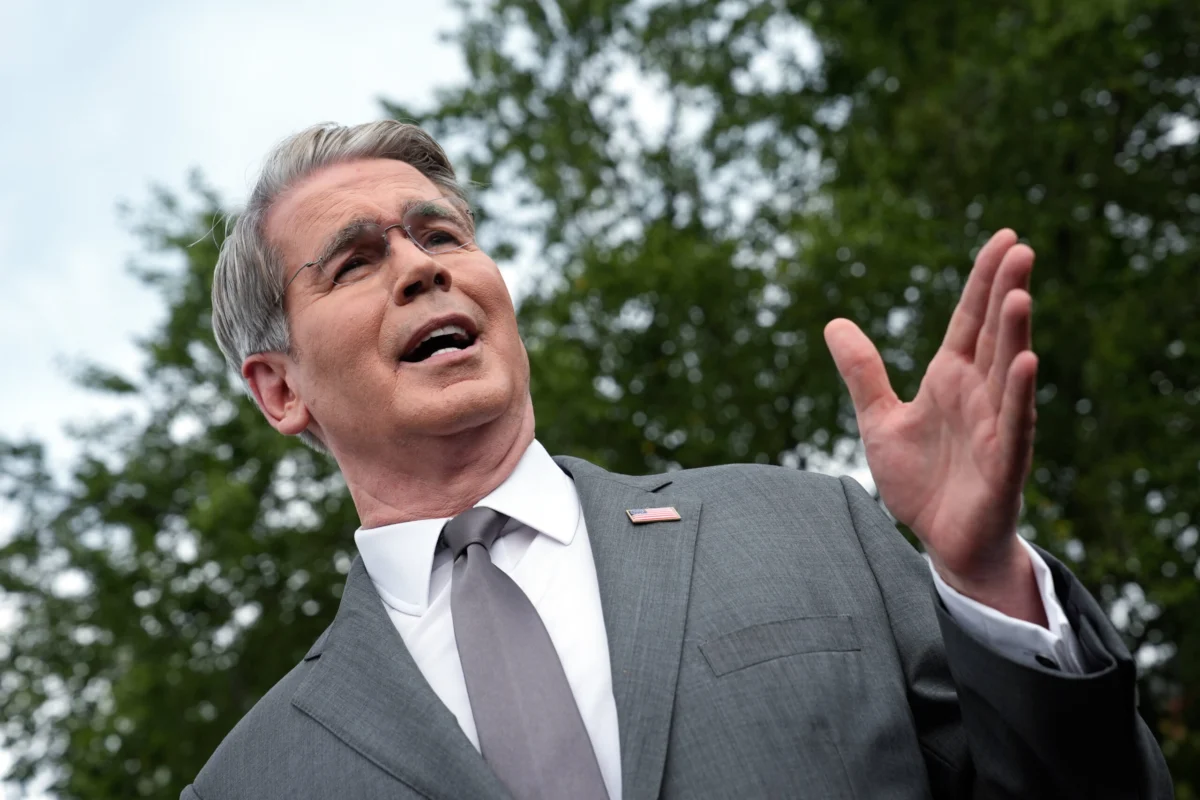
Treasury Secretary Scott Bessent finds himself navigating a complex and increasingly volatile government debt market, grappling with liquidity issues and investor skepticism following recent policy announcements. Despite assurances that a robust arsenal of tools is available to restore calm, the initial efforts to address concerns in the longer-maturity government bond sector have yielded limited and fleeting success, raising questions about the efficacy of the Treasury’s current strategy and the credibility of its guidance.
The Treasury Department’s announcement on Wednesday, August 19, 2026, detailing an intention to at least double its bond buyback operations beginning in early September, initially sent yields on longer-term debt tumbling. Investors, hopeful for a market backstop, applauded the move, viewing it as a potential stabilizing force for government bonds with extended maturities. However, this optimism proved short-lived. By Thursday, August 20, yields at the long end of the curve had begun to edge higher again, as market participants digested the plan and voiced concerns about its potential effectiveness against a backdrop of persistent market pressures.
Adding to the market’s unease, Secretary Bessent appeared on CNBC on Thursday, attempting to assuage fears. He reiterated that the intervention was primarily aimed at providing essential market liquidity rather than directly controlling the yield curve. While yields experienced an initial dip following his remarks, they quickly rebounded. This reaction was exacerbated by criticism regarding the rollout of the prior day’s announcement, with some analysts characterizing Bessent’s television appearance as having "minimal impact" on the underlying market pressures. This sentiment was echoed by market experts who pointed to a disconnect between the Treasury’s stated intentions and the market’s actual response, suggesting that the fundamental factors driving yields higher remained largely unaddressed.
A Deepening Skepticism and the "Weak Form of Operation Twist"
The Treasury’s dual-pronged approach—accelerated buybacks and an effort to persuade the market of the rationale behind its actions—has been met with a degree of skepticism that threatens to undermine its effectiveness. While Secretary Bessent emphasized the breadth of the Treasury’s "big toolkit," including the power of signaling to influence market perceptions about yields not reflecting underlying fundamentals, the market’s reaction suggests a deeper-seated concern.
Criticism has emerged regarding the proposed size of the buybacks. Bessent confirmed that these could exceed $4 billion, a figure that some analysts argue is insufficient to make a significant impact in the vast U.S. Treasury market. Krishna Guha, an analyst at Evercore ISI, described the Treasury’s plan as a "weak form of Operation Twist." This historical Federal Reserve initiative involved swapping longer-term notes and bonds for short-term bills to influence interest rates without expanding the Fed’s balance sheet. Guha posited that the current Treasury initiative "in itself will have little enduring impact and could backfire if it is seen as signaling concern about the ability to fund longer-term at acceptable cost." His assessment of Bessent’s interview further underscored the market’s perception, stating it "had minimal impact on the bond market."

This skepticism raises a critical question for Bessent: with his initial moves failing to decisively calm the markets, what further actions can be deployed, and at what cost? The Treasury secretary is left with several options, each carrying its own set of risks and uncertainties, and the possibility of choosing to do nothing and allowing the market to self-correct remains on the table.
Credibility Under Scrutiny: A Break in Treasury’s Predictability
Beyond the technicalities of market intervention, the Treasury’s recent actions have also placed its credibility under a microscope. The market’s growing skepticism is not solely a reaction to yield movements but also to a perceived deviation from long-established Treasury communication strategies.
Thomas Simons, chief U.S. economist at Jefferies, voiced his concerns, arguing that the buyback announcement was "improper." He highlighted that this decision came just two weeks after the Treasury had outlined its quarterly refunding plans, during which no indication was given of any impending changes to the buyback scheme. Simons wrote, "This breaks with Treasury’s long-held strategy of making ‘regular and predictable’ announcements, and using the Refunding to announce almost all of their policy changes and guidance." He further stated, "We do not think it is hyperbole to say that this break in communication strategy reduces the overall credibility of their guidance."
Adding to this critique, Simons pointed out that "the sloppy wording of [the] headline on [the] release gave the impression that this was a hastily made decision." This perception of impulsiveness can be detrimental in financial markets, where predictability and clear communication are paramount. The challenge for Bessent, therefore, extends beyond managing yields; it involves rebuilding trust and demonstrating a consistent and reliable approach to market management. The very efforts to suppress longer-end yields could, paradoxically, incentivize investors to demand even greater compensation for holding Treasury debt, if they perceive these actions as a sign of underlying instability.
A Confluence of Factors Pressuring Treasury Markets
The pressures on the Treasury market are not solely a product of recent policy missteps or Treasury actions. A confluence of interconnected factors is creating a challenging environment for government debt. As Bessent articulated on CNBC, these pressures extend beyond purely fundamental economic indicators.

Key Factors at Play:
- Corporate Bond Issuance: A surge in corporate bond issuance presents a competing investment opportunity for capital that might otherwise flow into Treasurys. Companies are actively tapping the debt markets, offering attractive yields to fund operations and expansion.
- Attractive Sovereign Yields Elsewhere: The yields offered by other sovereign nations, particularly Japan, have become increasingly competitive. This can draw international investment away from U.S. Treasurys, especially if U.S. yields are perceived as not adequately compensating for risk.
- Correlation with Oil Prices and Inflation Fears: The correlation between oil prices and inflation fears remains a significant concern. Rising energy costs can fuel broader inflationary pressures, prompting investors to demand higher yields on bonds to protect their purchasing power.
- Increasing Term Premiums: Investors are demanding higher "term premiums" – the additional yield they require for holding longer-dated debt compared to rolling over short-term instruments. This reflects a greater aversion to holding long-term assets in an uncertain economic and interest rate environment.
- Structural Shifts in Demand: Atsi Sheth, chief credit officer at Moody’s Ratings, highlights a fundamental shift in the buyer base for U.S. government debt. As central banks globally reduce their balance sheets and traditional long-duration buyers reach their absorption limits, new players like leveraged hedge funds employing relative-value strategies are becoming more prominent. These newer participants may have different risk appetites and trading strategies, contributing to market volatility.
The Looming Fiscal Storm
Compounding these market dynamics is the increasingly precarious fiscal situation of the United States. The nation faces a significant deficit-to-GDP ratio, standing at nearly 6% in August 2026, a figure approximately triple the average observed from the end of World War II until the COVID-19 pandemic. This widening deficit is exacerbating the challenge posed by the national debt, which has recently surpassed the $40 trillion mark for the first time.
The political landscape further complicates the outlook. With President Donald Trump advocating for further tax cuts and Congress showing little inclination towards fiscal restraint, the trajectory points towards continued increases in government borrowing. In response to these fiscal challenges, Bessent indicated that he and Russell Vought, head of the Office of Management and Budget, are scheduled to meet soon to discuss "fiscal consolidation"—a term generally understood to encompass strategies for reducing government deficits and debt.
JoAnne Bianco, senior investment strategist at BondBloxx, encapsulated the market’s concerns: "It’s that combination of the deficits, the borrowing needs, inflation expectations, not really knowing what future Fed policy is going to be, and the sustainability of being able to issue higher, ever higher, levels of U.S. Treasury debt, and what rates those need to be at." She concluded that "there’s just the idea that there needs to be a higher risk premium for all the issuance." This sentiment suggests that the market is pricing in a structural increase in the cost of U.S. government borrowing due to these mounting fiscal pressures.
Potential Avenues for Bessent: Collaboration and Policy Levers
Faced with this complex web of market pressures and fiscal challenges, Secretary Bessent has several potential avenues to explore. One significant option is to seek enhanced cooperation with the Federal Reserve. While Federal Reserve Chairman Kevin Warsh has consistently emphasized the importance of allowing market forces to dictate interest rates, Bessent hinted at the possibility of collaboration. He suggested that the Treasury and the Fed "would work together" in addressing complications in the bond markets, particularly as the central bank manages its own holdings of Treasury securities. Such coordination could involve more direct interventions or policy adjustments that aim to stabilize the market without overtly manipulating yields.

Another potential, albeit more controversial, path could involve a more assertive form of market intervention. While the current buyback program is seen as insufficient, the Treasury could consider significantly scaling up these operations or exploring other mechanisms. However, any such action would need to be carefully calibrated to avoid further eroding market confidence or triggering unintended consequences.
The Treasury could also consider adjustments to its issuance strategy. This might involve altering the maturity profile of newly issued debt or implementing more innovative financing techniques. However, such changes would likely require extensive consultation and market signaling to ensure smooth adoption.
The Road Ahead: Uncertainty and the Need for a Coherent Strategy
The current situation in the government debt market is a symptom of broader economic and fiscal challenges. Secretary Bessent’s assurance of having multiple weapons at his disposal is accurate, but the effectiveness of these weapons hinges on their judicious deployment and the market’s perception of their credibility. The recent communication missteps and the perceived inadequacy of the initial buyback expansion have created an environment where skepticism is the prevailing sentiment.
The coming weeks and months will be critical for Bessent and the Treasury Department. Restoring market confidence will require not only decisive action but also a clear, consistent, and credible communication strategy. The underlying fiscal imbalances, coupled with evolving global economic conditions, mean that the Treasury will likely face continued pressure. The ability of Secretary Bessent to navigate these challenges, restore stability to the bond market, and address the nation’s fiscal trajectory will be a defining test of his tenure. The market is watching, and its patience for further missteps appears to be wearing thin.
