

The International Sustainability Standards Board is currently consolidating its position as the primary architect of a global baseline for corporate sustainability disclosures, marking a pivotal shift in how the private sector communicates environmental, social, and governance risks to the global financial markets. Since its inception at the COP26 climate summit in Glasgow, the ISSB has moved with unprecedented speed to harmonize a fragmented landscape of reporting frameworks, aiming to provide investors with the same level of rigor and comparability in sustainability data as they have long enjoyed in traditional financial accounting. As of late 2024, the momentum behind this initiative has reached a critical mass, with nearly 50 jurisdictions—representing approximately 60 percent of global gross domestic product—taking concrete steps to incorporate these standards into their national regulatory architectures.
The Genesis of a Global Baseline
For decades, the corporate world operated within what many analysts described as an "alphabet soup" of voluntary reporting frameworks. Organizations such as the Global Reporting Initiative (GRI), the Sustainability Accounting Standards Board (SASB), and the Task Force on Climate-related Financial Disclosures (TCFD) all offered valuable but often overlapping or divergent methodologies for measuring non-financial performance. This fragmentation created a significant burden for multinational corporations, which were often forced to report under multiple regimes, and left investors struggling to compare the sustainability profiles of companies across different regions.
The formation of the ISSB by the International Financial Reporting Standards (IFRS) Foundation was a direct response to this inefficiency. By leveraging the institutional credibility of the IFRS—the body responsible for the accounting standards used in over 140 jurisdictions—the ISSB sought to create a "neutral" technical standard. Under the leadership of Chair Emmanuel Faber, the former CEO of Danone, the board released its first two finalized standards in June 2023: IFRS S1, which covers general requirements for disclosure of sustainability-related financial information, and IFRS S2, which focuses specifically on climate-related disclosures.
A Chronology of Rapid Integration
The timeline of the ISSB’s influence demonstrates a rare instance of global regulatory alignment occurring in less than three years. Following the 2021 announcement at COP26, the board spent 2022 and early 2023 in intensive consultation with stakeholders, including institutional investors, regulators, and corporate leaders.
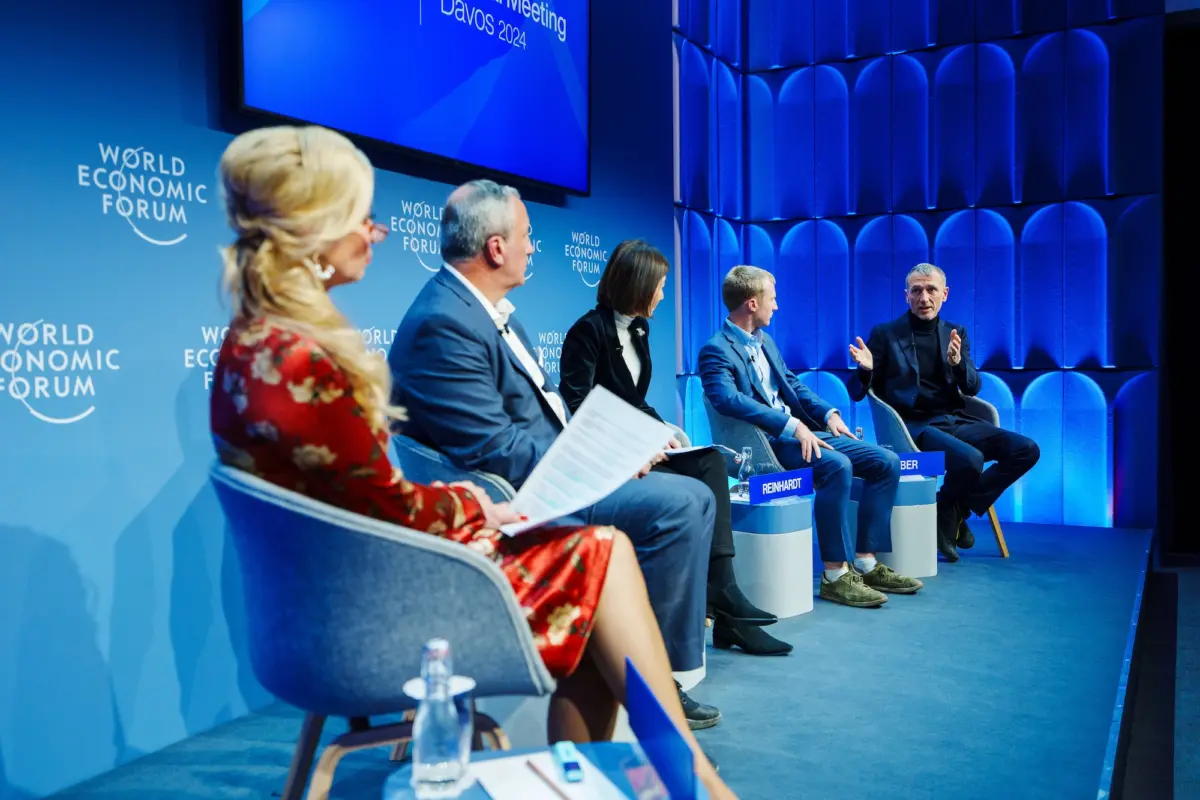
By June 2023, the publication of IFRS S1 and S2 provided the starting gun for national governments. By early 2024, at the World Economic Forum in Davos, Emmanuel Faber was able to report that the standards were no longer theoretical but were being actively integrated into law. Throughout 2024, major economies including Australia, Singapore, and the United Kingdom began formalizing their adoption paths. Looking ahead to 2025 and 2026, the focus is expected to shift toward the first waves of mandatory reporting and the expansion of the standards to cover broader topics such as biodiversity and human capital.
The Strategy of Adoption by Stealth
One of the most notable aspects of the ISSB’s success has been its ability to navigate the highly polarized political landscape of ESG (Environmental, Social, and Governance) reporting. In the United States, sustainability reporting has become a flashpoint for political debate, leading to legal challenges against the Securities and Exchange Commission’s (SEC) climate disclosure rules. Conversely, the European Union has moved toward a highly ambitious and prescriptive model via the Corporate Sustainability Reporting Directive (CSRD).
The ISSB has positioned itself as the "pragmatic middle ground." Because it is an independent, technical body rather than a political entity, many nations have found it easier to endorse ISSB standards as a matter of financial transparency rather than a political statement on climate change. This "adoption by stealth" allows countries in the Middle East, Africa, and Southeast Asia to elevate their local reporting requirements to international standards without appearing to favor any specific regional agenda. This neutrality is particularly attractive to emerging markets that wish to attract global institutional capital by proving they meet international transparency benchmarks.
Regional Variations: The "Comply or Explain" Reality
While the goal is a unified global baseline, the reality of implementation is characterized by regional nuances and "cherry-picking" of specific provisions. The ISSB framework includes "transition relief" measures, such as allowing companies to report on their direct Scope 1 and Scope 2 emissions in the first year before expanding to the more complex Scope 3 value-chain emissions in the second year. However, different jurisdictions are applying these reliefs differently.
In the United Kingdom, the Financial Conduct Authority (FCA) has taken a rigorous stance, indicating that the ISSB framework will replace existing climate-based rules on a "comply or explain" basis. Notably, the U.K. has stripped out some of the voluntary transition reliefs to ensure a faster pace of adoption for listed companies. Australia, by contrast, has mirrored the core framework but removed references to certain industry-specific metrics, tailoring the requirements to its domestic economic profile.
In Latin America, Brazil was an early mover, though it recently adjusted its timeline, moving from a mandatory 2026 start to a "comply or explain" model while still emphasizing the importance of independent third-party assurance. Mexico has kept the standards largely unaltered but added a requirement for external review, a step that goes beyond the core ISSB mandate but reflects a local desire for high-quality data verification.

The Materiality Divide: Financial vs. Double Materiality
A significant point of divergence in the global landscape remains the definition of "materiality." The ISSB standards are rooted in "financial materiality," focusing on how sustainability issues affect a company’s financial performance, cash flows, and valuation. This approach is designed specifically to meet the needs of investors and capital providers.
In contrast, the European Union’s CSRD utilizes "double materiality," which requires companies to report not only on how sustainability issues affect the company (outside-in) but also on how the company’s activities impact society and the environment (inside-out).
The most interesting test case for bridging this gap is China. Beijing has recently deviated from the core ISSB framework by favoring double materiality. This move signals that China intends to use sustainability reporting as a tool for broader social and ecological governance, rather than just financial risk management. How the ISSB reconciles its investor-focused baseline with the impact-focused requirements of China and the EU will be the defining challenge of the next five years. Proponents of the ISSB argue that over time, impacts on the planet inevitably become financial risks, suggesting that the two definitions of materiality may eventually converge.
Supporting Data and Economic Implications
The economic weight behind the ISSB is substantial. Jurisdictions that have committed to or are considering the standards account for over half of the world’s GDP and nearly 40 percent of global market capitalization. For multinational corporations, the stakes are high. A study of large-cap firms suggests that those with high-quality ESG disclosures often see a lower cost of capital, as investors perceive them to have better-managed long-term risks.
Furthermore, the demand for Scope 3 emissions data—which covers everything from a company’s supply chain to the end-use of its products—is driving a massive data collection effort. Estimates suggest that for many sectors, such as automotive or apparel, Scope 3 emissions account for more than 80 percent of a company’s total carbon footprint. The ISSB’s insistence on eventually including this data represents a major step toward total transparency in global supply chains.
Future Horizons: Biodiversity and the "Global Passport"
The ISSB is not resting on its initial climate-focused achievements. The board is currently developing a practice statement for biodiversity, ecosystems, and ecosystem services. This work is being modeled closely on the Taskforce for Nature-related Financial Disclosures (TNFD) framework, with a draft expected to be released imminently. By expanding into nature-related risks, the ISSB is acknowledging that climate change is only one facet of environmental risk facing the global economy.
Additionally, the board is working on a "global passport" initiative. This program aims to work with national regulators to understand why they are adapting or altering the standards. The goal is to iron out these regional variations so that a sustainability report produced in Nigeria or Singapore is instantly recognizable and comparable to one produced in London or Tokyo. To support this, the ISSB expanded its Jurisdictional Working Group in 2025 to include a wider array of developing nations.
Analysis of Broader Impacts
The move toward standardized reporting represents more than just a change in accounting; it is a fundamental shift in the "social contract" of the corporation. By mandating that sustainability risks be reported with the same discipline as financial data, the ISSB is effectively elevating environmental and social considerations to the boardroom level. Chief Financial Officers (CFOs) are now increasingly responsible for sustainability data, a task previously relegated to specialized CSR departments.
However, challenges remain. The risk of "greenwashing" persists if assurance standards—the rules for how data is audited—do not keep pace with reporting standards. Moreover, the cost of compliance for smaller companies in emerging markets could be prohibitive, potentially creating a two-tier system where only the largest, best-resourced firms can meet the "global baseline."
Despite these hurdles, the trajectory is clear. The era of voluntary, disparate sustainability reporting is ending. As the ISSB continues to expand its reach and refine its standards, the global financial system is moving toward a future where "performance" is measured not just in dollars and cents, but in carbon, water, and social impact. For the global business community, the message is unambiguous: transparency is no longer optional, and the baseline is now set.
