

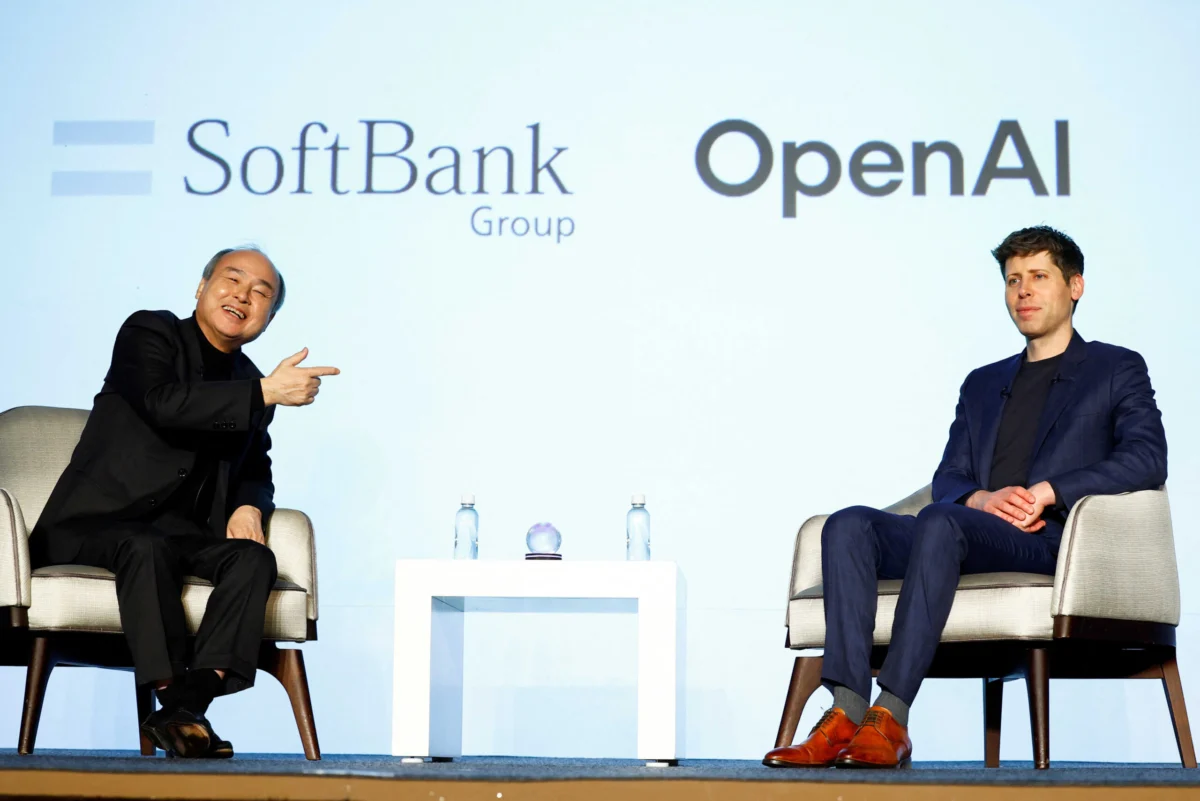
Silicon Valley luminaries, including Elon Musk and OpenAI CEO Sam Altman, have long championed the deflationary potential of the artificial intelligence revolution. Altman, in a recent blog post, articulated this vision, stating, "Intelligence too cheap to meter is well within grasp." Musk, the CEO of Tesla and SpaceX and the world’s wealthiest individual, has echoed this sentiment, predicting that AI and robotics will usher in an era of extreme abundance, thereby driving down costs. Similarly, SoftBank’s Masayoshi Son had previously projected a significant 40% drop in prices, envisioning a future where arduous manual labor would become obsolete.
However, these optimistic forecasts appear to be diverging from current economic realities. Instead of immediate cost reductions, the widespread integration of AI into the economy is encountering significant corporate inertia. This friction is, in some instances, contributing to near-term inflationary pressures and offering scant evidence of a sustained, broad-based productivity surge.
The pace of AI adoption across industries has proven to be more measured than many of its early proponents had anticipated. Concurrently, the technology sector’s multi-trillion-dollar investment in data centers and AI infrastructure has begun to strain global supply chains. The significant expenditure required for AI development and deployment is, paradoxically, driving up prices in critical sectors, such as electricity. These mounting costs are materializing before the full-scale economic benefits of AI are realized, presenting a complex challenge for policymakers at the Federal Reserve as they navigate inflation management.
Ronnie Chatterji, chief economist at OpenAI, acknowledges that the immediate costs associated with AI implementation are more readily quantifiable than its potential long-term benefits. "For it to impact the economy, it has to be adopted by organizations," Chatterji stated. "Those organizations have to realize value." He further conceded that "it’ll still be a little while before we see it sort of clearly for productivity statistics," indicating that a discernible impact on economic output metrics will likely take time.

The economic implications of the AI build-out are substantial. Goldman Sachs Research estimates that capital expenditure on AI infrastructure in the United States alone will reach $581 billion in the current year, with global spending potentially hitting $1 trillion. In the U.S., this investment represents approximately 1.8% of the nation’s gross domestic product, a figure the firm projects could climb to 2.8% by 2028.
Empirical data on AI adoption within businesses, however, presents a more nuanced picture. A survey conducted by the Census Bureau in May revealed that between 17% and 20% of U.S. businesses reported utilizing AI technologies. This adoption rate is notably higher among larger enterprises compared to small and medium-sized businesses.
Peter Boockvar, chief investment officer at OnePoint BFG Wealth Partners, draws a parallel between the current AI boom and the transformative impact of the internet. He points out that even during the internet’s widespread adoption, which spurred significant automation, the U.S. experienced only a 1.5% increase in productivity over a 30-year period. When viewed over a 50-year horizon, average productivity growth was around 2.5%. "To think that generative AI is going to bring that level of enhancement to the economy, relative to the internet, is tough," Boockvar remarked. "Technology has always made people more productive. But is generative AI multiple step functions higher? We just don’t know."
The Reality of AI Implementation: Beyond the Hype
Within the corporate world, executives who have begun integrating AI into their operations are tempering the industry’s more ambitious claims. Julie Averill, former chief information officer at Lululemon, where she spearheaded AI adoption, observed, "The reality is that the technology is there. The hype is around the ease of the technology in a large organization." Lululemon, for instance, employed AI to enhance product sales forecasting, a process that proved to be significantly more complex than a simple chatbot application.
Averill elaborated on the persistent challenges within large organizations: "The things that have always made implementations in large companies difficult still exist, which is people. Getting people to change their behaviors, taking them along the journey with you, and getting them to trust the model, that’s hard."

Chatterji’s observations from OpenAI’s internal data corroborate these findings. He noted that power users of AI technologies deploy them at an eightfold rate compared to average companies, measured by tokens per user. This disparity has widened significantly since OpenAI’s last report on the matter three months prior. "It is growing incredibly fast in terms of the gap between the frontier firms and the typical firms," Chatterji said. "The companies that are reorganizing their workflows around it and changing the way they work around AI, they’re having more success."
Economists studying the impact of AI have identified a concept known as "weak links" to explain these implementation hurdles. Weak links refer to tasks within a job that are not easily automated. AI can enhance productivity by automating specific functions, such as the interpretation of radiological scans, a task at which AI excels. However, as Stanford professor Charles Jones, a leading scholar on AI’s economic impact and currently on leave at Anthropic, explains, jobs are multifaceted, comprising a mix of tasks, some more amenable to automation than others.
Geoffrey Hinton, a Nobel laureate technologist, had predicted in 2016 that radiologists would be largely obsolete within a decade. Contrary to this forecast, the number of radiologists has continued to grow, partly because AI has augmented their capabilities and made them more valuable. "It turns out that radiologists do more than just read scans, and AI tools complement those other skills by automating a fraction of the tasks that radiologists perform," Jones wrote. Tasks such as patient communication and interdisciplinary collaboration represent these "weak links" that are more resistant to automation. The full extent of these weak links will only become apparent as AI adoption scales across a wider array of industries and job functions.
The Federal Reserve’s AI Conundrum
The complexities of AI’s economic impact have not escaped the attention of policymakers. Last month, Federal Reserve Chairman Jerome Powell appointed Charles Jones to a task force dedicated to informing the central bank’s understanding of AI’s influence on the economy. Marc Andreessen, a prominent venture capitalist with significant investments in AI startups and a proponent of an "hyper-deflationary" future, is also a member of this influential group.
When Jones, Andreessen, and their fellow task force members present their findings in the coming months, their insights will contribute to an ongoing, vigorous debate within the Federal Reserve regarding AI’s role in the economic landscape. As early as November, former Fed Chairman Kevin Warsh—who was confirmed to his position later—argued in an opinion piece that the Fed would need to revise its growth forecasts to incorporate the impact of AI. He posited that "AI will be a significant disinflationary force, increasing productivity and bolstering American competitiveness," a perspective that aligned with then-President Donald Trump’s calls for lower interest rates.

However, not all Fed officials share this optimistic outlook. In July, the Federal Open Market Committee (FOMC) voted to maintain its benchmark interest rate in the range of 3.5% to 3.75%. This decision was not unanimous, with some officials expressing concerns that a more restrictive monetary policy might be necessary to counteract potential AI-driven price increases.
Minneapolis Fed President Neel Kashkari articulated this concern in a statement explaining his dissenting vote in favor of a higher interest rate. He pointed to "the massive investment in data centers [that] has also added a new demand element to the high inflation Americans are experiencing."
The burgeoning demand for electricity-intensive data centers is a tangible factor contributing to rising utility costs for households. Data from the Bureau of Labor Statistics indicates that household electricity prices saw a 10% increase in the two years preceding July, outpacing the overall 6.2% rise in prices across the economy during the same period.
Furthermore, other Fed officials have highlighted supply chain bottlenecks for the specialized servers essential for advanced AI models. AI companies are aggressively procuring high-end chips from manufacturers like Nvidia, but chipmakers have struggled to ramp up production sufficiently to meet this surge in demand. This scarcity has led to significant price increases for critical components. JPMorgan Chase estimates that the cost of dynamic random-access memory (DRAM) could rise by as much as 400% by the end of the year compared to 2024 levels. Consumer Price Index (CPI) data also reveals a substantial 22.4% increase in the cost of computer software and accessories since July 2024.
The evolving economic landscape has prompted a more cautious stance from Chairman Powell. While acknowledging in July that companies’ substantial AI investments are laying the groundwork for future economic expansion, he conceded that "the precise timing and magnitude of effects on the supply side remain hard to predict."

Peter Boockvar summarized the predicament: "The cost and inflationary aspect is really complicating Kevin Warsh’s job. He wants to believe in the productivity enhancements down the road – but it’s not something he can react to." This sentiment underscores the central challenge: while AI holds immense promise for long-term productivity gains and potential deflationary effects, its immediate economic consequences, particularly concerning inflation, are proving to be complex and difficult to manage. The anticipated benefits of AI may eventually materialize, but the current costs are undeniably real and are actively shaping the Federal Reserve’s policy decisions.
Reporting contributed by CNBC’s Drew Troast.
WATCH: Former Trump adviser Joe Lavorgna stated that the Federal Reserve will need to raise interest rates to combat inflation.
