

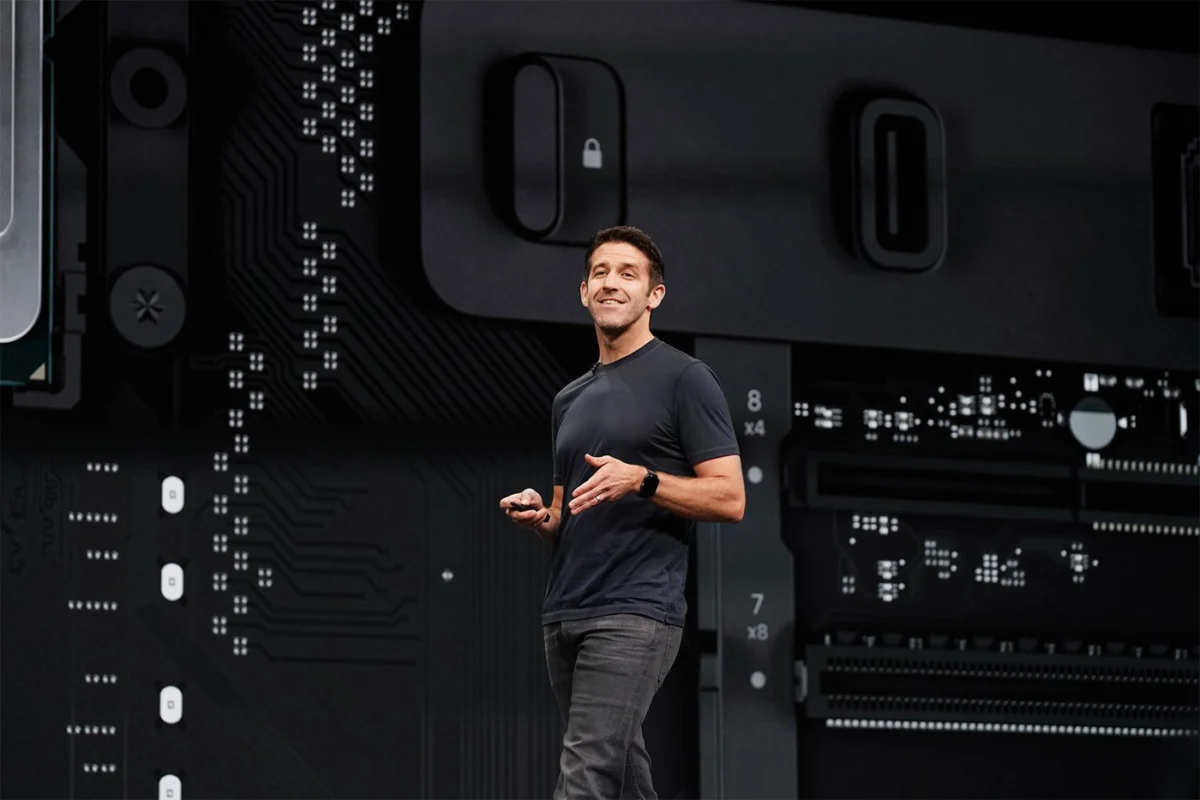
In a pivotal moment for the technology giant, John Ternus, making his debut as Apple’s Chief Executive Officer, presided over his inaugural iPhone event on Saturday, September 19, 2026, at 5:50 AM PDT. The highly anticipated keynote introduced the latest iterations of Apple’s flagship smartphones, the iPhone 18 Pro and iPhone 18 Pro Max, alongside a groundbreaking new product: the company’s first-ever foldable device, the iPhone Duo. This launch signifies a strategic push into new form factors and a continued evolution of Apple’s premium smartphone offerings, all while navigating a complex economic landscape marked by rising component costs.
Immediately following the product unveilings, financial markets and analysts began to dissect the implications of the new lineup and their pricing strategy. Wamsi Mohan, a respected analyst at Bank of America, reiterated his "buy" rating for Apple (NASDAQ: AAPL) stock, signaling continued confidence in the company’s long-term prospects. However, in a notable adjustment that caught the attention of investors, Mohan simultaneously lowered his price target for Apple shares to $370, down from a previous estimate of $380. This subtle but significant recalibration underscores the delicate balance Apple faces in maintaining profitability amidst a challenging supply chain environment, particularly concerning memory costs.
A New Chapter Under John Ternus: Innovation and Evolution
The September 19th event marked a significant milestone, not just for the product line, but for Apple’s leadership. John Ternus, a long-time veteran of Apple’s product development and a key figure in hardware engineering, assumed the CEO role earlier this year. His first iPhone event was closely watched, offering insights into his strategic vision and leadership style. The presentation, delivered with Apple’s characteristic blend of polished design and technical prowess, highlighted advancements across the new iPhone 18 series.
The iPhone 18 Pro and Pro Max are expected to feature enhanced camera systems, next-generation processors offering significant performance gains, and improvements in battery life and display technology, building upon the established legacy of the ‘Pro’ moniker. While specific technical details were meticulously presented, the broader narrative centered on refinement and incremental innovation designed to appeal to Apple’s loyal user base and attract new customers.
However, the spotlight was undeniably shared with the iPhone Duo. Apple’s entry into the foldable smartphone market has been rumored for years, and its official unveiling represents a significant strategic move. The iPhone Duo, with its innovative folding mechanism and larger, flexible display, positions Apple directly in a nascent but growing premium segment. This device is not merely an incremental upgrade but a bold step into a new product category, signaling Apple’s intent to lead in form factor innovation as well as traditional smartphone design.
Analyst Scrutiny: Price Targets and Profit Margins
Wamsi Mohan’s analysis, while affirming a bullish stance on Apple’s stock, provided a critical lens through which to view the new product launches. His decision to trim the price target by $10, from $380 to $370, was primarily attributed to the pricing strategy of the new iPhone 18 Pro and Pro Max models. While these devices saw a $100 increase over their predecessors – with the iPhone 18 Pro starting at $1,199 and the Pro Max at $1,299 – this increase was apparently lower than Mohan’s internal expectations for Apple’s ability to pass on rising component costs to consumers.
Mohan’s concern stems from the interplay between sales volume and profit margins. A lower-than-expected price point, even with an increase, could lead to higher unit sales, but potentially at the expense of thinner profit margins per device. In an environment where Apple is grappling with escalating supply chain costs, particularly for memory components, this trade-off becomes a crucial factor for investor sentiment. The analyst’s report suggested that while the new iPhones are poised to be a commercial success, the pricing structure indicates Apple’s strategic choice to absorb some of the cost increases, thereby protecting market share and customer affordability, but also impacting short-term profitability metrics.
The Rising Tide of Memory Costs and Its Impact on Hardware
The backdrop to Apple’s pricing dilemma is a global semiconductor market characterized by significant volatility, especially in memory components. The demand for advanced memory processors, such as DRAM and NAND flash, has surged dramatically in recent years, driven primarily by the explosive growth of artificial intelligence (AI) applications and the expansion of data centers worldwide. These data centers, requiring vast quantities of high-performance memory for AI training and inference, have created unprecedented demand, pushing prices upward across the board.
Apple, as one of the world’s largest consumers of memory chips for its iPhones, Macs, and other devices, is directly exposed to these market dynamics. The company had already responded to these pressures earlier in the year by raising prices on its Mac lineup, indicating a clear strategy to offset rising input costs. The $100 price increase for the iPhone 18 Pro and Pro Max models is a direct reflection of Apple’s ongoing efforts to mitigate the impact of these elevated memory prices on its balance sheet.
However, as Mohan’s analysis highlights, this is a delicate balancing act. Apple must weigh the necessity of increasing prices to maintain margins against the potential risk of alienating price-sensitive consumers or losing competitive ground. The company’s management has already provided guidance on gross margins for the upcoming fourth quarter, projecting figures between 47% and 48%. This represents a noticeable contraction from the 50% gross margin reported in the third quarter, underscoring the immediate financial pressure exerted by higher component costs and the chosen pricing strategy.
The Foldable Frontier: A Potential Margin Rebound?
While the immediate outlook points to some margin compression, the introduction of the iPhone Duo introduces a new dimension to Apple’s profitability strategy. The iPhone Duo, priced at a premium starting at $1,999, enters a high-end niche within the smartphone market. This significantly higher price point could serve as a crucial lever for boosting Apple’s overall iPhone segment margins in the longer term.
Gene Munster, the founder of Deepwater Asset Management and a veteran Apple analyst known for his astute market observations, posited an interesting scenario. Munster projects that a substantial portion – potentially up to one-third – of current iPhone Pro Max owners might opt to upgrade to the new iPhone Duo. If this migration pattern materializes, he believes the iPhone Duo could contribute as much as 10% of total iPhone revenue by 2027. Given its elevated price, a strong performance by the Duo could indeed provide a significant uplift to Apple’s blended iPhone margins, offsetting some of the pressures from the more traditionally priced Pro models.
The foldable market itself is still nascent but gaining traction. Competitors like Samsung have been active in this space for several years, refining their designs and expanding their foldable device portfolios. Apple’s entry, often seen as a validation of a technology’s maturity and market potential, is likely to catalyze further innovation and consumer adoption in the foldable segment. The iPhone Duo’s success will depend not only on its innovative hardware but also on the seamless integration of its flexible display into Apple’s ecosystem, particularly through software optimizations that leverage the unique form factor.
Apple’s Distinctive AI Strategy: A Prudent Path?
Beyond the immediate product cycle and margin discussions, the article touches upon Apple’s broader strategic positioning, particularly concerning artificial intelligence. In an era where many major tech companies are engaging in an intense arms race of AI investment, ramping up spending on R&D, infrastructure, and talent, Apple has seemingly adopted a more measured and focused approach. The company is not perceived as "ramping up spending" on AI in the same overt and aggressive manner as some of its peers.
At first glance, this might appear to be a drawback, suggesting Apple is falling behind in a critical technological frontier. However, the analysis suggests this differentiated strategy could, in fact, be working to Apple’s advantage. By avoiding the massive, often speculative, capital expenditures seen elsewhere in the AI sector, Apple may be preserving its strong profitability and financial flexibility. Its AI strategy appears to be more integrated and product-focused, embedding AI capabilities directly into its devices and services (e.g., Siri, camera features, on-device processing) rather than pursuing a broad, platform-centric AI play.
This approach aligns with Apple’s historical pattern of entering markets once they are more mature, bringing a polished, user-centric product rather than being the first to market. While rivals pour billions into foundational AI models and cloud-based AI infrastructure, Apple focuses on practical, privacy-preserving AI that enhances the user experience directly on its devices. This strategy allows the company to benefit from AI’s advancements without incurring the same level of upfront risk and investment, contributing to its sustained high margins and robust financial health.
Broader Implications and Long-Term Outlook
The launch of the iPhone 18 series and the iPhone Duo, coupled with the nuanced analyst reactions, paints a picture of Apple at a critical juncture. The company is successfully innovating, expanding its product portfolio into new and exciting categories, and maintaining its premium brand image. However, it is also operating within a complex global economic environment where supply chain costs are a persistent challenge.
Apple’s ability to balance these factors – delivering cutting-edge technology, maintaining attractive pricing, and preserving its industry-leading profit margins – will be key to its continued success. The strategic pricing of the iPhone 18 Pro and Pro Max suggests a careful calibration to maintain sales volume while still acknowledging increased costs. The iPhone Duo, meanwhile, represents a high-potential venture that could significantly contribute to future revenue growth and margin expansion, cementing Apple’s position in the ultra-premium segment.
From an investment perspective, despite the slight reduction in price target, the continued "buy" rating from Bank of America analyst Wamsi Mohan underscores a broader confidence in Apple’s fundamental strengths. These strengths include its unparalleled brand loyalty, vast ecosystem of hardware and services, robust financial position, and a proven track record of innovation. The long-term outlook for Apple remains positive, driven by its ability to evolve its product lines, penetrate new markets like foldables, and strategically integrate technologies like AI in a manner that enhances user value and sustains profitability. Investors will be closely watching the upcoming earnings reports for insights into how these new products perform and how Apple’s margin story unfolds in the coming quarters.
