

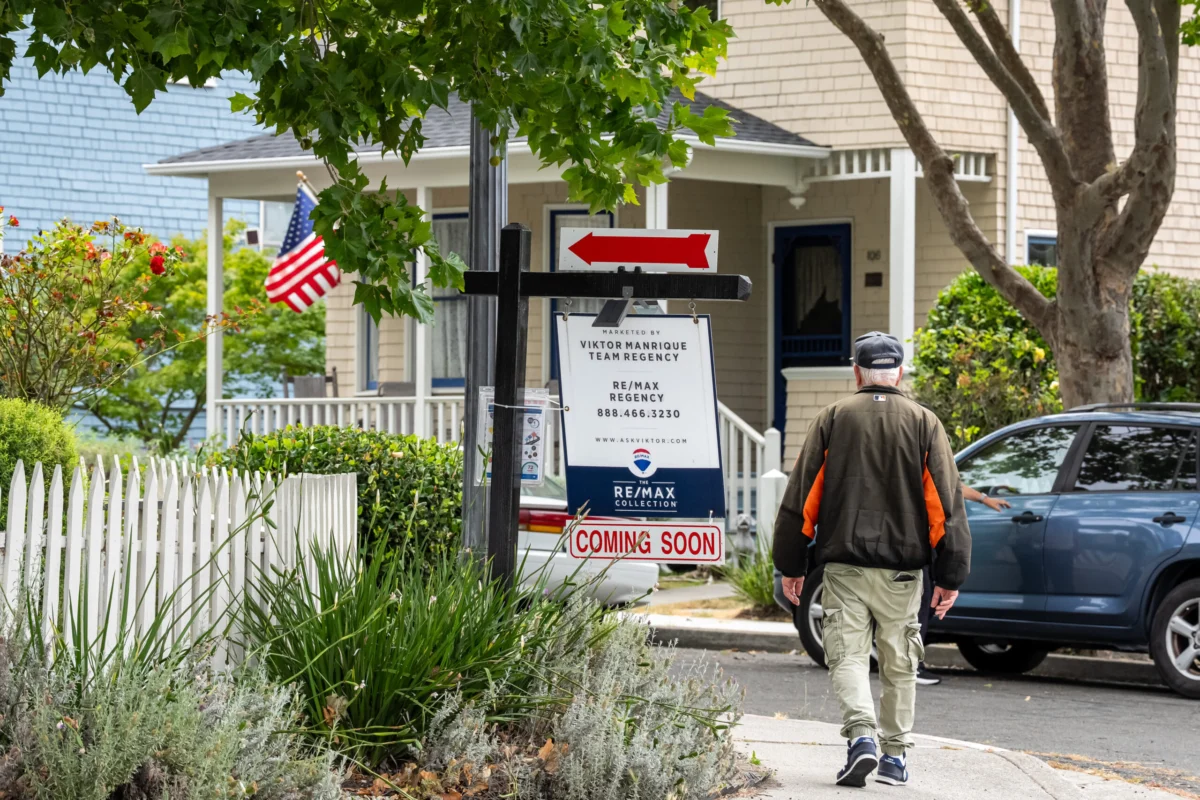
The United States housing market witnessed a complex interplay of forces in mid-2026, as mortgage rates escalated for another week, yet surprisingly, homebuyers re-entered the arena, driving total mortgage demand up by 1.9% compared to the previous week. This unexpected resilience in demand, as reported by the Mortgage Bankers Association’s (MBA) seasonally adjusted index, suggests a market grappling with rising borrowing costs but simultaneously adapting to shifting competitive landscapes and emerging opportunities for price negotiation. The increase in purchase applications signals a potential strategic pivot by buyers, who appear to be capitalizing on a cooling competitive environment and an increasing willingness from sellers to adjust prices, even as the cost of financing continues its upward trajectory, influenced by a volatile global economic and geopolitical backdrop.
The Mortgage Rate Landscape: A Detailed View
The average contract interest rate for 30-year fixed-rate mortgages, particularly those with conforming loan balances of $832,750 or less, climbed to 6.69% from 6.65%. This marks a significant benchmark, as it represents the highest rate observed since August 2025, underscoring a persistent upward trend in borrowing costs that has been a defining feature of the market since early 2022. Concurrently, points, which represent an upfront fee paid to the lender in exchange for a lower interest rate, saw a slight decrease to 0.62 from 0.67, including the origination fee, for loans structured with a 20% down payment. This minor reduction in points could offer a marginal reprieve to some borrowers, slightly offsetting the rise in the headline interest rate, yet the overall cost of homeownership remains a critical consideration in an environment where affordability is increasingly strained.
The movement in mortgage rates is inextricably linked to the broader bond market, particularly the yield on the 10-year U.S. Treasury note. As investor demand for U.S. government debt fluctuates in response to economic indicators, inflation expectations, and global stability concerns, the 10-year Treasury yield often serves as a bellwether for long-term borrowing costs, including mortgages. The recent climb in mortgage rates suggests an underlying increase in bond yields, reflecting heightened investor caution and expectations of sustained inflationary pressures or a more hawkish stance from the Federal Reserve. For instance, a rise of just 10 basis points in the 10-year Treasury yield can often translate to a similar increase in fixed mortgage rates, directly impacting the monthly payments for millions of prospective homeowners. This environment poses a continuous challenge for both prospective homeowners and the housing industry at large, demanding adaptability and strategic financial planning.
Demand Dynamics: Purchase vs. Refinance
The 1.9% overall increase in mortgage demand masks divergent trends within the market. Refinance demand, known for its acute sensitivity to weekly rate fluctuations, experienced a 2% decline for the week ending June 17, 2026. This drop is understandable given the rising rate environment, as fewer homeowners find it advantageous to refinance existing mortgages at higher rates than they currently hold. Homeowners who locked in historically low rates during the pandemic-era boom are largely sidelined, leaving only a smaller segment for whom refinancing makes financial sense—perhaps those with adjustable-rate mortgages resetting to higher payments or those needing to tap into equity for home improvements or debt consolidation.
However, a broader perspective reveals that refinance applications were still 7% higher than during the same week in 2025. This year-over-year increase, despite the recent weekly dip, suggests that while current rates (6.69%) are significantly higher than the record lows seen between 2020 and 2021, they are comparatively more attractive than the rates observed in June 2025. At that time, the average 30-year fixed loan was approximately 15 basis points higher, meaning current rates offer a slight improvement over last year’s figures. This nuanced view indicates that a segment of homeowners who might have missed earlier refinancing opportunities or whose financial situations have improved are still engaging with the market when rates offer even a slight advantage over their existing terms, even if weekly fluctuations temper enthusiasm.
In contrast, applications for mortgages to purchase a home demonstrated a more robust performance, rising by a notable 6% for the week. On a year-over-year basis, purchase applications remained essentially flat, registering a modest 0.2% increase. This stability, even in the face of climbing rates, is a testament to the persistent underlying demand for housing, driven by demographic shifts, evolving lifestyle preferences, and the inherent desire for homeownership. The weekly surge suggests that prospective buyers are actively monitoring market conditions, possibly timing their entry to coincide with periods of reduced competition or more favorable pricing, rather than being solely deterred by rising interest rates. This strategic behavior underscores a mature and adaptable buyer base navigating a complex market, prioritizing factors beyond just the headline interest rate.
Market Equilibrium: Inventory and Pricing Shifts
A critical factor contributing to the renewed buyer activity, despite rising rates, is the evolving inventory landscape and a noticeable shift in seller behavior. "Growing home inventory in many markets is supporting more purchase activity," observed Mike Fratantoni, senior vice president and chief economist at the MBA. After years of historically low housing stock—a consequence of underbuilding following the 2008 financial crisis and exacerbated by pandemic-driven demand—an increase in available homes provides buyers with more choices and potentially reduces the intense bidding wars that characterized earlier market phases. Data from various real estate analytics firms in late spring and early summer 2026 indicated a national inventory rise of nearly 15% year-over-year, though this varied significantly by region, with some Sun Belt markets seeing even larger increases.
This expansion of inventory is particularly evident as the market transitions into its historically slower summer months, a period when activity typically moderates as families embark on vacations and school breaks. The slowdown offers a natural cooling period, allowing supply to catch up, even marginally, with demand. The CNBC Housing Market Survey, published on July 7, 2026, corroborated this trend, with real estate agents across the country reporting an increasing willingness among sellers to cut prices. This adjustment in pricing expectations marks a significant shift from the seller-dominated markets of previous years, where multiple offers above asking price were commonplace. For example, some markets that saw rapid appreciation in 2020-2023 were now experiencing 5-10% price reductions on listings that had lingered on the market for more than 30 days.
For potential buyers, this combination of higher inventory and more flexible pricing creates a window of opportunity, allowing them to negotiate more effectively and potentially offset some of the increased costs associated with higher mortgage rates. While the overall affordability challenge persists, these market dynamics offer a slight "break" for determined buyers, enabling them to pursue homeownership with a degree of leverage not seen in recent memory. Regional variations, however, remain a crucial consideration, with some areas experiencing more significant inventory increases and price corrections than others, depending on local economic conditions, population growth, and housing development trends. Markets like Austin and Phoenix, which saw explosive growth, were experiencing more pronounced inventory buildups, while historically tight markets in the Northeast might still see modest gains.
Economic Headwinds and Geopolitical Shadows
The trajectory of mortgage rates and the broader housing market is intricately linked to macroeconomic indicators and global events. Last week brought some positive news on the inflation front, with incoming data for June 2026 showing a cooler-than-expected deceleration in price increases. This development, following months of sustained efforts by the Federal Reserve to tame inflation through successive interest rate hikes, initially offered a glimmer of hope that the central bank’s aggressive monetary tightening policies might be yielding results, potentially paving the way for a more stable interest rate environment and perhaps even a pause in future rate increases. The Consumer Price Index (CPI) for June, for example, showed a month-over-month increase that was below market expectations, leading to a temporary rally in bond markets.
However, this optimism was quickly tempered by a resurgence in energy prices. The latter half of June and early July saw crude oil prices spike significantly, pushing Brent crude futures back above $90 a barrel. This trend typically portends higher inflation in subsequent months due to increased transportation costs, higher utility bills for consumers and businesses, and broader economic impacts that filter through supply chains. As Mike Fratantoni cautioned, "with oil prices spiking again, that improvement seems unlikely to continue in July data, and mortgage rates are likely to remain higher as a result."
Adding another layer of complexity and uncertainty to the economic outlook were "new escalations in the war with Iran." This geopolitical development, occurring concurrently with the cooler inflation reports, profoundly overshadowed any positive market sentiment. The conflict, which had simmered for some time with periodic flare-ups in the Strait of Hormuz and proxy engagements in the Middle East, entered a more concerning phase in mid-2026. While specific details of the latest escalations were not immediately public, the market reacted to the heightened risk of supply disruptions in a region critical for global oil production and transit. Such instability invariably leads to increased volatility in global energy markets. The perceived risk to oil supply, even if not immediately impacting production, drives up futures prices as traders price in potential disruptions.
Matthew Graham, chief operating officer at Mortgage News Daily, succinctly captured this correlation: "For those who want to keep the analysis simple, fuel prices do a good enough job explaining the move. In fact, August gasoline futures also just hit their May 19th highs this week—perfectly aligning with the round trip in rates." This demonstrates how global events translate almost immediately into domestic borrowing costs. Geopolitical risks typically prompt investors to seek safer assets, sometimes leading to a flight to the perceived safety of government bonds, which could lower yields. However, if the conflict simultaneously fuels inflation fears (due to energy price spikes) or raises concerns about global economic growth, it can lead to a complex reaction in bond markets, sometimes pushing yields higher as investors demand greater compensation for holding debt in an uncertain environment. This complex dynamic, where inflation concerns meet geopolitical risk, has proven particularly challenging for forecasting mortgage rate movements throughout 2026.
Expert Perspectives and Forward Guidance
The analysis from industry experts paints a picture of a market in flux, driven by a confluence of domestic economic data and international events. Mike Fratantoni’s insights highlight the dual nature of current market conditions: while growing inventory provides a necessary catalyst for purchase activity, the persistent threat of inflation, exacerbated by rising energy costs and geopolitical tensions, acts as a significant upward pressure on mortgage rates. The Federal Reserve, having meticulously monitored inflation data throughout 2025 and 2026 and implementing a series of aggressive rate hikes, is now faced with the renewed challenge of balancing its mandate for price stability against potential economic slowdowns and external shocks. Any perceived shift in the Fed’s stance—whether signaling a pause in rate hikes, a continuation, or even the possibility of future cuts—would send immediate ripples through the bond market and directly impact mortgage rates. Market participants are keenly awaiting the next Federal Open Market Committee (FOMC) meeting for updated guidance on monetary policy.
Matthew Graham’s observation about the direct correlation between fuel prices and mortgage rates simplifies a complex economic interaction that extends far beyond the gas pump. Energy costs permeate nearly every sector of the economy, from manufacturing and transportation to agriculture and consumer goods and services. When oil and gasoline prices rise, businesses face higher operational costs, which are often passed on to consumers in the form of higher prices, thereby fueling broader inflation. This inflationary pressure, in turn, influences the Federal Reserve’s monetary policy decisions and bond market expectations, ultimately translating into higher long-term interest rates for consumers and businesses. The synchronization of August gasoline futures hitting their May 19th highs with mortgage rates matching their mid-May peaks offers a tangible illustration of this economic feedback loop, demonstrating the swift and direct impact of commodity markets on borrowing costs.
The Homebuyer’s Dilemma: Navigating the Current Climate
For prospective homebuyers, the current market presents a nuanced dilemma. On one hand, the increased inventory and sellers’ willingness to cut prices offer a glimmer of hope for finding a suitable property without
